Comment

EIA Natural Gas Storage: Prices Jump 37 Ticks on Smaller-Than-Expected 67 Bcf Build

According to our analysis, the 15 October 2026 DOE Weekly Natural Gas Storage Report (WNGSR) generated an immediate 37-tick move in natural gas.

Natural gas (37 ticks)
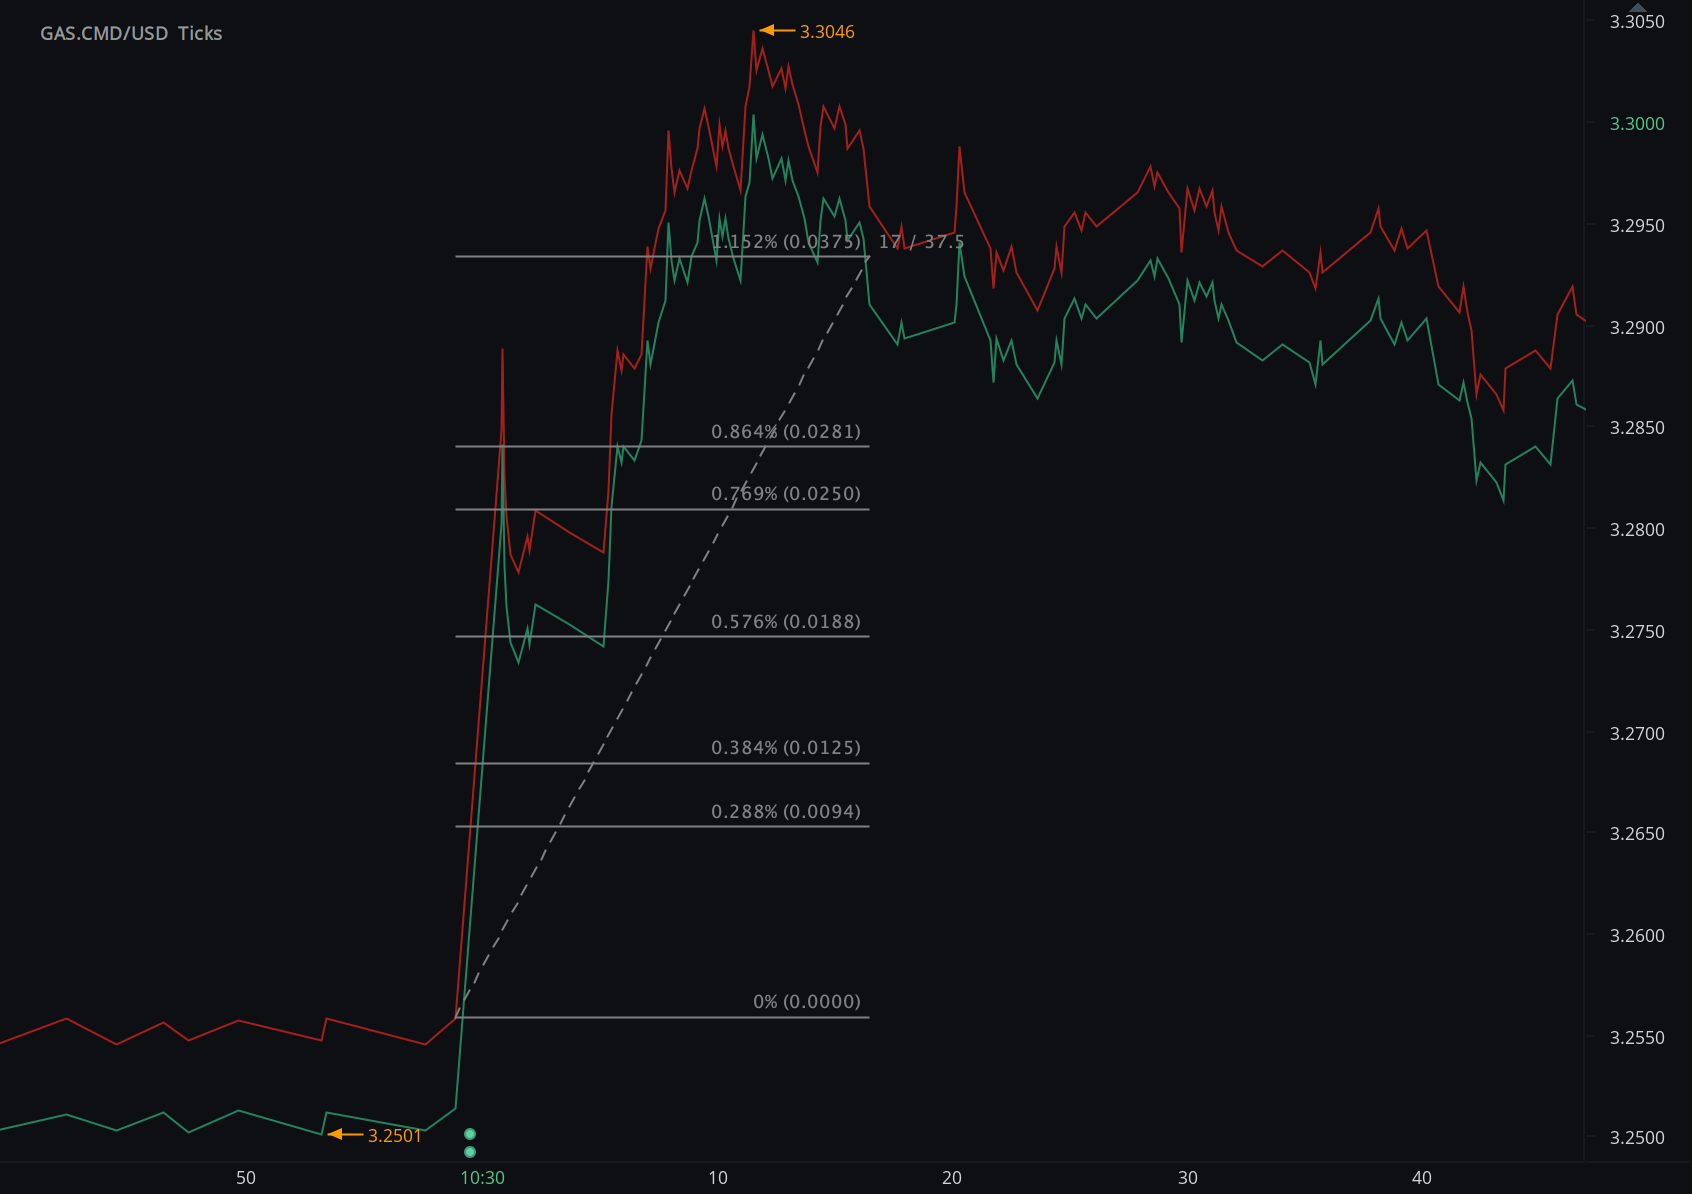
Charts are exported from JForex (Dukascopy).


HAAWKS Research

EIA Natural Gas Storage: Prices Jump 37 Ticks on Smaller-Than-Expected 67 Bcf Build

U.S. working natural-gas inventories increased less than expected in the week ending October 9, narrowing the storage surplus to the five-year average and triggering an immediate upward repricing.

15 October 2026 • 10:30 a.m. ET • EIA Weekly Natural Gas Storage Report • Natural Gas +37 ticks

The U.S. Energy Information Administration reported a 67 billion cubic foot injection into underground natural-gas storage for the week ending October 9, 2026.

The increase was materially smaller than pre-release expectations. A Wall Street Journal survey placed the analyst average at approximately 75 Bcf, while AEGIS reported a median estimate of 74 Bcf.

The smaller-than-expected build reduced the cushion between current inventories and the five-year seasonal average, providing a tighter storage signal as the market approached the end of the traditional injection season.

HAAWKS release-window measurement: U.S. natural gas rose approximately 37 ticks immediately following publication of the EIA storage data.

October 15 Storage Report at a Glance

Weekly Injection +67 Bcf Week ending October 9
WSJ Survey +75 Bcf Approximate analyst average
Total Storage 3,567 Bcf Lower 48 working gas
HAAWKS Reaction +37 Ticks Immediate release window

Immediate Natural-Gas Market Response

Release-Window Movement

+37 Ticks

HAAWKS measured a rapid upward repricing in natural gas following the 10:30 a.m. ET publication.

The direction of the move was consistent with a storage injection that came in below market expectations and below the normal seasonal build.

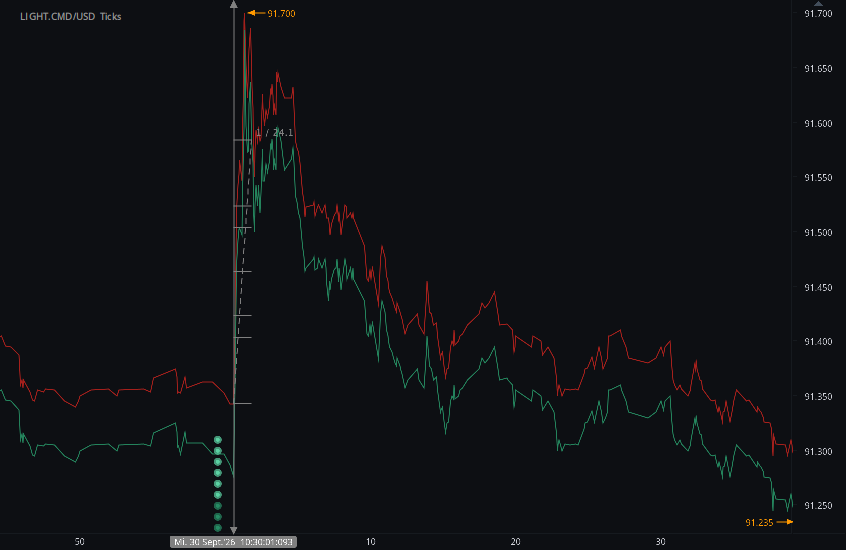
The attached HAAWKS tick-level chart shows the repricing beginning immediately after publication, with prices accelerating higher as the market incorporated the smaller inventory build.

The distinction between the immediate release response and the broader trading session is important. The HAAWKS measurement isolates the first market adjustment around publication rather than the full day's change.

Actual vs. Expectations

Measure Reference October 15 Result Interpretation
Weekly Storage Change WSJ survey: +75 Bcf +67 Bcf Approximately 8 Bcf below the cited survey average
AEGIS Median +74 Bcf +67 Bcf 7 Bcf below the reported median
Previous Week +85 Bcf +67 Bcf Weekly injection slowed by 18 Bcf
Five-Year Weekly Average Approximately +90 Bcf +67 Bcf Injection was materially below seasonal norms
HAAWKS view: the principal information surprise was not that inventories increased, but that they increased considerably less than anticipated. For storage-sensitive markets, the relevant signal is the deviation from expectations and seasonal norms rather than the sign of the weekly change alone.

Storage Surplus Narrows Further

Total Lower 48 working gas reached 3,567 Bcf, up from 3,500 Bcf one week earlier.

Despite the weekly injection, inventories remained 143 Bcf below the year-earlier level of 3,710 Bcf, equivalent to a year-on-year deficit of approximately 3.9%.

Relative to the five-year average, storage remained modestly elevated. The EIA reported a five-year average of 3,522 Bcf, leaving current inventories 45 Bcf, or 1.3%, above normal.

That surplus had been 68 Bcf one week earlier. The October 15 report therefore continued the recent erosion of the storage cushion.

Regional Storage Flows

The national 67 Bcf injection was not evenly distributed across storage regions.

Region October 9 Stocks Weekly Change vs. Five-Year Average
East 884 Bcf +22 Bcf +3.3%
Midwest 1,037 Bcf +27 Bcf +2.0%
Mountain 255 Bcf +2 Bcf +5.4%
Pacific 294 Bcf −5 Bcf +6.5%
South Central 1,097 Bcf +21 Bcf −3.1%

Within the South Central region, salt facilities added 9 Bcf while nonsalt facilities added 12 Bcf.

South Central stocks remained below their five-year average, while the East, Midwest, Mountain and Pacific regions remained above their respective seasonal norms.

Why a 67 Bcf Injection Was Supportive

Weekly natural-gas storage data are inherently relative. An injection increases inventories in absolute terms, but that does not automatically make the release bearish.

Expectation Gap

The 67 Bcf build was roughly 7–8 Bcf below the principal consensus measures reviewed by HAAWKS.

Seasonal Comparison

The build was also considerably smaller than the approximately 90 Bcf five-year average for the corresponding week.

Shrinking Surplus

The inventory surplus to the five-year average declined to only 45 Bcf as the market moved closer to winter.

Year-on-Year Deficit

Inventories remained 143 Bcf below the corresponding year-earlier level despite continued injections.

Implications for Real-Time Market Intelligence

The Actual Number Is Only the First Field

A machine-readable feed that distributes only the 67 Bcf headline does not capture the complete information set.

Real-time interpretation also benefits from the consensus estimate, previous week's change, regional composition, five-year comparison and year-on-year storage position.

Consensus Sources Can Differ

The Wall Street Journal survey indicated approximately 75 Bcf, while AEGIS reported a 74 Bcf median. Other market calendars cited figures around 76 Bcf.

For systematic research, the specific consensus source should therefore be preserved alongside the official release rather than treated as a universal value.

Seasonality Is Part of the Signal

Storage data require comparison with normal seasonal behavior. A 67 Bcf injection in October carries different information content from the same injection during another part of the refill season.

Regional Composition Matters

Aggregate Lower 48 inventories can conceal materially different regional conditions. The South Central region remained below its five-year average even while national stocks remained modestly above normal.

Precise Release Timing Matters

The report was published at 10:30 a.m. ET. The HAAWKS analysis focuses on the immediate market response around that scheduled publication timestamp.

Release-Window Analysis

HAAWKS measured approximately 37 ticks of upward natural-gas movement following the storage report.

The price response was consistent with a tighter-than-expected storage outcome, but the measurement should be distinguished from a claim that the report alone explains every subsequent market move.

After the initial repricing, natural-gas prices can respond to production, weather forecasts, LNG feedgas demand, pipeline flows, broader energy-market conditions, positioning and liquidity.

Market-intelligence takeaway: the October 15 release demonstrates why storage data are best processed as a multidimensional information set. The actual injection, consensus deviation, seasonal benchmark, regional composition and inventory trajectory all contribute to the information absorbed during the first seconds after publication.

HAAWKS Conclusion

The October 15 EIA Weekly Natural Gas Storage Report showed a 67 Bcf injection for the week ending October 9.

The result was below the approximately 74–75 Bcf consensus measures reviewed by HAAWKS and materially below the seasonal five-year average build.

Total working gas increased to 3,567 Bcf. Stocks remained 45 Bcf above the five-year average but were 143 Bcf below the corresponding level one year earlier.

HAAWKS measured natural gas approximately 37 ticks higher in the immediate release window.

The event reinforces the importance of combining low-latency official data with consensus expectations, historical comparisons and field-level storage detail when evaluating scheduled energy-market releases in real time.

Real-Time Data. Structured Intelligence. Professional Markets.

Low-Latency Energy and Macroeconomic Data

HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data covering the United States, Canada and Europe.

The feed supports systematic strategies, professional trading desks and latency-sensitive applications requiring field-level data as official releases become public.

API infrastructure is available in Chicago, New York and London. Free trials are available for qualified financial institutions.

Explore HAAWKS G4A

Sources

  1. U.S. Energy Information Administration — Weekly Natural Gas Storage Report
    Official source for the October 15, 2026 storage report, Lower 48 inventories, regional flows and historical comparisons.
  2. The Wall Street Journal — U.S. Natural Gas Futures and Storage Expectations
    Source for the approximately 75 Bcf analyst survey and seasonal weekly comparison.
  3. AEGIS Market Insights — Weekly Gas Statistics, October 15, 2026
    Source for the 74 Bcf median estimate and cited analyst range.
  4. HAAWKS internal tick-level market analysis — October 15, 2026
    Source for the measured immediate natural-gas +37 tick release-window movement.
Data note: EIA storage figures are official published estimates. Pre-release expectations vary across surveys and providers. This article identifies the specific consensus sources used for comparison. HAAWKS market-movement figures are internal release-window measurements.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The 37-tick movement represents historical market movement measured around the release and does not represent guaranteed or necessarily achievable trading profit. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for speed-sensitive market participants. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data through API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for qualified financial institutions.

Comment

October 2026 WASDE: Corn, Soybeans and Wheat Reprice Lower on Heavier Supply

Comment

October 2026 WASDE: Corn, Soybeans and Wheat Reprice Lower on Heavier Supply

According to our analysis ZC went down 72 ticks, ZW went down 52 ticks and ZS went down 76 ticks (total: 200 ticks) on USDA World Agricultural Supply and Demand Estimates (WASDE) data on 9 October 2026.


HAAWKS Research

October 2026 WASDE Drives Broad Repricing Across Corn, Wheat and Soybeans

USDA raised key U.S. supply estimates across the grain complex, including a materially larger corn yield, production forecast and projected carryout, prompting a synchronized decline across CBOT agricultural futures.

9 October 2026 • Release time: 12:00 p.m. ET • USDA WASDE • 200 measured ticks

The October 2026 World Agricultural Supply and Demand Estimates delivered a broadly heavier U.S. supply outlook across corn, soybeans and wheat, generating a rapid repricing across the CBOT grain complex.

The most significant statistical deviation was concentrated in corn. USDA raised the national yield to 181.2 bushels per acre, compared with a Dow Jones survey average of 177.6 bushels per acre.

U.S. corn production was consequently raised to 16.034 billion bushels, while projected 2026/27 ending stocks increased to 1.849 billion bushels.

Soybean production and ending stocks also moved higher, while the U.S. wheat balance incorporated lower exports and higher projected carryout.

HAAWKS release-window measurement: soybean futures ZS fell 76 ticks, corn futures ZC fell 72 ticks, and Chicago wheat ZW fell 52 ticks around publication of the October WASDE.

Immediate Cross-Grain Market Response

Soybeans — ZS −76 Ticks HAAWKS release-window measurement
Corn — ZC −72 Ticks HAAWKS release-window measurement
Wheat — ZW −52 Ticks HAAWKS release-window measurement

Across the three contracts, HAAWKS measured 200 instrument-specific ticks of absolute release-window movement.

These figures describe contract-specific price changes and should not be interpreted as standardized returns. Tick values differ by futures contract.

October WASDE vs. Pre-Release Expectations

The market significance of the October update was driven not simply by the direction of USDA revisions, but by the difference between the official figures and the expectations embedded before publication.

The estimates below are from the Dow Jones survey of analysts, as reproduced by DTN ahead of the October 9 release.

Indicator September Dow Jones Average October USDA Difference vs. Average
Corn Yield 178.5 bpa 177.6 bpa 181.2 bpa +3.6 bpa
Corn Production 15.800B bu 15.716B bu 16.034B bu +318M bu
Corn Ending Stocks 1.567B bu 1.677B bu 1.849B bu +172M bu
Soybean Yield 52.8 bpa 52.9 bpa 53.1 bpa +0.2 bpa
Soybean Production 4.535B bu 4.541B bu 4.562B bu +21M bu
Soybean Ending Stocks 310M bu 311M bu 315M bu +4M bu
Wheat Ending Stocks 717M bu 722M bu 740M bu +18M bu

Estimate source: Dow Jones analyst survey reproduced by DTN. Consensus estimates can differ across surveys and data providers; this article therefore identifies the specific survey used for each comparison.

HAAWKS view: the corn balance carried the largest surprise relative to expectations. The October corn yield, production and ending-stock estimates all came in materially above the cited survey averages, while soybean and wheat balances also incorporated somewhat larger U.S. supplies or carryout.

Corn: Supply Expansion Dominates the October Update

Corn contained the clearest supply-side revision in the October WASDE.

USDA increased the national yield by 2.7 bushels per acre from September to 181.2 bushels per acre.

That was 3.6 bushels per acre above the Dow Jones survey average of 177.6 and near the upper end of the cited 173.2 to 182.1 bpa estimate range.

U.S. Corn Yield 181.2 Bushels per acre
U.S. Production 16.034B Bushels
Ending Stocks 1.849B 2026/27 bushels

The higher yield lifted projected production by 234 million bushels from September to 16.034 billion.

Beginning stocks were also raised by 173 million bushels to reflect the updated September 1 inventory position.

USDA increased projected demand as well. Total use rose by 125 million bushels, including higher feed and residual use, ethanol use and exports.

2026/27 Corn Balance September October Monthly Change
Beginning Stocks 1.922B bu 2.095B bu +173M
Production 15.800B bu 16.034B bu +234M
Feed & Residual 5.950B bu 6.000B bu +50M
Ethanol 5.600B bu 5.650B bu +50M
Exports 3.275B bu 3.300B bu +25M
Ending Stocks 1.567B bu 1.849B bu +282M

The important balance-sheet result was that the increase in supply substantially exceeded the increase in projected use.

USDA consequently raised ending stocks by 282 million bushels and reduced the projected season-average farm price by $0.10 to $4.70 per bushel.

Global Corn Stocks Also Exceed Expectations

The U.S. supply revision carried through into the global balance.

USDA raised projected 2026/27 world corn ending stocks to 280.4 million metric tons, up from 272.1 million in September.

The Dow Jones survey average was 273.9 million metric tons, with an estimate range of 272.0 to 279.8 million.

The official estimate therefore came in approximately 6.5 million metric tons above the survey average and slightly above the highest estimate in the cited range.

USDA attributed most of the increase in global corn stocks to the larger U.S. inventory position.

Soybeans: Record Production Estimate Moves Higher

The soybean revisions were smaller than those in corn, but the U.S. balance still shifted toward greater supply.

USDA raised the national soybean yield to 53.1 bushels per acre, up 0.3 bushel from September and 0.2 bushel above the Dow Jones survey average.

Production increased by 27 million bushels from September to a record 4.562 billion bushels.

U.S. Soybean Yield 53.1 Bushels per acre
U.S. Production 4.562B Bushels
Ending Stocks 315M 2026/27 bushels

Beginning stocks were reduced by 10 million bushels, partially offsetting the larger crop.

USDA also increased exports by 10 million bushels to 1.695 billion, while the crush forecast remained unchanged at 2.780 billion bushels.

The net result was a 5-million-bushel increase in projected U.S. soybean ending stocks to 315 million bushels, compared with the Dow Jones average estimate of 311 million.

2026/27 Soybean Balance September October Monthly Change
Yield 52.8 bpa 53.1 bpa +0.3 bpa
Production 4.535B bu 4.562B bu +27M
Exports 1.685B bu 1.695B bu +10M
Ending Stocks 310M bu 315M bu +5M

Globally, soybean ending stocks increased slightly to 124.3 million metric tons, compared with the Dow Jones average of 123.8 million.

Unlike corn, the soybean balance did not contain one dominant statistical surprise. Rather, several moderately heavier supply components arrived together.

Wheat: Lower Exports Raise U.S. Carryout

The October U.S. wheat outlook shifted toward higher supplies, increased domestic use, reduced exports and larger ending stocks.

USDA projected U.S. wheat production at 1.534 billion bushels, while exports were reduced by 25 million bushels to 750 million.

Feed and residual use increased by 10 million bushels, but the export reduction was large enough to push projected ending stocks higher.

U.S. Wheat Production 1.534B Bushels
U.S. Exports 750M Down 25M from September
Ending Stocks 740M Up 23M from September

Projected U.S. ending stocks increased from 717 million to 740 million bushels.

That was also above the Dow Jones survey average of 722 million bushels.

USDA reduced the season-average wheat price forecast by $0.10 to $6.30 per bushel.

The global balance was less directional. World wheat ending stocks were projected at 276.0 million metric tons, slightly below both September and the cited 276.8-million-ton survey average.

Three Contracts, Different Statistical Profiles

Corn

The largest deviations from expectations were concentrated in corn, with materially higher yield, production, domestic ending stocks and global ending stocks.

Soybeans

Soybean yield, production and ending stocks all moved modestly above the cited survey averages, producing a somewhat heavier balance than anticipated.

Wheat

U.S. wheat carryout moved higher as exports were reduced, although global ending stocks remained broadly stable and slightly below the cited survey average.

Market Response

Despite different underlying statistical profiles, HAAWKS measured simultaneous downside repricing across ZC, ZS and ZW during the immediate release window.

Why WASDE Requires Multi-Field Processing

WASDE cannot be reduced to a single production or ending-stock number. The report updates multiple interconnected components of domestic and global supply-and-demand balances simultaneously.

Information Set Relevant Fields Analytical Function
Production Yield, harvested acreage and crop size Establishes the current domestic supply outlook.
Beginning Stocks Carry-in from the prior marketing year Can materially change total supply before current crop production is considered.
Domestic Demand Feed, ethanol, crush, seed and residual Determines how rapidly available supply is projected to be consumed domestically.
Exports U.S. export forecasts and global trade flows Connects domestic balances with global demand and relative competitiveness.
Ending Stocks U.S. and global carryout Summarizes the residual balance after projected supply and usage.
Price Forecasts Season-average farm prices Provides USDA's updated price framework after balance-sheet revisions.

Implications for Event-Driven Commodity Strategies

Consensus Is Part of the Information Set

A production number has different market information content depending on what was expected immediately before publication.

In October, the corn production forecast of 16.034 billion bushels was approximately 318 million bushels above the Dow Jones survey average.

Several Fields Can Reinforce the Same Direction

The corn signal was strengthened because higher yield and production arrived alongside larger beginning stocks and substantially higher projected ending stocks.

Demand was increased, but not enough to absorb the supply revision.

Not Every Crop Has the Same Information Structure

Soybeans delivered smaller differences relative to expectations, while wheat combined higher U.S. carryout with a comparatively stable global balance.

A robust framework therefore needs crop-specific and field-specific interpretation rather than a single aggregate classification.

Domestic and Global Balances Should Be Processed Together

Corn provided a particularly clear example in October. Larger U.S. stocks flowed directly into a substantial increase in projected world carryout.

In wheat, by contrast, higher U.S. ending stocks were accompanied by slightly lower projected global ending stocks.

Release Vintage Matters

Systematic historical research benefits from preserving the exact USDA figures and consensus expectations available at the publication timestamp.

Using only subsequently revised historical databases can obscure the actual information set that markets processed in real time.

Tick Movement Is Instrument-Specific

The measured ZS, ZC and ZW movements describe contract-specific price changes around publication. The 200-tick aggregate is a sum of absolute contract movements, not a standardized portfolio return.

Release-Window Repricing vs. the Broader Session

HAAWKS measured ZS 76 ticks lower, ZC 72 ticks lower and ZW 52 ticks lower during the immediate response to the October WASDE.

These measurements isolate the first repricing around the scheduled 12:00 p.m. ET publication rather than the direction of each market over the full trading session.

Subsequent price action can reflect liquidity, positioning, harvest progress, export demand, weather, inter-commodity spreads and broader commodity-market conditions.

HAAWKS view: October illustrates how a synchronized cross-grain move can emerge from different underlying data structures. Corn delivered the clearest supply surprise, while soybeans and wheat contained more moderate revisions. Real-time interpretation therefore requires both rapid extraction and field-level differentiation.

HAAWKS Conclusion

The October 9 USDA WASDE produced a broad downside repricing across major CBOT grain contracts.

Corn contained the largest statistical surprise. USDA raised the national yield to 181.2 bushels per acre and production to 16.034 billion bushels, both materially above the cited Dow Jones survey averages.

Projected U.S. corn ending stocks increased to 1.849 billion bushels, approximately 172 million above the cited survey average and 282 million above the September forecast.

Soybean production increased to 4.562 billion bushels and ending stocks to 315 million bushels, while U.S. wheat ending stocks increased to 740 million bushels as projected exports were reduced.

HAAWKS measured immediate release-window movements of ZS −76 ticks, ZC −72 ticks and ZW −52 ticks, equivalent to 200 instrument-specific ticks across the three contracts.

For professional market infrastructure, the October release reinforces the importance of processing WASDE as a multidimensional information set. Yield, production, beginning stocks, domestic consumption, exports, U.S. ending stocks and global balances can all change at the same publication timestamp.

The ability to evaluate those fields against pre-release expectations in real time is central to understanding the first market response.

Real-Time Data. Structured Intelligence. Professional Markets.

Real-Time Agricultural Data for Professional Markets

HAAWKS G4A provides low-latency, structured macroeconomic and commodity data covering the United States, Canada and Europe.

The feed supports systematic strategies, professional trading desks and latency-sensitive applications requiring field-level economic and commodity data as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. USDA — World Agricultural Supply and Demand Estimates, October 9, 2026
    Official source for U.S. and global corn, soybean and wheat supply-and-demand forecasts.
  2. USDA — WASDE Report
    Official USDA WASDE publication page and release schedule.
  3. DTN — October USDA Reports Preview
    Source for the Dow Jones pre-release analyst survey averages and estimate ranges used in this analysis.
  4. DTN — October WASDE Report Summary
    Additional post-release comparison of USDA figures with the Dow Jones analyst survey.
  5. HAAWKS internal tick-level market analysis — October 9, 2026
    Source for the measured immediate release-window movements: ZS −76 ticks, ZC −72 ticks and ZW −52 ticks.
Data note: USDA figures are official published statistics and forecasts. Pre-release expectations referenced in this article are from the Dow Jones analyst survey reproduced by DTN and may differ from estimates produced by other surveys or data providers. HAAWKS market-movement figures are internal release-window measurements.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured release-window movements and do not represent guaranteed or necessarily achievable trading profits. Tick values are contract-specific. The 200-tick aggregate represents the sum of absolute measured movements across ZS, ZC and ZW and is not a standardized rate of return. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

Canada Labour Force Survey: USD/CAD Rises 32 Pips After 68,000 Employment Decline

According to our analysis USD/CAD moved 32 pips on Canada Labour Force Survey (LFS) data on 9 October 2026.

USD/CAD (32 pips)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Canada Labour Force Survey: USD/CAD Rises 32 Pips as Employment Falls 68,000

Canada's September labour report delivered a substantial downside employment surprise, weakening the Canadian dollar and prompting an immediate repricing of Bank of Canada expectations.

9 October 2026 • Release time: 8:30 a.m. ET • Statistics Canada Labour Force Survey • USD/CAD +32 pips

Statistics Canada's September 2026 Labour Force Survey delivered a considerably weaker employment result than markets had expected, producing an immediate repricing in the Canadian dollar and domestic rate expectations.

Canadian employment declined by approximately 68,000 in September, following a decline of roughly 42,000 in August.

A Reuters survey of economists had anticipated an increase of 9,200 jobs. The difference between the reported result and the survey average was therefore approximately 77,500 jobs to the downside.

The unemployment rate increased by 0.1 percentage point to 6.5%, matching the Reuters consensus forecast. The employment surprise, rather than the unemployment-rate headline, was therefore the clearest deviation from pre-release expectations.

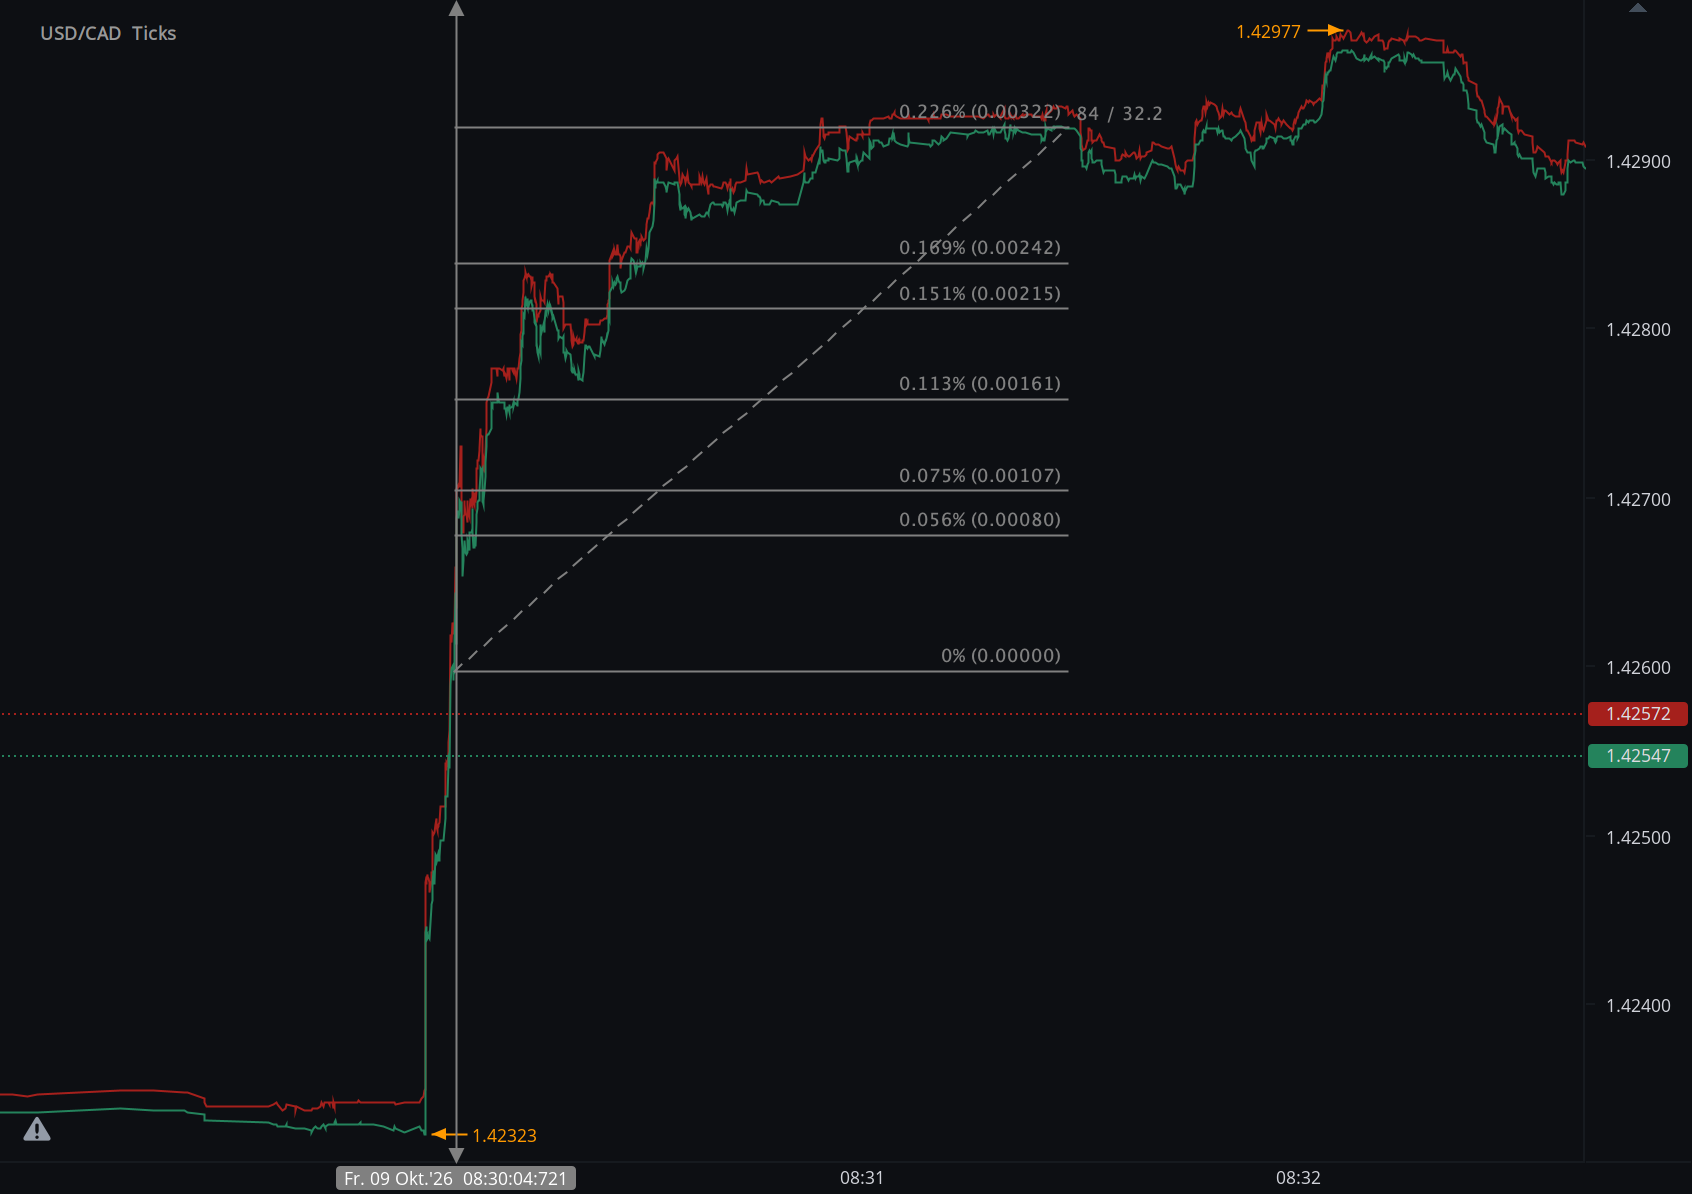
HAAWKS release-window measurement: USD/CAD rose approximately 32 pips following publication of the September Labour Force Survey, reflecting an immediate weakening of the Canadian dollar against the U.S. dollar.

Immediate USD/CAD Market Response

USD/CAD Release-Window Movement

+32 Pips

HAAWKS measured a rapid upward repricing in USD/CAD after the 8:30 a.m. ET publication.

A rise in USD/CAD corresponds to a weaker Canadian dollar relative to the U.S. dollar. The measurement represents market movement around the release, not necessarily achievable trading P&L.

The HAAWKS tick-level chart shows the currency pair moving sharply higher immediately after publication as the market incorporated the weaker employment data.

Reuters subsequently reported that USD/CAD traded as high as approximately 1.4298, corresponding to the weakest level for the Canadian dollar against the U.S. dollar since April 2025.

The broader session move therefore remained directionally consistent with the initial release-window response measured by HAAWKS.

Actual Data vs. Pre-Release Expectations

Indicator Previous Reuters Consensus September Actual Release Signal
Employment Change −41.7K +9.2K −68.3K Large downside surprise
Unemployment Rate 6.4% 6.5% 6.5% In line
Participation Rate 65.0% — 64.8% −0.2 ppt
Employment Rate 60.8% — 60.6% −0.2 ppt
Average Hourly Wages +2.0% YoY — +2.3% YoY Wage growth accelerated
HAAWKS view: the employment headline carried the dominant surprise. The unemployment rate itself matched the Reuters survey, while wage growth accelerated. The release was therefore not uniformly weak across every field, but the scale of the employment decline provided a clear negative labour-demand signal.

The Composition of the Employment Decline

The headline decline was broad enough to matter beyond a single employment category.

Full-time employment fell by approximately 35,000, while part-time employment declined by approximately 33,000.

Total Employment −68K September monthly change
Full-Time −35K −0.2% month over month
Part-Time −33K −0.9% month over month
Employment Rate 60.6% Down 0.2 percentage point

September represented a second consecutive monthly employment decline. Statistics Canada reported employment down by approximately 42,000 in August after gains earlier in the year.

Despite the recent weakness, total employment remained approximately 95,000 higher than one year earlier, an increase of about 0.5%.

Public-Sector Employment Drives Much of the Weakness

One of the most important details beneath the national headline was the continued decline in public-sector employment.

Statistics Canada reported that the number of public-sector employees fell by approximately 70,000 in September, or 1.5%.

This represented a fourth consecutive monthly decline in public-sector employment. Compared with September 2025, the number of public-sector employees was down approximately 119,000.

Private-sector employment was little changed during the month, while self-employment edged down by approximately 23,000.

Class of Worker September Change Year-on-Year Context
Public Sector −70K −119K / −2.6%
Private Sector Little changed +163K / +1.2%
Self-Employment −23K +51K / +1.9%

Employment Weakness Concentrated in Several Major Industries

The industry breakdown showed losses across education, health-related services and manufacturing.

Industry September Employment Change Monthly Percentage Change
Educational Services −35K −2.2%
Health Care & Social Assistance −23K −0.8%
Manufacturing −13K −0.7%
Other Services +17K +2.1%

Manufacturing is particularly relevant for macro analysis given its exposure to cross-border trade and U.S.-Canada economic conditions. However, the largest monthly losses were recorded in educational services and health care and social assistance.

Participation Falls to 64.8%

The labour-force participation rate declined by 0.2 percentage point to 64.8%.

Statistics Canada noted that this was the lowest participation rate since December 1997, excluding the exceptional conditions during 2020.

The agency emphasized that population aging is an important structural contributor to the decline in participation.

People aged 65 and older represented 23.2% of the working-age population in September 2026, compared with 20.5% in September 2019.

Analytical distinction: a decline in participation can limit the increase in the unemployment rate even when employment falls materially. For real-time interpretation, employment, unemployment and participation therefore need to be processed together rather than treated as independent headlines.

Youth Employment Accounts for a Significant Share of the Decline

Employment among people aged 15 to 24 fell by approximately 48,000, or 1.8%, in September.

It was the second consecutive monthly decline for youth employment. Over August and September combined, youth employment decreased by approximately 67,000.

The number of young people participating in the labour force also declined, helping keep the youth unemployment rate broadly unchanged at approximately 13.0%.

This is another example of why the unemployment rate alone can provide an incomplete reading of labour-market momentum.

Regional Labour-Market Divergence

Employment weakness was not evenly distributed across Canada.

Province Employment Change Monthly Change Unemployment Rate
Quebec −49K −1.1% 6.0%
British Columbia −20K −0.7% 6.4%
Ontario −20K −0.2% 7.0%
Alberta +23K +0.9% 6.4%

Quebec recorded the largest provincial employment decline, while Alberta moved in the opposite direction with an increase of approximately 23,000 jobs.

Wage Growth Prevents an Unambiguously Soft Reading

Average hourly wages among employees increased 2.3% year over year in September, compared with 2.0% in August.

The average hourly wage level increased by approximately $0.86 to $37.64 from a year earlier.

From a monetary-policy perspective, that detail matters. Employment growth weakened substantially, but wage growth did not simultaneously decelerate.

The report therefore contained a strong negative employment surprise alongside a somewhat firmer wage signal.

Bank of Canada Expectations Reprice

The currency response was accompanied by a shift in Canadian interest-rate expectations.

Reuters reported that investors reduced the implied probability of a Bank of Canada rate increase at the October meeting to approximately 25%, from around 40% before the employment report.

Canadian government bond yields also moved lower as markets incorporated a weaker near-term labour outlook.

This transmission mechanism is central to understanding the USD/CAD response:

Employment Surprise

Employment fell substantially instead of delivering the modest increase expected by the Reuters survey.

Policy Expectations

A weaker labour backdrop reduced the market-implied probability of near-term Bank of Canada tightening.

Canadian Rates

Lower policy expectations were accompanied by lower Canadian government bond yields.

FX Transmission

The resulting relative-rate repricing was consistent with a weaker Canadian dollar and higher USD/CAD.

Why the Labour Force Survey Requires Multi-Field Processing

The September release demonstrates why professional real-time economic data infrastructure cannot rely on a single headline field.

Within one publication, the market received information on employment, unemployment, participation, full-time and part-time work, wages, public and private employment, industry-level changes, demographics and regional labour markets.

Data Field September Reading Why It Matters
Employment Change −68K Primary measure of monthly labour demand and the largest consensus surprise.
Unemployment Rate 6.5% Important policy variable, but matched the cited consensus.
Participation Rate 64.8% Helps explain movements in unemployment and labour supply.
Full-Time / Part-Time −35K / −33K Shows the composition and breadth of employment changes.
Wage Growth +2.3% YoY Adds information relevant to domestic inflation pressure and monetary policy.
Industry Breakdown Education, health care and manufacturing lower Helps distinguish broad labour weakness from isolated sector volatility.

Implications for Event-Driven Macro Strategies

Consensus Is Part of the Information Set

Employment falling by 68,300 is economically relevant on its own, but its immediate market significance was amplified by the fact that economists surveyed by Reuters had expected an increase of 9,200.

The approximately 77,500-job gap between actual and expected employment provided the clearest quantitative surprise in the release.

Not Every Field Pointed in the Same Direction

Employment was substantially weaker, participation declined and the employment rate fell. At the same time, unemployment matched the consensus estimate and wage growth accelerated.

Automated interpretation therefore benefits from evaluating multiple fields rather than assigning a directional signal from one headline.

Cross-Market Confirmation Matters

The Canadian dollar weakened while domestic yields declined and expectations for near-term Bank of Canada tightening were reduced. That cross-market response provides additional context for the initial USD/CAD move.

The Immediate Window Should Be Separated from the Session

HAAWKS measured approximately 32 pips of USD/CAD movement around the release itself.

Later session prices reflected not only the original Labour Force Survey but also subsequent liquidity, broader U.S. dollar movement, commodity prices, positioning and other market information.

Release Vintage Matters

Historical systematic research is most robust when it preserves the exact values, expectations and timestamps available when the release became public rather than relying solely on later databases.

HAAWKS Conclusion

Canada's September Labour Force Survey delivered a substantial downside employment surprise.

Employment fell by approximately 68,000, compared with a Reuters consensus forecast for an increase of 9,200.

The unemployment rate increased to 6.5%, matching expectations, while labour-force participation declined to 64.8%.

Employment weakness was distributed across full-time and part-time work and was particularly visible in public-sector employment, educational services, health care and social assistance, manufacturing and youth employment.

Wage growth provided a countervailing signal, accelerating to 2.3% year over year.

HAAWKS measured USD/CAD approximately 32 pips higher during the immediate release window as the Canadian dollar weakened and markets reduced expectations for near-term Bank of Canada tightening.

For professional market infrastructure, the release reinforces the importance of combining official data, consensus expectations, supporting labour-market fields and precise timestamps in one structured real-time framework.

Real-Time Data. Structured Intelligence. Professional Markets.

Real-Time Canadian Economic Data

HAAWKS G4A provides low-latency, structured macroeconomic and commodity data covering the United States, Canada and Europe.

The feed supports systematic strategies, professional trading desks and latency-sensitive applications requiring field-level economic data as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. Statistics Canada — Labour Force Survey, September 2026
    Official source for employment, unemployment, participation, wage, industry, demographic and provincial labour-market data.
  2. Reuters — Canada's Employment Unexpectedly Shrinks in September
    Source for the pre-release economist survey: employment +9,200 expected and unemployment rate 6.5% expected, as well as initial market reaction.
  3. Reuters — Canadian Dollar Hits 18-Month Low as Jobs Data Clips Rate-Hike Bets
    Source for subsequent Canadian-dollar performance and changes in market-implied Bank of Canada policy expectations.
  4. HAAWKS internal tick-level market analysis — 9 October 2026
    Source for the measured immediate release-window movement of USD/CAD +32 pips.
Data note: Statistics Canada figures are official published statistics. Pre-release expectations are based on the Reuters economist survey referenced above and may differ from estimates published by other providers. HAAWKS market-movement figures are internal release-window measurements.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The 32-pip USD/CAD movement represents historical market movement measured around the release and does not represent guaranteed or necessarily achievable trading profit. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Q3 2026 HAAWKS Real-Time Market Intelligence Briefing

Comment

Q3 2026 HAAWKS Real-Time Market Intelligence Briefing

We are pleased to report that, based on our ex-post analysis, the 11 selected events in the third quarter of 2026 generated a cumulative indicative potential of 875 pips/ticks and 185 XAU/USD points. For comparison, the corresponding potential performance measured across 2025 was 1,828 pips/ticks.

Q3 2026

Cumulative Potential — Indicative Performance for Q3 2026. Please see the individual releases below for detailed analysis.

For detailed analysis, click on any release below to view the full HAAWKS research note.


HAAWKS Research

Q3 2026 HAAWKS Real-Time Market Intelligence Briefing: Macro, Energy and Agricultural Repricing

Eleven scheduled information events across U.S. macroeconomics, energy and agriculture generated repeated short-horizon repricing across FX, equities, precious metals and commodity futures during the third quarter of 2026.

July–September 2026 • 11 Releases • 8 Release Dates • HAAWKS Real-Time Market Intelligence Briefing

The third quarter of 2026 provided a diverse set of scheduled information events spanning employment, inflation, economic growth, petroleum and natural-gas inventories, agricultural supply-and-demand balances and physical grain stocks.

Across the eleven releases reviewed by HAAWKS, the recurring theme was not simply volatility. The more important observation was how quickly markets differentiated between headline figures, supporting fields, prior-period revisions, consensus expectations and simultaneous information arriving at the same timestamp.

Using the HAAWKS cumulative-potential convention, the quarter produced 875 pips/ticks of indicative release-window movement, with a further 185 points measured in XAU/USD.

Those figures describe historical price movement around the selected publication windows. They are not standardized investment returns and should not be interpreted as automatically executable P&L.

Quarterly measurement: July contributed 271 pips/ticks and 77 XAU/USD points, August contributed 117 pips/ticks and 17 XAU/USD points, and September contributed 487 pips/ticks and 91 XAU/USD points.

Q3 2026 at a Glance

Releases Analysed 11 Across macro, energy and agriculture
Q3 Indicative Potential 875 Pips / ticks under HAAWKS convention
XAU/USD Movement 185 Points across selected macro releases
2026 Cumulative 1,902 HAAWKS pips/ticks indicator at 30 September

Quarterly Distribution by Month

July

271 Pips / ticks + 77 XAU/USD points

June NFP, June CPI and EIA natural-gas storage generated the quarter's first major macro and energy repricing events.

August

117 Pips / ticks + 17 XAU/USD points

July payrolls unexpectedly contracted, with substantial downward revisions reinforcing the deterioration in labour-market momentum.

September

487 Pips / ticks + 91 XAU/USD points

Seven releases across employment, inflation, energy, growth and agriculture made September the most active month of the quarter.

Q3 2026 Release-Window Intelligence Matrix

Date Release Key Information HAAWKS Measurement
2 Jul U.S. Employment Situation NFP +57K vs. roughly +110K expected; unemployment 4.2%; April and May revised down by a combined 74K. 118 pips/ticks
XAU/USD 43 points
14 Jul U.S. CPI Headline −0.4% MoM and core 0.0%, both below consensus; energy −5.7% and gasoline −9.7%. 114 pips/ticks
XAU/USD 34 points
16 Jul EIA Natural Gas Storage +41 Bcf injection vs. +43 Bcf expected; total inventories 181 Bcf above the five-year average. Natural Gas −39 ticks
7 Aug U.S. Employment Situation NFP −23K vs. +80K expected; May and June revised down by a combined 103K; wage growth slowed. 117 pips/ticks
XAU/USD 17 points
4 Sep U.S. Employment Situation NFP +162K vs. +56K expected; unemployment 4.1%; June and July revised up by 55K. US500 −68 ticks
XAU/USD −57 points
10 Sep EIA Weekly Petroleum Status Report Crude −0.391M vs. roughly −1.55M expected, alongside unexpected gasoline and distillate builds. WTI −30 ticks
11 Sep U.S. CPI Headline +0.4% MoM matched consensus; core +0.3% exceeded the +0.2% expectation. US500 −48 ticks
XAU/USD −19 points
11 Sep USDA WASDE Corn yield cut to 178.5 bpa, production to 15.800B bu and projected ending stocks to 1.567B bu. ZC +52
ZW +32
ZS +28 ticks
30 Sep BEA PCE / GDP Headline PCE +0.3% MoM vs. +0.4% expected while Q2 GDP was revised from 1.5% to 2.2%. 93 pips/ticks
XAU/USD +15 points
30 Sep EIA Weekly Petroleum Status Report Crude +0.922M vs. an expected draw, but gasoline and distillates posted substantially larger-than-expected draws. WTI +24 ticks
30 Sep USDA Grain Stocks Corn 2.095B bu vs. 1.924B survey average; soybeans 315M vs. 323M; wheat 1.846B vs. 1.849B. ZC −56
ZW −32
ZS +24 ticks

Macro Intelligence: Policy Expectations Reversed Repeatedly

The macro releases in Q3 were notable for the speed with which the perceived U.S. policy outlook changed from one publication to the next.

The quarter began with a weaker June Employment Situation. Payrolls increased by only 57,000, below the approximately 110,000 expected, while April and May payrolls were revised down by a combined 74,000.

The July 14 inflation report reinforced that softer interpretation. Headline CPI declined 0.4% in June while core CPI was unchanged. HAAWKS measured a weaker dollar alongside gains in equities and gold.

The July labour report, released August 7, then delivered an even larger employment shock. Payrolls fell 23,000 against expectations for an 80,000 increase, while the prior two months were revised lower by another 103,000.

By early September, however, the signal reversed sharply. August payrolls increased 162,000 against a consensus estimate of only 56,000, and the prior two months were revised upward by 55,000.

One week later, August CPI introduced another comparatively restrictive signal: headline inflation matched expectations, but core CPI increased 0.3% month over month against a 0.2% forecast.

HAAWKS view: Q3 demonstrated why a static macro regime label is insufficient. Employment, inflation and revisions repeatedly changed the marginal policy signal, and markets repriced that information within the release window rather than waiting for a stable quarterly narrative.

September 30: One Timestamp, Competing Macro Signals

The BEA releases on September 30 provided one of the clearest examples of conflicting information arriving simultaneously.

August headline PCE inflation increased 0.3% month over month, below the cited Reuters expectation of 0.4%. The annual rate was 3.4%, below approximately 3.7% expected, while core PCE increased 0.2% month over month and 3.0% year over year.

At the same 8:30 a.m. ET timestamp, second-quarter real GDP was revised from 1.5% to 2.2%. Real final sales to private domestic purchasers increased 4.6%, while real GDI was revised to 2.6%.

The first market response nevertheless leaned toward the softer inflation signal. HAAWKS measured EUR/USD higher, USD/JPY lower, US500 higher and gold higher.

The analytical lesson is important: a release can be simultaneously less inflationary and more growth-positive. Field-level weighting, release vintage and cross-asset confirmation matter more than a simplistic directional label.

Energy Intelligence: The Headline Was Rarely Enough

The quarter's three energy events provide a useful comparison because the first-order headline did not always explain the immediate market response.

Natural Gas — 16 July

EIA reported a 41 Bcf injection, slightly below the 43 Bcf consensus and below the five-year average build.

Yet natural gas fell 39 ticks in 11 seconds. Total working gas stood at 3,024 Bcf, still 181 Bcf or 6.4% above the five-year average.

The market therefore placed more weight on the broader inventory and supply environment than on the modest weekly surprise.

Petroleum — 10 September

Commercial crude stocks fell only 391,000 barrels against expectations for a much larger draw. Gasoline and distillate inventories also unexpectedly increased.

HAAWKS measured WTI approximately 30 ticks lower.

This release also highlighted publication architecture: core market-sensitive EIA statistics became public before the later complete formatted report.

Petroleum — 30 September

The later petroleum release produced almost the mirror image. Commercial crude unexpectedly increased by 922,000 barrels, but gasoline declined by approximately 1.7 million barrels and distillates by approximately 2.3 million.

HAAWKS measured WTI 24 ticks higher, consistent with the market placing substantial weight on the tighter refined-product balance rather than on the crude headline alone.

Agricultural Intelligence: Revisions, Consensus and Physical Stocks

September added two distinct USDA information events to the quarter: WASDE on September 11 and Grain Stocks on September 30.

September WASDE

USDA reduced the 2026/27 corn yield from 180.7 to 178.5 bushels per acre, lowered production to 15.800 billion bushels and reduced projected ending stocks to 1.567 billion bushels.

Soybean production increased to 4.535 billion bushels, but stronger exports reduced projected ending stocks to 310 million bushels. Wheat's U.S. balance was comparatively stable.

HAAWKS measured ZC +52 ticks, ZW +32 ticks and ZS +28 ticks.

One of the central analytical distinctions was that a large month-to-month USDA revision is not necessarily the same thing as a large surprise relative to pre-release expectations.

September Grain Stocks

The quarter ended with updated physical inventory estimates. September 1 corn stocks totaled 2.095 billion bushels, approximately 171 million above the cited Dow Jones survey average and above the top of its estimate range.

Soybean stocks of 315 million bushels were below the cited 323-million-bushel average, while all-wheat stocks of 1.846 billion bushels were close to the 1.849-billion consensus.

HAAWKS measured ZC −56 ticks, ZW −32 ticks and ZS +24 ticks.

Where Q3 Release-Window Movement Was Concentrated

Data Complex Releases Cumulative Pips / Ticks XAU/USD Points
U.S. Macro NFP ×3, CPI ×2, PCE/GDP 558 185
Energy Natural Gas Storage + WPSR ×2 93 —
Agriculture WASDE + Grain Stocks 224 —
Q3 Total 11 releases 875 185

Six Market-Intelligence Lessons from Q3

Consensus Defines the Surprise

Absolute numbers are not sufficient. The immediate information content depends on the difference between an official value and what market participants expected before publication.

Revisions Can Change the Signal

Payroll revisions of −74K, −103K and later +55K demonstrated how historical revisions can materially reinforce or offset a current-month headline.

Supporting Fields Matter

Core CPI, labour participation, refined-product inventories, indicated grain disappearance and private domestic final sales all provided information beyond the headline field.

Conflicting Signals Are Normal

September 30 combined softer PCE inflation with stronger GDP, while the petroleum release combined a crude build with large product draws. Robust interpretation must rank competing signals.

Publication Timing Matters

The September 10 EIA event demonstrated that the relevant market timestamp is the first public dissemination of high-value official data, not necessarily the later publication of a complete report.

Release Vintage Must Be Preserved

BEA annual revisions and recurring payroll revisions reinforce the importance of retaining the exact data set available to the market at each historical publication timestamp.

Implications for Real-Time Market Infrastructure

The quarter's releases originated from different agencies and covered very different statistical frameworks, yet the technical requirements for systematic interpretation were remarkably consistent.

Requirement Function Q3 Example
Low-Latency Official Data Capture fields as they become publicly available. September 10 EIA petroleum data
Consensus Integration Quantify the deviation between actual values and expectations. NFP, CPI, petroleum inventories and Grain Stocks
Multi-Field Parsing Process headline and supporting statistics concurrently. Core CPI, payroll revisions, product inventories and PCE/GDP
Release-Vintage Storage Preserve the data exactly as available in real time. Payroll revisions and BEA annual benchmarking
Cross-Asset Mapping Relate individual fields to the markets most sensitive to them. FX, US500, gold, WTI, natural gas and grain futures
Precise Event Scheduling Maintain state across several high-value publication windows. September 30 at 8:30, 10:30 and 12:00 ET

Cumulative Indicative Potential vs. Executable Performance

The HAAWKS quarterly figures aggregate absolute market movement across selected release windows to provide a consistent indicator of how much repricing occurred around scheduled information events.

Under that convention, Q3 produced 875 pips/ticks and 185 XAU/USD points.

These values should not be treated as a standardized portfolio return. A pip in an FX pair, a tick in an equity index or commodity future and a point in spot gold are different units with different economic values.

HAAWKS methodology: release-window measurements describe historical price movement around scheduled official publications. They measure market sensitivity to newly available information; they do not represent guaranteed or necessarily achievable trading performance.

Q3 2026 HAAWKS Research Archive

For detailed analysis, click on any release below to view the full HAAWKS research note.

2 July 2026 U.S. Employment Situation — June NFP

118 pips/ticks and 43 XAU/USD points as softer payroll growth, stable wages and negative revisions shifted the macro signal.

14 July 2026 U.S. Consumer Price Index — June CPI

114 pips/ticks and 34 XAU/USD points following a broad downside inflation surprise.

16 July 2026 EIA Weekly Natural Gas Storage Report

Natural gas fell 39 ticks in 11 seconds despite an injection slightly below consensus.

7 August 2026 U.S. Employment Situation — July NFP

117 pips/ticks and 17 XAU/USD points after payrolls unexpectedly contracted and prior months were revised sharply lower.

4 September 2026 U.S. Employment Situation — August NFP

US500 −68 ticks and XAU/USD −57 points after payroll growth substantially exceeded expectations.

10 September 2026 EIA Weekly Petroleum Status Report

WTI −30 ticks after a smaller-than-expected crude draw and unexpected refined-product builds.

11 September 2026 U.S. Consumer Price Index — August CPI

US500 −48 ticks and XAU/USD −19 points after monthly core CPI exceeded consensus.

11 September 2026 USDA September WASDE

ZC +52, ZW +32 and ZS +28 ticks as markets processed updated agricultural supply-and-demand balances.

30 September 2026 BEA Personal Income & Outlays and GDP

93 pips/ticks and 15 XAU/USD points as softer inflation competed with a materially stronger GDP revision.

30 September 2026 EIA Weekly Petroleum Status Report

WTI +24 ticks as large product draws offset an unexpected commercial crude build.

30 September 2026 USDA Grain Stocks

ZC −56, ZW −32 and ZS +24 ticks following publication of the September 1 inventory estimates.

HAAWKS Market Intelligence Conclusion

Q3 2026 produced eleven distinct examples of how newly published official information can generate rapid repricing across financial and commodity markets.

HAAWKS measured a cumulative 875 pips/ticks of indicative release-window potential and a further 185 XAU/USD points across the selected events.

Macro releases accounted for the largest share of measured activity, but the energy and agricultural events reinforced the same broader analytical principle: the headline figure alone is rarely sufficient.

Expectations, revisions, supporting fields, physical balances and publication timing repeatedly changed the information content of the releases.

The quarter also demonstrated why release-vintage preservation matters. A historical database containing the latest revised value is not necessarily the same information set that professional market participants received at the original publication timestamp.

For real-time market infrastructure, the central requirement remains consistent: deliver official information quickly, structure it at the field level and preserve enough context to evaluate the new data against expectations while markets are repricing.

Real-Time Data. Structured Intelligence. Professional Markets.

Real-Time Structured Data for Professional Markets

HAAWKS G4A provides low-latency, structured macroeconomic and commodity data covering the United States, Canada and Europe.

The feed supports systematic strategies, professional trading desks and latency-sensitive applications requiring field-level economic and commodity data as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Primary Data Sources

Methodology note: The quarterly 875 pips/ticks figure is a cumulative indicative measure based on the HAAWKS convention of summing absolute measured release-window movements across selected FX, equity-index and commodity instruments. XAU/USD movements are reported separately and totaled 185 points during the quarter. Pips, ticks, index points and gold points are instrument-specific units. They do not represent equivalent economic values and should not be interpreted as a standardized portfolio return.

Data note: Official figures are sourced from the relevant government agencies. Pre-release expectations referenced in the underlying research notes are sourced from identified surveys and data providers and can vary between sources. Historical release vintages can subsequently be revised.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. Historical release-window price movement does not represent guaranteed or necessarily achievable trading performance. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for speed-sensitive market participants. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data through API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for qualified financial institutions.
Comment

HAAWKS Market Intelligence Briefing — September 2026: Real-Time Repricing Across Macro, Energy and Agricultural Markets

Comment

HAAWKS Market Intelligence Briefing — September 2026: Real-Time Repricing Across Macro, Energy and Agricultural Markets

According to our analysis, the September 2026 events generated a combined potential market movement of 487 pips/ticks and 91 XAU/USD points. For comparison, the corresponding potential performance measured across 2025 was 1,828 pips/ticks.

September 2026

Cumulative Potential — Indicative Performance for September 2026. Please see the individual releases below for detailed analysis.

For detailed analysis, click on any release below to view the full HAAWKS research note.


HAAWKS Research

September 2026 Real-Time Market Intelligence Briefing: Macro, Energy and Agricultural Markets

A review of seven scheduled U.S. data events and the immediate repricing observed across equities, foreign exchange, precious metals, crude oil and agricultural futures.

September 2026 • 7 Scheduled Releases • 4 Release Dates • Real-Time Market Intelligence Briefing

September 2026 provided a concentrated series of scheduled U.S. information events across macroeconomics, energy and agriculture, creating measurable short-horizon repricing across multiple asset classes.

The month included the U.S. Employment Situation, Consumer Price Index, Personal Income and Outlays, GDP, two Weekly Petroleum Status Reports, USDA WASDE and USDA Grain Stocks.

Across these seven releases, HAAWKS measured 462 instrument-specific ticks across equity-index, energy and agricultural markets, 25 FX pips across EUR/USD and USD/JPY, and 91 XAU/USD points.

The purpose of this briefing is not to aggregate those observations into a trading-return figure. Instead, it documents how new official information was incorporated across markets and highlights recurring themes in release structure, expectations, revisions and cross-asset transmission.

Measurement framework: HAAWKS release-window figures represent historical market movement observed around scheduled official publications. Tick, pip and point conventions differ across instruments and are therefore reported separately rather than combined into a standardized performance metric.

September Market Intelligence at a Glance

Scheduled Releases 7 Macro, energy and agriculture
Futures / Index Ticks 462 Absolute measured release-window movement
FX Pips 25 EUR/USD and USD/JPY
XAU/USD Points 91 Across three macro releases

September 2026 Release-Window Intelligence Summary

Date Official Release Measured Market Response Key Information Signal
4 Sep U.S. Employment Situation US500 −68 ticks
XAU/USD −57 points
Payroll growth substantially exceeded expectations while prior months were revised higher.
10 Sep EIA Weekly Petroleum Status Report WTI −30 ticks Crude stocks declined less than expected while gasoline and distillate inventories increased.
11 Sep U.S. Consumer Price Index US500 −48 ticks
XAU/USD −19 points
Headline CPI matched expectations while monthly core CPI exceeded consensus.
11 Sep USDA WASDE ZC +52 ticks
ZW +32 ticks
ZS +28 ticks
Updated U.S. and global agricultural supply-and-demand balances generated repricing across the grain complex.
30 Sep BEA Personal Income & Outlays / GDP EUR/USD +10 pips
USD/JPY −15 pips
US500 +68 ticks
XAU/USD +15 points
Softer PCE inflation arrived alongside a substantial upward revision to second-quarter GDP.
30 Sep EIA Weekly Petroleum Status Report WTI +24 ticks An unexpected crude build was offset by substantially larger gasoline and distillate draws.
30 Sep USDA Grain Stocks ZC −56 ticks
ZW −32 ticks
ZS +24 ticks
Corn inventories exceeded the cited survey range, soybean stocks were below the survey average and wheat stocks were close to expectations.

Concentration of Market Repricing by Release Date

Date Scheduled Events Measured Ticks FX Pips XAU/USD Points
4 September Employment Situation 68 — 57
10 September EIA WPSR 30 — —
11 September CPI + WASDE 160 — 19
30 September BEA PCE/GDP + EIA WPSR + USDA Grain Stocks 204 25 15
September Total 7 releases 462 25 91

4 September — Employment Data Reprice U.S. Macro Expectations

The August Employment Situation opened September's major scheduled U.S. macro releases with a substantial upside payroll surprise.

Nonfarm payroll employment increased by 162,000, compared with a cited consensus expectation of approximately 56,000.

The unemployment rate remained at 4.1%, labor-force participation increased to 61.6%, and June and July payroll estimates were revised upward by a combined 55,000 jobs.

HAAWKS measured US500 68 ticks lower and XAU/USD 57 points lower during the immediate release window.

Market-intelligence takeaway: the information set extended well beyond the headline payroll number. Employment growth, historical revisions, participation and wages all entered the market at the same timestamp and contributed to the initial repricing of U.S. rate expectations.

10 September — Petroleum Data Highlight Release Sequencing

The September 10 petroleum release illustrated an important feature of professional market-data infrastructure: the relevant event begins when market-sensitive official information first becomes publicly available.

Commercial crude inventories declined by approximately 391,000 barrels, materially less than the roughly 1.55 million-barrel draw cited in the pre-release survey.

Gasoline and distillate inventories simultaneously increased, strengthening the negative interpretation of the broader petroleum balance.

HAAWKS measured approximately 30 ticks of downside movement in WTI following publication of the early EIA data.

The episode demonstrates why release architecture matters: the first structured official data can become relevant before the later publication of a complete formatted report.

11 September — Inflation and Agricultural Supply Reprice Different Markets

Two independent information events occurred on September 11: U.S. CPI at 8:30 a.m. ET and USDA WASDE at noon.

Consumer Price Index

Headline CPI increased 0.4% month over month, matching the cited consensus.

Core CPI increased 0.3% versus a 0.2% expectation, making the underlying inflation measure the more significant release-window surprise.

HAAWKS measured US500 48 ticks lower and XAU/USD 19 points lower.

USDA WASDE

Four hours later, USDA updated its domestic and global agricultural supply-and-demand projections.

Corn production and projected ending stocks were reduced from August levels, while the soybean balance combined higher production with stronger exports and lower projected carryout.

HAAWKS measured ZC +52 ticks, ZW +32 ticks and ZS +28 ticks, representing 112 instrument-specific ticks of immediate movement across the three contracts.

30 September — Three Information Events Across Three Market Complexes

September 30 was the most concentrated data session of the month.

BEA macroeconomic data were published at 8:30 a.m. ET, EIA petroleum statistics at 10:30 a.m. ET, and USDA Grain Stocks at noon.

Across those three publication windows, HAAWKS measured 204 ticks, 25 FX pips and 15 XAU/USD points.

8:30 a.m. ET — PCE Inflation and GDP

August headline PCE inflation increased 0.3% month over month, below the cited 0.4% expectation.

At the same timestamp, second-quarter real GDP was revised materially higher from 1.5% to 2.2%.

The first cross-asset response nevertheless placed greater weight on the softer inflation signal.

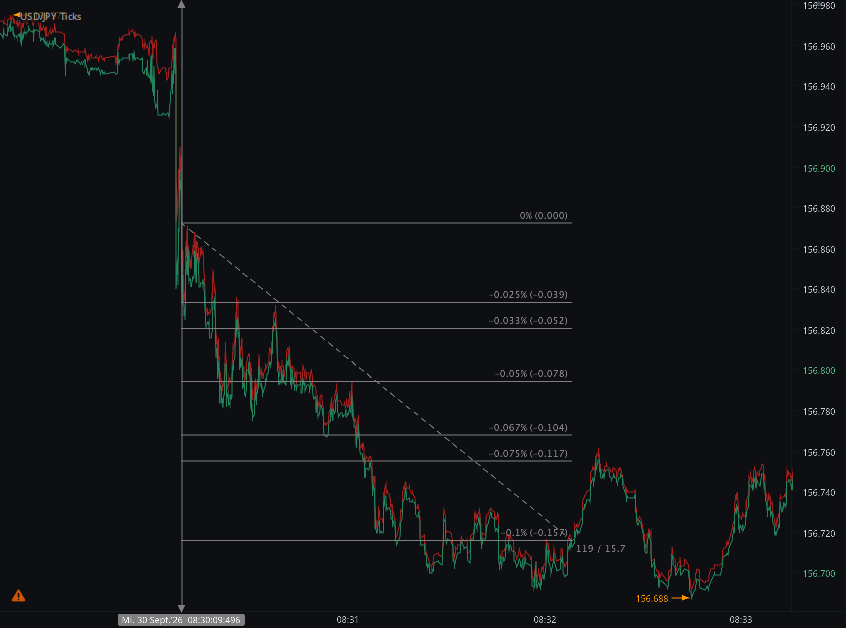
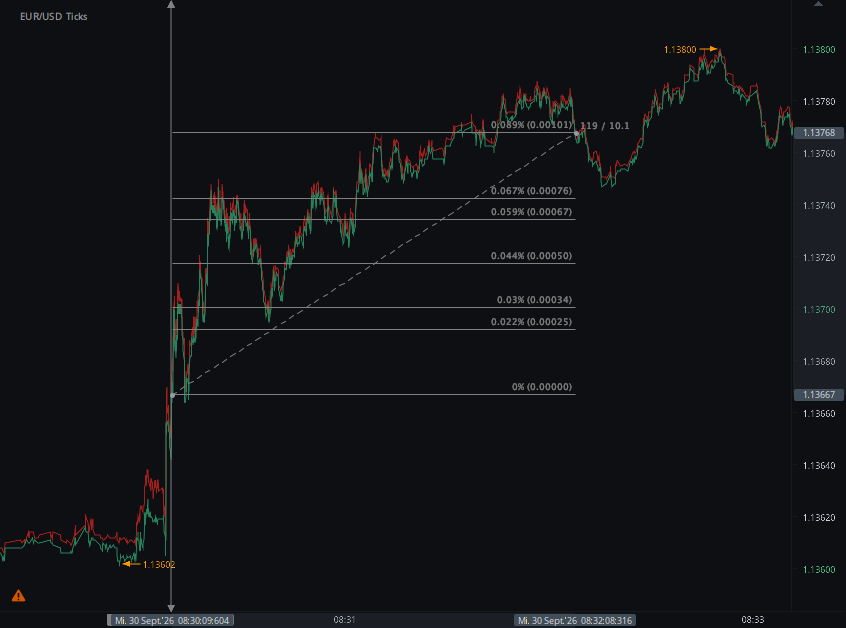
HAAWKS measured EUR/USD +10 pips, USD/JPY −15 pips, US500 +68 ticks and XAU/USD +15 points.

10:30 a.m. ET — EIA Petroleum Data

Commercial crude inventories increased by approximately 922,000 barrels, contrary to expectations for a draw.

Gasoline inventories fell by approximately 1.7 million barrels, while distillate stocks declined by approximately 2.3 million barrels.

HAAWKS measured WTI 24 ticks higher, illustrating how the petroleum balance can generate a different signal from the crude headline in isolation.

12:00 p.m. ET — USDA Grain Stocks

USDA reported September 1 corn stocks of 2.095 billion bushels, approximately 171 million bushels above the cited Dow Jones survey average and above the top of the cited estimate range.

Soybean inventories of 315 million bushels were below the cited survey average, while all-wheat stocks of 1.846 billion bushels were close to expectations.

HAAWKS measured ZC −56 ticks, ZW −32 ticks and ZS +24 ticks, representing another 112 instrument-specific ticks across the three agricultural contracts.

Recurring Market-Intelligence Themes in September

Expectations Define the Surprise

The sign of an economic or inventory change is not sufficient on its own. What matters for immediate repricing is often the difference between the published value and the distribution of expectations already embedded in the market.

The Headline Is Only One Field

Core CPI, payroll revisions, refined-product inventories and underlying PCE and GDP components all demonstrated that the highest-information field may not be the headline statistic.

Conflicting Signals Can Arrive Together

September 30 combined softer inflation with stronger GDP. The EIA petroleum report combined a crude build with substantial refined-product draws. Structured interpretation is required when fields point in different directions.

Release Architecture Matters

The September 10 petroleum event demonstrated that the first publicly available official data can precede a later complete formatted report. For latency-sensitive infrastructure, first dissemination is the relevant timestamp.

Release Sequencing Matters

September 30 contained three separate scheduled information windows within three and a half hours. Systems need precise event schedules and state management as one publication follows another.

Cross-Asset Repricing Adds Context

FX, equities, precious metals, crude oil and agricultural futures provide different transmission channels for the same underlying information. Observing several markets can provide a more complete picture of how the information is being interpreted.

Requirements for Real-Time Event-Driven Market Infrastructure

The seven September releases originated from different agencies and covered very different economic and commodity frameworks, yet the underlying data requirements were broadly consistent.

Requirement Function September Example
Low-Latency Official Data Capture market-sensitive fields as soon as they become publicly available. September 10 EIA petroleum data
Consensus Integration Measure the published figure against expectations already reflected in market pricing. NFP, CPI, petroleum inventories and Grain Stocks
Multi-Field Parsing Process headline and supporting fields concurrently. Payroll revisions, core CPI, petroleum products, PCE and GDP
Release Vintage Preservation Retain the data exactly as it was available at each publication timestamp. BEA annual updates and GDP revisions
Asset-Specific Mapping Map individual data fields to the markets most sensitive to the information. FX, equities, gold, crude oil and agricultural futures
Precise Event Timing Maintain accurate schedules where multiple official releases occur on the same day. September 30 at 8:30, 10:30 and 12:00 ET

Release-Window Measurement and Market Intelligence

HAAWKS release-window analysis is designed to document how markets responded immediately around identifiable official data publications.

This provides a consistent framework for studying market sensitivity to new information without conflating the initial repricing with the direction of the entire trading session.

The measurements are not intended to represent executable returns or realized P&L.

Actual execution depends on factors including data latency, processing latency, market depth, spreads, available liquidity, slippage, order type and execution venue.

HAAWKS methodology: the objective is to measure the market's immediate response to newly published official information and to analyze the structure of the data that entered the market at that timestamp.

September 2026 HAAWKS Research Archive

4 September 2026 August 2026 U.S. Employment Situation

US500 −68 ticks and XAU/USD −57 points following the stronger payroll result and upward revisions.

10 September 2026 EIA Weekly Petroleum Status Report

WTI −30 ticks after a smaller-than-expected crude draw and unexpected gasoline and distillate builds.

11 September 2026 August 2026 U.S. Consumer Price Index

US500 −48 ticks and XAU/USD −19 points as monthly core CPI exceeded consensus.

11 September 2026 September 2026 USDA WASDE

ZC +52, ZW +32 and ZS +28 ticks as markets incorporated updated agricultural supply-and-demand balances.

30 September 2026 BEA Personal Income & Outlays and GDP

EUR/USD +10 pips, USD/JPY −15 pips, US500 +68 ticks and XAU/USD +15 points after softer inflation and stronger GDP.

30 September 2026 EIA Weekly Petroleum Status Report

WTI +24 ticks as substantial gasoline and distillate draws offset an unexpected commercial crude inventory build.

30 September 2026 USDA Grain Stocks

ZC −56, ZW −32 and ZS +24 ticks following publication of the September 1 U.S. inventory estimates.

HAAWKS Market Intelligence Conclusion

September 2026 provided seven distinct examples of how scheduled official information can generate rapid repricing across financial and commodity markets.

HAAWKS measured 462 instrument-specific ticks, 25 FX pips and 91 XAU/USD points across the selected release windows.

The underlying events covered employment, inflation, household spending, GDP, petroleum inventories, agricultural supply-and-demand balances and physical grain stocks.

Despite the different data sets, several common market-intelligence principles emerged repeatedly: expectations matter, supporting fields matter, revisions matter, publication timing matters and the first repricing can differ materially from the subsequent trading session.

September 30 was particularly instructive. Three scheduled releases across macroeconomic, petroleum and agricultural markets occurred within three and a half hours, producing 204 ticks, 25 FX pips and 15 gold points of measured release-window movement.

For professional market infrastructure, the central requirement is consistent: official data is most useful when it is delivered quickly, structured at the field level and contextualized against expectations, revisions and the exact publication timestamp.

Real-Time Data. Structured Intelligence. Professional Markets.

Real-Time Structured Data for Professional Markets

HAAWKS G4A provides low-latency machine-readable macroeconomic and commodity data covering the United States, Canada and Europe.

Data is delivered in structured machine-readable format for systematic strategies, professional trading desks and latency-sensitive applications that require field-level information as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

September 2026 Research Sources

Methodology note: Monthly totals represent sums of absolute historical price movements measured around the specified scheduled releases. Positive and negative movements are therefore both included by magnitude. Tick, pip and point conventions are instrument-specific. The 462 ticks, 25 FX pips and 91 XAU/USD points presented in this briefing are intentionally reported as separate units and should not be combined or interpreted as a standardized rate of return.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. Historical release-window movement does not represent guaranteed or necessarily achievable trading profit. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

USDA Grain Stocks Trigger Sharp Repricing Across Corn, Wheat and Soybeans

Comment

USDA Grain Stocks Trigger Sharp Repricing Across Corn, Wheat and Soybeans

According to our analysis corn (ZC), wheat (ZW) and soybeans (ZS) futures prices moved around 56 / 32 / 24 ticks (total 112) on USDA Grain Stocks data on 30 September 2026.


HAAWKS Research

USDA Grain Stocks Trigger Sharp Repricing Across Corn, Wheat and Soybeans

September 1 U.S. grain inventories delivered materially different supply signals across corn, soybeans and wheat, with the largest deviation from expectations concentrated in corn.

September 30, 2026 • Release time: 12:00 p.m. ET • USDA NASS Grain Stocks

The September 2026 USDA Grain Stocks report produced a differentiated response across CBOT corn, wheat and soybean futures as market participants incorporated updated estimates of physical inventories across the three major U.S. grain markets.

USDA reported September 1 corn inventories of 2.095 billion bushels, substantially above pre-release expectations and 35% above the corresponding level one year earlier.

Soybean inventories totaled 315 million bushels, below the cited market average and approximately 3% below September 2025.

All-wheat inventories stood at 1.846 billion bushels, close to the cited average expectation while remaining approximately 14% below the prior-year level.

HAAWKS release-window measurement: CBOT corn futures ZC fell 56 ticks, wheat futures ZW fell 32 ticks, while soybean futures ZS rose 24 ticks following publication of the USDA Grain Stocks data.

Immediate Cross-Grain Market Reaction

Corn — ZC −56 Ticks HAAWKS release-window measurement
Wheat — ZW −32 Ticks HAAWKS release-window measurement
Soybeans — ZS +24 Ticks HAAWKS release-window measurement

September 1 Stocks vs. Market Expectations

The information content of a scheduled agricultural release depends not only on the absolute inventory level but also on the difference between the published figure and the distribution of expectations immediately before publication.

The pre-release estimates below are from the Dow Jones / Wall Street Journal analyst survey, as reproduced by DTN and Price Futures Group ahead of and following the September 30 release.

Commodity Survey Average Survey Range USDA Actual Difference vs. Average
Corn 1.924B bu 1.860–2.005B 2.095B bu +171M bu
Soybeans 323M bu 305–335M 315M bu −8M bu
All Wheat 1.849B bu 1.790–1.955B 1.846B bu −3M bu

Estimate source: Dow Jones / Wall Street Journal survey of analysts, reproduced by DTN and Price Futures Group. Survey estimates can differ across data providers and should be identified by source when used in release analysis.

HAAWKS view: the three crops delivered materially different inventory profiles. Corn produced the largest deviation from the cited pre-release distribution, soybean inventories were below the survey average, while wheat stocks were close to the consensus level.

Corn: Stocks Exceed the Entire Survey Range

September 1 U.S. corn inventories totaled 2.095 billion bushels.

That was approximately 171 million bushels above the Dow Jones survey average of 1.924 billion bushels.

More significantly, USDA's estimate exceeded the upper end of the cited 1.860 to 2.005 billion bushel survey range. The published figure was therefore above every estimate contained in that survey.

Total Corn Stocks 2.095B Bushels on September 1
Year-on-Year +35% Versus September 2025
Difference vs. Average +171M Bushels above Dow Jones average
Corn Inventory Detail Sep. 1, 2026 Sep. 1, 2025 Year-on-Year Change
On-Farm Stocks 787.3M bu 643.2M bu +22%
Off-Farm Stocks 1.308B bu 908.1M bu +44%
Total Stocks 2.095B bu 1.551B bu +35%

The increase was particularly pronounced in off-farm storage. Off-farm corn stocks reached approximately 1.308 billion bushels, 44% above the corresponding level one year earlier.

June through August indicated disappearance was approximately 3.20 billion bushels, compared with about 3.09 billion bushels during the same period in 2025.

Usage therefore increased year over year, but not sufficiently to prevent a substantially larger September 1 inventory position.

Soybeans: Stocks Come In Below Expectations

USDA estimated September 1 soybean inventories at 315 million bushels.

That was approximately 8 million bushels below the Dow Jones survey average of 323 million bushels and within the cited 305 to 335 million bushel estimate range.

Total soybean inventories were also approximately 3% below the year-earlier level.

Total Soybean Stocks 315M Bushels on September 1
Year-on-Year −3% Versus September 2025
Difference vs. Average −8M Bushels below Dow Jones average
Soybean Inventory Detail Sep. 1, 2026 Sep. 1, 2025 Year-on-Year Change
On-Farm Stocks 90.4M bu 91.5M bu −1%
Off-Farm Stocks 224.7M bu 233.3M bu −4%
Total Stocks 315.1M bu 324.8M bu −3%

June through August indicated soybean disappearance totaled approximately 744 million bushels, compared with roughly 683 million bushels during the comparable period one year earlier.

Wheat Stocks Decline from the Prior Year

USDA reported September 1 all-wheat inventories of 1.846 billion bushels.

The figure was close to the Dow Jones survey average of 1.849 billion bushels and remained within the cited 1.790 to 1.955 billion bushel range.

Relative to September 1, 2025, total wheat inventories were approximately 14% lower.

Total Wheat Stocks 1.846B Bushels on September 1
Year-on-Year −14% Versus September 2025
Difference vs. Average −3M Bushels vs. Dow Jones average
Wheat Inventory Detail Sep. 1, 2026 Sep. 1, 2025 Year-on-Year Change
On-Farm Stocks 546.5M bu 692.2M bu −21%
Off-Farm Stocks 1.299B bu 1.442B bu −10%
Total All-Wheat Stocks 1.846B bu 2.134B bu −14%

June through August indicated wheat disappearance totaled approximately 608 million bushels, compared with approximately 710 million bushels during the same period one year earlier.

Three Crops, Different Inventory Profiles

Corn Inventories

September 1 stocks reached 2.095 billion bushels, substantially above the Dow Jones survey average and above the upper end of the cited estimate range.

Soybean Inventories

Soybean stocks totaled 315 million bushels, below the cited pre-release average and approximately 3% below the prior-year inventory level.

Wheat Inventories

All-wheat stocks totaled 1.846 billion bushels, close to the pre-release average while substantially below the corresponding level one year earlier.

Cross-Market Repricing

HAAWKS recorded different immediate price responses across all three CBOT contracts as market participants incorporated the updated physical inventory information.

Storage Location Adds Another Layer of Information

Grain Stocks separates inventories held on farms from stocks held in commercial facilities, mills, elevators and other off-farm locations.

That distinction can matter for professional agricultural-market analysis because physical availability, producer selling behavior and regional basis conditions can differ depending on where inventories are located.

Commodity On-Farm Stocks Off-Farm Stocks Total Stocks
Corn 787.3M bu 1.308B bu 2.095B bu
Soybeans 90.4M bu 224.7M bu 315.1M bu
Wheat 546.5M bu 1.299B bu 1.846B bu

Indicated Disappearance Provides Demand Context

Inventory levels describe the quantity of grain remaining at a particular point in time. Indicated disappearance adds another layer by estimating the quantity that moved out of stocks during the quarter.

Commodity Jun–Aug 2026 Jun–Aug 2025 Direction
Corn 3.20B bu 3.09B bu Higher
Soybeans 744M bu 683M bu Higher
Wheat 608M bu 710M bu Lower

These fields provide a broader view of physical-market activity than the headline stock totals alone and can be useful when reconciling supply-and-demand balances after publication.

Why Grain Stocks Requires Multi-Field Processing

The publication contains considerably more information than three headline inventory totals.

A structured feed can expose inventory totals, storage location, historical comparisons, indicated disappearance and revisions at the field level, allowing each component to be evaluated independently.

Information Set Relevant Fields Analytical Function
Total Stocks Corn, soybeans and wheat Establishes the point-in-time physical inventory position.
Consensus Comparison Average, high and low estimates Measures the deviation between expectations and the official publication.
Storage Location On-farm and off-farm inventories Provides additional information about physical availability and inventory distribution.
Indicated Disappearance Quarterly implied usage Adds demand-side context to the inventory balance.
Historical Comparison Current and year-earlier stocks Places the latest estimate within a broader supply context.

Implications for Event-Driven Commodity Strategies

Consensus Is Part of the Data Set

The official inventory figure alone does not quantify the amount of new information entering the market. A professional event-driven framework also needs the relevant consensus source, estimate range and timestamp.

Consensus Sources Should Be Identified Explicitly

Estimates can differ across surveys and data vendors. This analysis therefore identifies the cited numbers as the Dow Jones / Wall Street Journal analyst survey reproduced by DTN and Price Futures Group rather than presenting them as a universal market consensus.

Each Commodity Requires Independent Parsing

Corn, wheat and soybeans can deliver different statistical signals in the same publication. Systems therefore benefit from processing each commodity and each inventory field separately rather than generating one aggregate grain classification.

Storage Location Matters

On-farm and off-farm inventory changes can contain information about physical availability, producer behavior and commercial supply.

Release Vintage Should Be Preserved

Quantitative research benefits from preserving the exact numbers available at publication rather than relying solely on databases that may contain subsequent revisions.

Tick Movement Is Contract-Specific

The measured ZC, ZW and ZS movements describe contract-specific price changes around publication. Tick values are instrument-specific and should not be treated as standardized financial returns.

Immediate Market Response

HAAWKS measured ZC 56 ticks lower, ZW 32 ticks lower and ZS 24 ticks higher during the immediate response to the USDA Grain Stocks publication.

These measurements isolate the initial repricing around the scheduled data release rather than the direction of each market over the entire trading session.

Subsequent price action can incorporate harvest progress, export demand, weather, positioning, inter-commodity spreads, liquidity and broader market developments.

HAAWKS view: the September Grain Stocks release demonstrates why agricultural market data is best treated as a structured information set rather than a single headline number. Inventory totals, expectations, storage location and implied usage all enter the market at the same publication timestamp.

HAAWKS Conclusion

The September 30 USDA Grain Stocks report produced a differentiated repricing across CBOT agricultural futures.

Corn inventories totaled 2.095 billion bushels, approximately 171 million bushels above the Dow Jones survey average and above the highest estimate in the cited survey range.

Soybean inventories stood at 315 million bushels, approximately 8 million bushels below the cited survey average and around 3% below the year-earlier stock level.

All-wheat inventories totaled 1.846 billion bushels, close to the cited survey average and approximately 14% below September 2025.

HAAWKS measured immediate release-window movements of ZC −56 ticks, ZW −32 ticks and ZS +24 ticks.

For professional market infrastructure, the publication demonstrates the value of processing USDA statistics as structured, machine-readable information. Official values, market expectations, estimate ranges, historical comparisons, storage location and indicated disappearance can all be evaluated as the market incorporates newly published data.

Low-Latency Data. Structured Intelligence. Professional Execution.

Machine-Readable Data for Professional Markets

HAAWKS G4A provides low-latency, structured macroeconomic and commodity data covering the United States, Canada and Europe.

The feed supports systematic strategies, professional trading desks and latency-sensitive applications requiring field-level economic and commodity data as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. USDA NASS — Grain Stocks, September 30, 2026
    Official source for September 1 corn, soybean and wheat inventories, on-farm and off-farm stocks, indicated disappearance and other Grain Stocks statistics.
  2. DTN — Pre-Report Grain Stocks Estimates, September 28, 2026
    Source for the Dow Jones survey averages and ranges used in the pre-release comparison: corn 1.924B bushels, soybeans 323M bushels and wheat 1.849B bushels.
  3. DTN — USDA Quarterly Grain Stocks, September 30, 2026
    Post-release publication reproducing the survey averages, ranges and official USDA Grain Stocks results.
  4. Price Futures Group — Grains Report, September 30, 2026
    Additional reproduction of the Dow Jones / Wall Street Journal analyst survey used for the pre-release stock estimates.
  5. HAAWKS internal tick-level market analysis — September 30, 2026
    Source for the measured immediate release-window movements: ZC −56 ticks, ZW −32 ticks and ZS +24 ticks.
Data note: Pre-release market expectations can vary between surveys and data providers. The estimates used in this article are specifically the Dow Jones / Wall Street Journal analyst survey figures reproduced by DTN and Price Futures Group. USDA figures are official published statistics. HAAWKS market-movement figures are internal release-window measurements.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured release-window movements and do not represent guaranteed or necessarily achievable trading profits. Tick values are contract-specific and are not standardized measures of financial return. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

EIA Petroleum Data: WTI Rises 24 Ticks as Product Draws Offset Crude Build

According to our analysis WTI crude oil moved 24 ticks on DOE Weekly Petroleum Status Report (WPSR) data on 30 September 2026.

WTI crude oil (24 ticks)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

WTI Rises 24 Ticks as Sharp Product Draws Offset an Unexpected Crude Build

The September 30 EIA petroleum release delivered conflicting inventory signals: U.S. commercial crude stocks unexpectedly increased, while gasoline and distillate inventories fell substantially more than expected.

September 30, 2026 • Release time: 10:30 a.m. ET • EIA Weekly Petroleum Data

The September 30 U.S. Energy Information Administration petroleum release presented professional commodity desks with a distinctly two-sided inventory signal.

Commercial crude oil inventories increased by 922,000 barrels during the week ending September 25, directly opposing expectations for an inventory draw.

The refined-product side of the balance sheet, however, told a very different story.

Gasoline inventories declined by approximately 1.7 million barrels, while distillate stocks fell by approximately 2.3 million barrels. Both draws were significantly larger than market expectations.

HAAWKS release-window measurement: WTI crude oil moved approximately 24 ticks higher following the 10:30 a.m. ET release. The initial price response suggests that the market placed substantial weight on tightening refined-product inventories despite the unexpected build in crude.

Inventory Results vs. Market Expectations

Commercial Crude +0.922M Reuters expectation: −0.264M barrels
Gasoline −1.7M Reuters expectation: −0.485M
Distillates −2.3M Reuters expectation: −0.190M
WTI Reaction +24 Ticks HAAWKS release-window measurement
Petroleum Field Market Expectation EIA Actual Surprise Market Read-Through
Commercial Crude Oil −0.264M barrels +0.922M barrels Build vs. expected draw Negative for the crude balance in isolation.
Gasoline −0.485M barrels −1.7M barrels Larger draw Supportive product-market signal and substantially tighter than consensus.
Distillates −0.190M barrels −2.3M barrels Much larger draw Particularly relevant given already constrained diesel and heating-oil inventories.
Cushing, Oklahoma — +0.553M barrels Build A negative counter-signal at the NYMEX WTI delivery hub.

WTI Moves 24 Ticks Higher

HAAWKS tick-level analysis recorded a rapid upward response in WTI immediately following the scheduled petroleum release.

+24 WTI Crude Oil Ticks

Measured during the immediate release window following the September 30, 2026 EIA petroleum data.

The move is notable because the crude inventory headline itself was weaker than expected.

A model reacting only to the commercial crude figure would have seen a 922,000-barrel build against expectations for a 264,000-barrel draw. That represents a swing of almost 1.2 million barrels relative to consensus.

Yet WTI initially moved higher. The broader petroleum balance helps explain why.

The Product Draws Were the More Important Tightness Signal

Gasoline and distillates both delivered materially larger inventory draws than expected.

Gasoline stocks fell from approximately 206.0 million barrels to 204.4 million barrels, a decline of about 1.7 million barrels.

Distillate inventories fell from approximately 107.4 million barrels to 105.2 million barrels, a decline of roughly 2.3 million barrels.

The absolute stock levels are also relevant. Gasoline inventories remained approximately 7% below their five-year seasonal average, while distillate inventories were approximately 14% below the five-year average.

HAAWKS view: the crude build weakened the upstream inventory signal, but the significantly larger-than-expected gasoline and distillate draws reinforced an already tight refined-product market. For WTI pricing, the complete petroleum balance carried more information than the crude headline alone.

Total Commercial Petroleum Inventories Fell 7 Million Barrels

Another important detail is that aggregate commercial petroleum stocks declined despite the rise in crude inventories.

EIA data showed total petroleum stocks excluding the Strategic Petroleum Reserve falling from approximately 1.2514 billion barrels to 1.2443 billion barrels.

That represents a weekly decline of approximately 7.0 million barrels.

Inventory Measure Current Week Previous Week Weekly Change
Commercial Crude 427.3M barrels 426.4M barrels +0.9M
Gasoline 204.4M barrels 206.0M barrels −1.7M
Distillates 105.2M barrels 107.4M barrels −2.3M
Total Commercial Stocks ex-SPR 1,244.3M barrels 1,251.4M barrels −7.0M

This is one reason the petroleum release should be evaluated as a multi-variable balance rather than as a single crude-inventory number.

Lower Refinery Runs Help Explain the Inventory Split

U.S. refinery activity slowed meaningfully during the reporting week.

Refinery crude inputs fell by approximately 554,000 barrels per day to 16.257 million barrels per day.

Refinery utilization declined by 1.5 percentage points to 92.5%.

This combination provides an important explanation for the apparently contradictory stock movements.

Lower refinery throughput reduces the amount of crude being processed, which can contribute to a build in crude stocks. At the same time, lower refinery output can tighten gasoline and distillate inventories.

Balance-sheet interpretation: the crude build and product draws were not independent events. Lower refinery runs provided a common mechanism linking the two sides of the report.

Cushing Added a Negative Counter-Signal

Crude inventories at Cushing, Oklahoma increased by approximately 553,000 barrels.

EIA data put Cushing stocks at approximately 24.3 million barrels, up from about 23.7 million barrels one week earlier.

Cushing deserves separate attention because it is the designated delivery location for NYMEX WTI futures.

In this release, Cushing reinforced the negative crude-inventory signal, making the upward WTI response even more notable and highlighting the importance of the product-market data.

Crude Supply and Flow Data

The EIA overview also provided useful information on production, imports, exports and refinery demand.

U.S. Crude Measure Current Week Previous Week Weekly Change
Domestic Production 13.955M b/d 13.939M b/d +16K b/d
Crude Imports 5.698M b/d 5.877M b/d −179K b/d
Crude Exports 3.570M b/d 3.281M b/d +289K b/d
Net Crude Imports 2.128M b/d 2.596M b/d −468K b/d
Refinery Crude Inputs 16.257M b/d 16.811M b/d −554K b/d

Net crude imports fell substantially, while domestic production edged higher. However, the reduction in refinery demand was large enough to contribute to the commercial crude inventory build.

Product Supplied Remained Firm

Measures of petroleum products supplied also provided useful context for the tightening product balances.

Total products supplied averaged approximately 21.5 million barrels per day during the latest week.

On a four-week-average basis, total products supplied were approximately 20.8 million barrels per day, up 2.1% from the comparable period one year earlier.

Product Supplied Latest Week Four-Week Average Four-Week YoY Change
Total Petroleum Products 21.500M b/d 20.779M b/d +2.1%
Finished Motor Gasoline 8.689M b/d 8.721M b/d +0.3%
Distillate Fuel Oil 3.948M b/d 3.776M b/d +5.2%
Jet Fuel 1.809M b/d 1.761M b/d +6.5%

The strong year-over-year increase in four-week distillate product supplied is particularly relevant given the low level of distillate inventories.

Why Could WTI Rise Despite an Unexpected Crude Build?

Product Draws Were Much Larger Than Expected

Gasoline and distillate inventories both tightened materially more than consensus anticipated, providing a strong offset to the crude build.

Distillate Stocks Were Already Tight

Distillate inventories stood roughly 14% below their five-year seasonal average, increasing the information value of another 2.3M-barrel draw.

Total Commercial Stocks Declined

Aggregate petroleum stocks excluding the SPR fell by approximately 7M barrels despite the commercial crude build.

Refining Activity Fell

Lower refinery runs helped explain both the crude build and the simultaneous tightening in product inventories.

The Crude Headline Alone Was Insufficient

The September 30 release demonstrates why high-frequency petroleum analysis requires simultaneous processing of multiple fields.

A crude-only framework would have classified the release negatively: stocks built when the market expected a draw, and Cushing inventories also increased.

A broader balance-sheet framework would immediately have identified substantial tightening in gasoline and distillates, falling refinery runs and a seven-million-barrel decline in total commercial petroleum inventories.

Professional market takeaway: petroleum releases are multi-dimensional. The first price response can reflect the interaction among crude, products, Cushing, refinery runs, trade flows and demand indicators rather than the sign of any single inventory field.

Release-Window Reaction vs. the Broader Oil Session

The measured 24-tick WTI increase represents the immediate response around the scheduled EIA release.

It should be separated from the broader daily oil move.

Crude prices were already trading higher amid continued concerns over Middle Eastern supply, while tightening U.S. gasoline and distillate inventories added support following the EIA data.

WTI ultimately settled at approximately $90.42 per barrel, up about $1.04 on the session.

The distinction matters for event attribution: the release-window movement isolates the market's response to the new petroleum data, while the full-session price reflects a much broader information set.

Implications for Low-Latency Commodity Strategies

Process the Entire Petroleum Balance

Crude, gasoline, distillates and Cushing can deliver conflicting signals. A robust system needs to parse them concurrently rather than sequentially.

Compare Actual Data with Consensus

The absolute direction of a stock change is not sufficient. The magnitude of the deviation from market expectations determines how much new information the release contains.

Preserve Relationships Between Fields

Lower refinery runs helped explain why crude inventories increased while refined-product stocks declined. Treating each field independently can miss these balance-sheet relationships.

Separate Absolute Stocks from Weekly Changes

Commercial crude stocks were above their seasonal five-year average, while gasoline and distillates remained below theirs. Stock levels and weekly changes therefore provided different signals.

Distinguish Release-Window Movement from Daily Performance

HAAWKS measurements focus on the immediate market response surrounding the official publication. They are not intended to represent the direction or magnitude of the entire trading session.

HAAWKS Conclusion

The September 30 EIA petroleum release delivered a clear example of a mixed inventory report in which the crude headline did not determine the initial market direction.

Commercial crude inventories increased by 922,000 barrels against expectations for a 264,000-barrel draw.

Cushing stocks also increased by approximately 553,000 barrels.

Yet gasoline inventories fell by 1.7 million barrels and distillate inventories fell by 2.3 million barrels, both substantially exceeding expected draws.

Total commercial petroleum inventories excluding the SPR declined by approximately 7 million barrels, while refinery utilization fell to 92.5%.

HAAWKS measured an immediate 24-tick upward movement in WTI crude oil following the release.

For professional market participants, the release highlights the value of structured, low-latency access to the full petroleum data set. Crude inventories matter, but so do refined products, refinery activity, delivery-hub stocks, flows and implied demand.

Low-Latency Data. Structured Intelligence. Professional Execution.

Machine-Readable Data for Professional Markets

HAAWKS G4A provides low-latency, structured macroeconomic and commodity data covering the United States, Canada and Europe.

The feed is designed for systematic strategies, professional trading desks and latency-sensitive applications that require field-level economic and commodity data as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Energy Information Administration — Weekly Petroleum Status Report, September 30, 2026
    Official source for U.S. crude, gasoline, distillate, refinery, supply, inventory and product-supplied data.
  2. Reuters — Oil Prices Rise on Tight Fuel Markets, September 30, 2026
    Used for analyst expectations and broader post-release oil-market context.
  3. Reuters via BOE Report — U.S. Crude Stocks Rise, Gasoline and Distillate Inventories Fall
    Used for consensus estimates, Cushing inventories and refinery utilization context.
  4. HAAWKS internal tick-level market analysis — September 30, 2026
    Source for the measured immediate 24-tick upward WTI crude oil movement.
Data note: Market expectations can vary between surveys and data providers. Consensus figures used above are identified separately from official EIA statistics. HAAWKS market-movement figures are internal release-window measurements.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movement described is a historical measured market response and does not represent guaranteed or necessarily achievable trading profit. Tick values are instrument-specific. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

Softer PCE Inflation Sends US500 Up 68 Ticks as Dollar Weakens

According to our analysis USDJPY moved 15 pips, EURUSD moved 10 pips, US500 moved 68 ticks and XAUUSD 15 points (93 ticks, gold 15 points total) on US BEA Personal Income and Outlays and US BEA Gross Domestic Production (GDP) data on 30 September 2026.

USDJPY (15 pips)

EURUSD (10 pips)

US500 (68 ticks)

XAUUSD (15 points)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Softer PCE Inflation Drives Dollar Lower as US500 and Gold Rally

August PCE inflation undershot expectations while the third estimate of second-quarter U.S. GDP was revised sharply higher. The simultaneous BEA releases produced an immediate cross-asset repricing in FX, equities and gold.

September 30, 2026 • Release time: 8:30 a.m. ET • BEA PCE & GDP

Two major U.S. macroeconomic releases hit institutional trading systems simultaneously at 8:30 a.m. ET on September 30: August Personal Income and Outlays, including the Federal Reserve's preferred PCE inflation measures, and the third estimate of second-quarter GDP.

The combined signal was unusual. Inflation was softer than expected, while economic growth was revised materially higher.

In the first minutes after the release, markets appeared to give greater weight to the inflation surprise and its implications for Federal Reserve policy.

HAAWKS measured an immediate 10-tick rise in EUR/USD, 15-tick decline in USD/JPY, 68-tick rise in US500 and 15-point rise in XAU/USD.

Institutional read-through: the cross-asset configuration — weaker USD, stronger equities and stronger gold — was consistent with a decline in near-term U.S. rate-hike expectations. The much stronger GDP revision provided an important counter-signal, but it did not dominate the initial release-window repricing.

Immediate Cross-Asset Reaction

EUR/USD +10 Ticks USD weaker
USD/JPY −15 Ticks USD weaker
US500 +68 Ticks Immediate equity rally
XAU/USD +15 Points Gold higher
Instrument HAAWKS Measured Move Direction Institutional Interpretation
EUR/USD 10 ticks Higher Broadly consistent with a softer U.S. dollar following the lower-than-expected PCE inflation readings.
USD/JPY 15 ticks Lower Reinforced the initial USD-negative interpretation across major FX pairs.
US500 68 ticks Higher Lower expected policy-rate pressure initially supported equity valuations.
XAU/USD 15 points Higher Gold benefited from the initial decline in U.S. rate expectations and dollar weakness.

August PCE: The Dominant Release-Window Signal

The principal inflation measures came in below market expectations. Headline PCE increased 0.3% month over month, compared with a Reuters consensus estimate of 0.4%.

On a year-over-year basis, headline PCE inflation was 3.4%, below the approximately 3.7% expected before the release.

Core PCE, which excludes food and energy and receives particular attention from Federal Reserve policymakers, rose 0.2% month over month and 3.0% year over year.

Headline PCE MoM +0.3% Reuters expectation: +0.4%
Headline PCE YoY 3.4% Reuters expectation: 3.7%
Core PCE MoM +0.2% Softer underlying inflation
Core PCE YoY 3.0% Revised inflation profile
HAAWKS view: for the first market reaction, the inflation surprise carried greater policy relevance than the backward-looking GDP revision. The combination of EUR/USD higher, USD/JPY lower, US500 higher and gold higher is consistent with the market initially reducing the probability of additional near-term Federal Reserve tightening.

An Important Institutional Caveat: The PCE Data Were Revised

The September 30 release was not a standard monthly update in isolation. It incorporated BEA's 2026 annual update of the National Economic Accounts, with revisions to personal income, spending and inflation estimates beginning in January 2021.

That distinction matters for systematic interpretation.

July headline PCE inflation was revised down to 0.1% month over month, while July core PCE was also revised to 0.1%.

Reuters reported that methodology changes affecting areas including portfolio-management services, software and legal services contributed materially to lower historical inflation readings.

Institutional implication: a low-latency model should distinguish a genuinely new monthly inflation surprise from revisions caused by annual benchmarking or methodology changes. Both can move markets, but they represent different information structures and may deserve different model weights.

The Consumer Remained Exceptionally Strong

The inflation data were softer, but the broader household data were not weak.

Nominal personal consumption expenditures increased 0.9% in August, equivalent to a $190.8 billion increase.

Inflation-adjusted real PCE increased 0.6%, indicating that the spending acceleration was not merely a function of higher prices.

Personal income increased only 0.2%, while disposable personal income increased 0.3%. Real disposable income was unchanged.

The personal saving rate declined to 4.1%, showing that the strength in consumption was accompanied by a lower share of disposable income being saved.

August Household Measure BEA Result Institutional Read-Through
Personal Income +0.2% Income growth remained positive but materially lagged consumption growth.
Disposable Personal Income +0.3% Moderate nominal household-income growth.
Real DPI 0.0% No monthly increase in inflation-adjusted disposable income.
Nominal PCE +0.9% Very strong consumer spending despite elevated borrowing costs.
Real PCE +0.6% Indicates genuine volume growth rather than only price effects.
Saving Rate 4.1% Household spending growth continued to outpace income growth.

GDP Delivered a Powerful Counter-Signal

At exactly the same 8:30 a.m. ET release time, BEA published its third estimate of second-quarter GDP.

Real GDP growth was revised sharply higher to an annualized 2.2%, compared with 1.5% in the second estimate.

The 0.7-percentage-point upward revision reflected stronger investment, consumer spending and government spending.

Q2 U.S. Measure Second Estimate Third Estimate Institutional Significance
Real GDP 1.5% 2.2% Material upward revision to aggregate economic growth.
Real Final Sales to Private Domestic Purchasers 4.2% 4.6% Strong underlying private domestic demand.
Real GDI 2.2% 2.6% Income-side measure also pointed to firmer activity.
Average of GDP and GDI 1.8% 2.4% Broader confirmation that Q2 activity was stronger than previously estimated.

Underlying Domestic Demand Was Stronger Than Headline GDP

For institutional macro investors, the composition of GDP may be more informative than the headline 2.2% figure.

Real final sales to private domestic purchasers — consumer spending plus private fixed investment — increased at a 4.6% annualized rate.

This measure removes several volatile components of GDP and provides a cleaner indication of underlying private domestic demand.

BEA attributed the Q2 GDP expansion to consumer spending, investment and exports, while increased imports subtracted from the headline calculation.

Among industries, the strongest contributors included real estate and rental and leasing, information, durable-goods manufacturing, and finance and insurance.

Corporate Profits Added to the Growth Signal

Profits from current production increased by $384.0 billion in the second quarter, although that figure was revised down by $16.9 billion from the previous estimate.

The combination of stronger consumer activity, investment and corporate earnings helps explain why the GDP release offered a distinctly growth-positive counterweight to the softer inflation figures.

Why the Inflation Signal Won the First Policy Repricing

Inflation Undershot Expectations

Headline monthly PCE rose 0.3% versus a 0.4% Reuters consensus, while the annual rate was 3.4% versus approximately 3.7% expected.

The Data Were Directly Relevant to the Fed

PCE inflation is the Federal Reserve's preferred consumer-inflation framework, making an inflation surprise immediately relevant to policy-rate pricing.

GDP Was Backward Looking

The 2.2% GDP figure described activity during April through June. The August PCE data provided more recent information about the inflation environment.

Growth Remained a Hawkish Counterweight

Strong consumption, a 4.6% increase in private domestic final sales and the GDP revision argue against interpreting the release as a simple growth slowdown.

Institutional takeaway: this was closer to a "soft inflation, strong demand" configuration than a straightforward dovish macro release. The first price response favored the inflation signal, but the underlying growth data remained too strong to justify treating the report as an unambiguously weak U.S. macro outcome.

Federal Reserve Expectations Repriced Lower

The immediate rates-market response reinforced the cross-asset signal.

Reuters reported that the implied probability of another Federal Reserve rate increase at the October meeting fell to approximately 41.5% after the data, from roughly 51.5% immediately beforehand.

U.S. Treasury yields initially declined and the dollar weakened, consistent with the HAAWKS FX, equity and gold observations.

That repricing did not eliminate the possibility of additional tightening. Inflation remained above the Federal Reserve's longer-run objective and household demand remained exceptionally resilient.

One Timestamp, Multiple Macro Signals

September 30 also illustrates a problem that matters directly to institutional news-trading infrastructure: multiple high-value data sets can be released at precisely the same timestamp.

At 8:30 a.m. ET, systems were required to process not merely one PCE figure but a large matrix of information including:

Data Family Examples of Relevant Fields Primary Market Channel
PCE Inflation Headline MoM, headline YoY, core MoM, core YoY Federal Reserve policy expectations
Household Income Personal income, disposable income, real DPI Household purchasing capacity
Consumer Spending Nominal PCE, real PCE, goods and services Current-quarter growth expectations
GDP Real GDP, final sales, investment, consumption Growth and policy outlook
GDI Real GDI and GDP/GDI average Confirmation of economic activity
Corporate Profits Current-production profits and industry measures Equity and growth fundamentals

Implications for Institutional News-Trading Systems

Field-Level Parsing Is Essential

A system reacting only to headline PCE could miss the interaction among core inflation, spending, income, GDP revisions and prior-period revisions.

Release Vintage Must Be Preserved

The 2026 annual update changed historical PCE and GDP estimates. Institutional research and systematic backtesting therefore need to distinguish the data available in real time from subsequently revised historical series.

Surprise Direction Is Not Enough

Softer inflation was dovish, while stronger GDP and spending were comparatively hawkish. A robust model needs to evaluate the magnitude, timeliness and policy relevance of competing surprises.

Cross-Asset Confirmation Adds Information

EUR/USD higher, USD/JPY lower, gold higher and equities higher provided a coherent initial cross-asset signal consistent with reduced near-term U.S. rate expectations.

Release-Window Movement Is Not Full-Session Performance

HAAWKS measurements isolate the immediate market response to the scheduled release. Subsequent price action incorporates liquidity, positioning, policy commentary and additional economic information.

Immediate Reaction vs. the Full Trading Session

The initial response should not be confused with the eventual daily close.

HAAWKS measured a strong 68-tick US500 increase during the release window, reflecting the first repricing of the new information.

The broader U.S. equity session subsequently became more mixed as investors continued to digest the strength of economic activity and elevated longer-term interest rates.

This distinction is central to institutional event analysis: release-window attribution asks a different question from end-of-day market attribution.

HAAWKS Conclusion

The September 30 BEA releases delivered one of the more complex U.S. macro combinations for systematic news traders: softer inflation alongside substantially stronger growth and exceptionally resilient consumer spending.

August headline PCE increased 0.3% month over month and 3.4% year over year, while core PCE increased 0.2% and 3.0%, respectively.

At the same time, second-quarter real GDP was revised from 1.5% to 2.2%, real final sales to private domestic purchasers increased 4.6%, and August nominal consumer spending surged 0.9%.

The market's initial interpretation nevertheless leaned toward the inflation side of the release.

HAAWKS measured EUR/USD +10 ticks, USD/JPY −15 ticks, US500 +68 ticks and XAU/USD +15 points in the immediate release window.

For institutional trading systems, the event demonstrates why a simultaneous macro release cannot be reduced to one headline field. Current values, consensus expectations, prior revisions, annual benchmarking, growth composition and cross-asset confirmation all need to be evaluated while the market is repricing.

Low-Latency Data. Structured Intelligence. Institutional Execution.

Low-Latency Macro Data for Institutional Markets

HAAWKS G4A provides structured, machine-readable macroeconomic and commodity data covering the United States, Canada and Europe.

The feed is designed for professional news-trading desks, systematic macro strategies and latency-sensitive applications that require field-level data immediately when official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Economic Analysis — Personal Income and Outlays, August 2026
    Official source for personal income, consumer spending, headline and core PCE inflation and the personal saving rate.
  2. U.S. Bureau of Economic Analysis — GDP Third Estimate, Industries and Corporate Profits, Second Quarter 2026
    Official source for real GDP, GDI, private domestic final sales, corporate profits and industry-level revisions.
  3. Reuters — U.S. Inflation Rises Less Than Expected in August
    Used for market consensus, Federal Reserve pricing and post-release rates and FX context.
  4. HAAWKS internal tick-chart analysis — September 30, 2026
    Source for the measured immediate release-window reactions: EUR/USD +10 ticks, USD/JPY −15 ticks, US500 +68 ticks and XAU/USD +15 points.
Data note: The September 30 releases incorporated BEA's 2026 annual update of the National Economic Accounts. Historical figures and prior-period readings may therefore differ from figures originally published in earlier release vintages. Quarterly GDP growth rates are seasonally adjusted annual rates and should not be directly compared with monthly or year-over-year PCE inflation rates without accounting for the different measurement basis.

Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The market movements described are historical measured release-window movements and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific and are not standardized measures of financial return. Actual trading results depend on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

September 2026 WASDE: Corn Jumps 52 Ticks, Wheat 32 and Soybeans 28

Comment

September 2026 WASDE: Corn Jumps 52 Ticks, Wheat 32 and Soybeans 28

According to our analysis ZC moved 52 ticks, ZW moved 32 ticks and ZS moved 28 ticks (total: 112 ticks) on USDA World Agricultural Supply and Demand Estimates (WASDE) data on 11 September 2026.


HAAWKS Research

September WASDE Triggers Fast Grain Moves: Corn +52 Ticks, Wheat +32 and Soybeans +28

USDA cut the U.S. corn crop and tightened corn and soybean balances, while wheat delivered a more mixed global supply picture. CBOT grain futures reacted immediately to the 12:00 p.m. ET release.

September 11, 2026 • Release time: 12:00 p.m. ET • USDA WASDE

The September 2026 World Agricultural Supply and Demand Estimates produced rapid moves across the major CBOT grain markets as traders processed new USDA forecasts for corn, wheat and soybeans.

HAAWKS measured an immediate 52-tick rise in corn futures (ZC), a 32-tick rise in wheat futures (ZW) and a 28-tick rise in soybean futures (ZS) following the 12:00 p.m. ET release.

The report contained very different signals across the three crops. Corn supplies tightened substantially compared with USDA's August projections. Soybean production increased, but stronger export demand reduced projected ending stocks. U.S. wheat supply and use was largely unchanged, while the global wheat balance became looser.

HAAWKS first read: the initial futures reaction was higher across all three contracts, but the WASDE was not uniformly bullish relative to trade expectations. This is an important distinction for professional news traders: month-to-month USDA revisions and surprise versus consensus are two different signals.

Immediate Futures Market Reaction

CBOT Corn — ZC +52 Ticks Immediate HAAWKS release-window move
CBOT Wheat — ZW +32 Ticks Immediate HAAWKS release-window move
CBOT Soybeans — ZS +28 Ticks Immediate HAAWKS release-window move

Corn: USDA Cuts Yield, Production and Ending Stocks

Corn contained the clearest month-over-month tightening in the September report.

USDA reduced the 2026/27 national corn yield by 2.2 bushels per acre, from 180.7 to 178.5 bpa.

Production was cut by 213 million bushels to 15.800 billion bushels.

With lower beginning stocks and smaller production only partly offset by reduced feed demand, projected U.S. ending stocks fell from 1.653 billion to 1.567 billion bushels.

U.S. Corn August USDA Trade Average September USDA Interpretation
Yield 180.7 bpa 178.1 bpa 178.5 bpa Large cut vs. August, but slightly above consensus.
Production 16.013B bu 15.768B bu 15.800B bu 213M-bushel USDA cut, but slightly above the trade average.
2026/27 Ending Stocks 1.653B bu 1.533B bu 1.567B bu Tighter month over month, though not as tight as expected.
Season-Average Farm Price $4.50/bu — $4.80/bu USDA raised the price forecast by $0.30.
Corn takeaway: the balance sheet tightened substantially compared with August, which was supportive, but the headline yield, production and ending stocks figures were all slightly above pre-report trade averages. For a news trader, that makes the release more nuanced than simply calling the corn figures a bullish surprise.

Soybeans: Bigger Crop, but Stronger Exports Tighten Carryout

Soybeans delivered a mixed supply-and-demand signal.

USDA increased the soybean yield from 52.7 to 52.8 bushels per acre and raised production by 16 million bushels to a record 4.535 billion bushels.

That increase in supply was more than absorbed by stronger demand. USDA raised projected soybean exports by 25 million bushels to approximately 1.685 billion bushels.

As a result, projected ending stocks actually declined from 320 million to 310 million bushels.

U.S. Soybeans August USDA Trade Average September USDA Interpretation
Yield 52.7 bpa 52.5 bpa 52.8 bpa Higher than both August and the trade average.
Production 4.519B bu 4.492B bu 4.535B bu Larger crop than traders expected.
Exports 1.660B bu — 1.685B bu USDA raised exports by 25M bushels.
2026/27 Ending Stocks 320M bu 289M bu 310M bu Lower than August, but above the trade average.
Season-Average Farm Price $11.40/bu — $12.00/bu USDA raised its price projection by $0.60.

Wheat: U.S. Balance Unchanged, Global Supplies Rise

Wheat was arguably the most interesting market response because the underlying WASDE changes were less supportive than the immediate 32-tick upward move might suggest.

USDA left aggregate U.S. wheat supply and use unchanged. Production remained at 1.531 billion bushels and ending stocks remained at 717 million bushels.

USDA did make changes within wheat classes. White wheat exports were raised by 20 million bushels, while Hard Red Winter exports were reduced by 15 million and Hard Red Spring exports by 5 million.

The season-average wheat price was increased by $0.20 to $6.40 per bushel.

Globally, however, wheat supplies increased substantially. USDA raised production forecasts for Australia, Canada and Ukraine, while world ending stocks increased to approximately 276.3 million metric tons.

Wheat Measure August USDA Trade Average September USDA Interpretation
U.S. Production 1.531B bu — 1.531B bu Unchanged.
U.S. Ending Stocks 717M bu 720M bu 717M bu Slightly below the average trade estimate.
World Ending Stocks 273.3 MMT about 273.2 MMT 276.3 MMT The clearest bearish supply surprise among the three crops.
U.S. Farm Price $6.20/bu — $6.40/bu Raised by $0.20.
Wheat takeaway: the immediate 32-tick ZW rally should not be interpreted as proof that the WASDE itself was fundamentally bullish for wheat. Global wheat supplies and ending stocks increased, while the U.S. balance was essentially unchanged. Positioning, order flow and the interaction of multiple USDA data points can matter during the first seconds after a major agricultural release.

Global Ending Stocks: Another Layer for News Traders

The global balance sheets provided an important counterweight to the tighter U.S. corn and soybean figures.

2026/27 Global Ending Stocks August USDA Trade Estimate September USDA Signal vs. Consensus
Corn 274.7 MMT about 271.9 MMT 272.1 MMT Much tighter vs. August, but slightly above expectations.
Soybeans 124.2 MMT about 123.1 MMT 124.0 MMT Slightly tighter month over month, but above consensus.
Wheat 273.3 MMT about 273.2 MMT 276.3 MMT Significantly above expectations.

Why Can Futures Rally on a Mixed WASDE?

Algorithms Process Many Fields at Once

WASDE is not one number. Yield, production, exports, domestic use, ending stocks, global stocks and price forecasts arrive together. Different trading models may assign different weights to each field.

Month-over-Month Changes Matter

Corn production fell by 213M bushels from USDA's August estimate, while U.S. corn ending stocks declined by 86M bushels. Those are substantial directional changes even though the final figures were slightly above trade consensus.

Consensus Matters Too

Professional traders also compare the published figures with pre-report expectations. A number can tighten relative to last month and still be less bullish than traders anticipated.

Positioning Can Amplify the First Move

Futures prices reflect existing positions as well as fundamentals. Stop orders, hedging flows, spread positions and thin liquidity immediately after a release can amplify short-duration moves.

Immediate Reaction vs. the Rest of the Session

The HAAWKS measurements describe the immediate release-window reaction. They should not be confused with the direction of grain futures over the entire trading day.

HAAWKS recorded upward moves of 52 ticks in ZC, 32 ticks in ZW and 28 ticks in ZS following the USDA release.

Later in the session, grain markets reassessed the complete balance sheets. CME noted that corn and soybean futures ultimately finished the week lower, illustrating how an initial data-release move can differ from the subsequent market trend.

News-trader takeaway: release-window trading measures how prices respond when new information first enters the market. Later price action reflects additional interpretation, positioning, liquidity and broader market factors.

What the September WASDE Shows News Traders

WASDE Requires Multi-Field Parsing

Unlike a simple one-number economic release, WASDE contains hundreds of interconnected supply-and-demand fields. A professional system needs to identify which numbers changed and which differences matter most.

U.S. and Global Numbers Can Conflict

U.S. corn supplies tightened materially while world corn stocks still came in slightly above expectations. Wheat provided an even clearer example: U.S. ending stocks were slightly below the trade average, while world stocks were sharply above it.

Prior Estimates Are as Important as Consensus

Comparing September with August tells a trader how USDA changed its fundamental outlook. Comparing September with market expectations tells a trader how surprising the new information actually was.

Speed Alone Is Not Enough

Receiving the report quickly is valuable, but an automated system must also correctly map the crop, marketing year, country, unit and balance sheet field before acting.

Measured Movement Is Not Guaranteed Profit

The 52-, 32- and 28-tick figures represent historical measured price movement. Actual results depend on market depth, latency, spread, slippage, execution venue, order type and risk management.

HAAWKS Conclusion

The September 2026 WASDE triggered rapid price movement across all three major CBOT grain contracts monitored by HAAWKS.

HAAWKS measured approximately 52 ticks higher in corn futures, 32 ticks higher in wheat futures and 28 ticks higher in soybeans in the immediate release window.

Corn showed the clearest month-over-month tightening. USDA cut the national yield to 178.5 bpa, lowered production by 213 million bushels and reduced projected ending stocks to 1.567 billion bushels.

Soybean production increased to 4.535 billion bushels, but higher exports reduced ending stocks to 310 million bushels.

U.S. wheat supply and use was largely unchanged, while the global wheat balance became looser and world ending stocks rose to roughly 276.3 million metric tons.

The release therefore provides an important lesson for professional news traders: the initial price reaction cannot always be explained by one headline number or even by a simple bullish-versus-bearish label.

Low-latency access to structured USDA data allows trading systems to compare many fields simultaneously — current values, previous estimates, consensus expectations and global balances — while the market is still repricing.

Trade smart. Stay informed. Stay ahead.

Machine-Readable Data for Professional News Traders

HAAWKS G4A provides low-latency machine-readable U.S. macroeconomic and commodity data, together with macroeconomic data covering Canada and Europe.

Data is delivered via API access in Chicago, New York and London for professional and latency-sensitive news-trading applications.

Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. USDA — World Agricultural Supply and Demand Estimates, September 11, 2026
    Official source for U.S. and world corn, wheat and soybean supply-and-demand forecasts.
  2. USDA — WASDE Report
    Official WASDE publication page and release schedule.
  3. Price Futures Group — September 11 Grain Report
    Reproduces the pre-report analyst averages and ranges for U.S. production, yield and ending stocks used in this analysis.
  4. DTN — USDA Lowers Corn Yield 2.2 BPA, Slightly Increases Soy Yield
    Independent post-release analysis of the September WASDE and Crop Production reports.
  5. CME Group — Corn and Soybean Futures React to Latest WASDE Estimates
    Used for broader post-release grain-market context.
  6. HAAWKS internal tick-chart analysis — September 11, 2026
    Source for the measured immediate market reactions: ZC +52 ticks, ZW +32 ticks and ZS +28 ticks.
Data note: Pre-report market expectations can vary between surveys and data vendors. Figures identified as trade averages in this article are external consensus estimates, while USDA figures are official published data. HAAWKS market movements are internal release-window measurements.

Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick values are contract-specific. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

August 2026 CPI: Hotter Core CPI Sends US500 Down 48 Ticks and Gold Down 19 Points

According to our analysis US500 moved 48 ticks and XAUUSD 19 points on US BLS Consumer Price Index (CPI) data on 11 September 2026.

US500 (48 ticks)

XAUUSD (19 points)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Hotter Core CPI Sends US500 Down 48 Ticks and Gold Down 19 Points

August U.S. inflation data delivered a hotter-than-expected core CPI reading, triggering an immediate hawkish repricing across equities, gold and interest-rate expectations.

September 11, 2026 • Release time: 8:30 a.m. ET • U.S. Consumer Price Index

The August 2026 U.S. Consumer Price Index delivered a mixed headline but a more important upside surprise in underlying inflation.

Headline CPI increased 0.4% month over month, in line with expectations, while the annual rate stood at 3.4%.

The more market-sensitive core measure increased 0.3% month over month, above the 0.2% consensus forecast. Core inflation was 2.4% year over year.

HAAWKS first read: the headline CPI result itself was not the key surprise. The immediate hawkish signal came primarily from the hotter 0.3% core CPI reading versus 0.2% expected. HAAWKS measured an initial 48-tick decline in US500 and 19-point decline in XAU/USD.

August CPI: Estimates vs. Actual

Headline CPI MoM +0.4% Expected: +0.4%
Headline CPI YoY 3.4% Expected: 3.4%
Core CPI MoM +0.3% Expected: +0.2%
Core CPI YoY 2.4% Expected: 2.4%
Inflation Measure Consensus Actual HAAWKS News-Trader Read
Headline CPI MoM +0.4% +0.4% Matched expectations and therefore provided little standalone surprise.
Headline CPI YoY 3.4% 3.4% Annual headline inflation remained elevated.
Core CPI MoM +0.2% +0.3% The key upside surprise and the most clearly hawkish element of the release.
Core CPI YoY 2.4% 2.4% Matched expectations.

Immediate Market Reaction

HAAWKS tick-chart analysis captured an immediate downside reaction in both US500 and gold following the 8:30 a.m. ET inflation release.

US500 −48 Ticks Immediate release-window decline
XAU/USD −19 Points Immediate release-window decline
Market Measured Move Direction News-Trader Interpretation
US500 48 ticks Lower The hotter core CPI increased expectations for tighter Federal Reserve policy, initially pressuring equities.
XAU/USD 19 points Lower Higher expected policy rates reduced the immediate appeal of non-yielding gold.

Why the Core CPI Number Mattered Most

For news traders, this release provides another example of why headline inflation cannot be read in isolation.

Headline CPI at 0.4% was in line with expectations. If that had been the only relevant data point, the inflation release would have contained relatively little immediate surprise.

Core CPI told a different story. Prices excluding food and energy rose 0.3% during August instead of the 0.2% economists had expected.

That difference strengthened the view that underlying inflation pressure remained persistent enough to influence Federal Reserve policy expectations.

HAAWKS view: the initial US500 and gold reaction was driven less by the headline CPI number, which broadly matched expectations, and more by the upside surprise in monthly core inflation and its implications for interest rates.

What Drove August Inflation?

CPI Component August MoM 12-Month Change HAAWKS Read-Through
All Items +0.4% +3.4% Headline monthly inflation accelerated.
Core CPI +0.3% +2.4% Monthly core inflation exceeded consensus.
Energy +2.1% +16.3% Energy remained an important source of headline inflation pressure.
Gasoline +3.9% +27.4% Gasoline accounted for more than one-third of the monthly increase in headline CPI.
Shelter +0.3% +3.0% Shelter accelerated from the previous month.
Food +0.1% +2.7% Food inflation remained comparatively moderate.
Services Less Energy Services +0.3% +3.0% Continued services inflation remained relevant to the underlying inflation picture.

Gasoline Drove Part of the Headline Increase

Energy prices were an important contributor to August inflation. The energy index increased 2.1% during the month.

Gasoline prices increased 3.9% and accounted for more than one-third of the monthly increase in the all-items CPI. Over the previous 12 months, gasoline prices increased 27.4%.

Fuel oil also increased sharply during the month, while other energy components were less inflationary.

Underlying Inflation Was Broader Than Energy

The core inflation increase was distributed across several categories, reinforcing the importance of looking beyond volatile energy prices.

Shelter increased 0.3%, while several transportation and service categories also recorded price increases.

This combination helped explain why the monthly core figure exceeded expectations despite some categories continuing to show weaker price pressure.

The Federal Reserve Repricing

The CPI report arrived shortly before the September Federal Reserve policy decision, increasing its significance for rate-sensitive markets.

Recent employment data had already demonstrated stronger labor-market conditions. The hotter core CPI figure added another argument for maintaining tighter monetary policy.

Core CPI Beat Expectations

A 0.3% monthly increase compared with 0.2% expected was the clearest hawkish surprise in the report.

Energy Inflation Accelerated

Energy increased 2.1%, with gasoline up 3.9%, keeping headline inflation pressure elevated.

Shelter Increased 0.3%

Shelter remained an important component of underlying consumer inflation.

Policy Expectations Changed

The combination of stronger employment data and firmer core inflation reinforced expectations for restrictive monetary policy.

Immediate Reaction vs. the Rest of the Trading Session

News traders should distinguish the immediate release-window response from subsequent full-session market performance.

HAAWKS measured an initial 48-tick decline in US500 and a 19-point decline in XAU/USD around the CPI release.

Markets can subsequently retrace or reverse these initial moves as liquidity normalizes, traders reassess individual components and additional market information enters prices.

News-trader takeaway: release-window analysis measures the market's first response to new information. It should not be confused with the direction or size of the move over the entire trading session.

What This CPI Release Shows News Traders

Actual vs. Consensus Is the Primary Signal

Headline CPI at 0.4% carried limited surprise because it matched expectations. Core CPI at 0.3% mattered because the market had expected only 0.2%.

Headline and Core CPI Can Send Different Signals

A professional news-trading system should distinguish all-items CPI from the core measure. Each field can have a different surprise magnitude and a different effect on interest-rate expectations.

Component Data Adds Context

Gasoline, energy, shelter and service-price components help traders understand whether inflation pressure is concentrated in volatile categories or is becoming more broadly distributed.

Cross-Asset Confirmation Matters

The initial simultaneous declines in US500 and gold were consistent with a more hawkish interpretation of the inflation data.

Measured Movement Is Not Guaranteed Profit

The 48-tick US500 and 19-point XAU/USD moves represent measured historical price movement. Actual execution can differ materially due to latency, spreads, liquidity, slippage, order type and execution venue.

HAAWKS Conclusion

The August CPI report delivered a more nuanced result than the headline number alone suggested.

Headline CPI increased 0.4%, broadly matching market expectations, while annual inflation stood at 3.4%.

The key market-moving surprise was core CPI, which increased 0.3% month over month against expectations for 0.2%.

Energy also accelerated, with gasoline increasing 3.9%, while shelter prices rose 0.3%.

HAAWKS measured an immediate 48-tick decline in US500 and 19-point decline in XAU/USD following the release.

For professional news traders, the release demonstrates why receiving only the headline CPI figure is not enough. Headline CPI, core CPI, expectations and individual components need to be processed together to identify the actual surprise and understand the market's initial interpretation.

Trade smart. Stay informed. Stay ahead.

Built for Professional News Traders

HAAWKS G4A provides low-latency machine-readable data for U.S. macroeconomic and commodity releases, together with macroeconomic data from Norway, Sweden, Switzerland and Turkey, as well as ECB interest-rate decisions and statements.

All data is machine readable and available via API access in Chicago, New York and London. Free trials are available for qualified professionals.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Labor Statistics — Consumer Price Index, August 2026
    Official source for headline CPI, core CPI and detailed inflation components.
  2. HAAWKS internal tick-chart analysis — September 11, 2026
    Source for the measured immediate release-window movements of 48 ticks in US500 and 19 points in XAU/USD.
Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific measures and should not be treated as standardized financial returns. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment