Viewing entries tagged
FX

Comment

EIA Petroleum Data: WTI Rises 24 Ticks as Product Draws Offset Crude Build

According to our analysis WTI crude oil moved 24 ticks on DOE Weekly Petroleum Status Report (WPSR) data on 30 September 2026.

WTI crude oil (24 ticks)
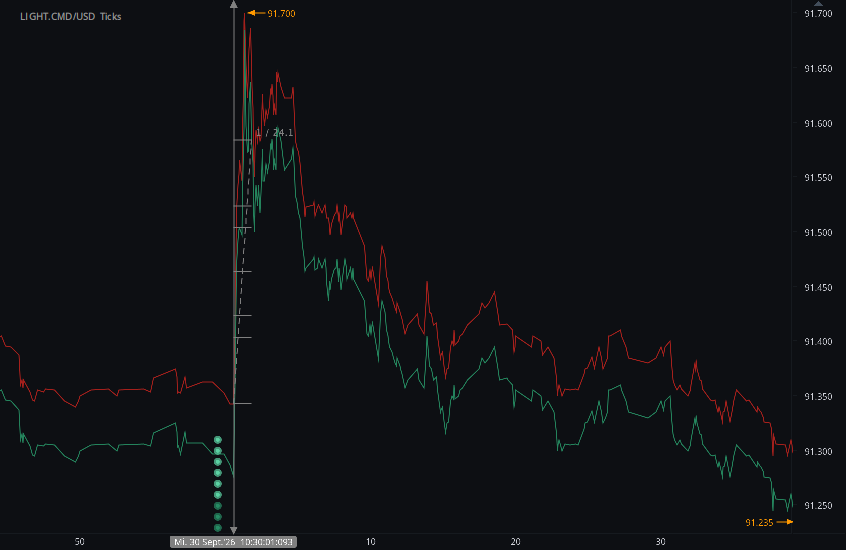
Charts are exported from JForex (Dukascopy).


HAAWKS Research

WTI Rises 24 Ticks as Sharp Product Draws Offset an Unexpected Crude Build

The September 30 EIA petroleum release delivered conflicting inventory signals: U.S. commercial crude stocks unexpectedly increased, while gasoline and distillate inventories fell substantially more than expected.

September 30, 2026 • Release time: 10:30 a.m. ET • EIA Weekly Petroleum Data

The September 30 U.S. Energy Information Administration petroleum release presented professional commodity desks with a distinctly two-sided inventory signal.

Commercial crude oil inventories increased by 922,000 barrels during the week ending September 25, directly opposing expectations for an inventory draw.

The refined-product side of the balance sheet, however, told a very different story.

Gasoline inventories declined by approximately 1.7 million barrels, while distillate stocks fell by approximately 2.3 million barrels. Both draws were significantly larger than market expectations.

HAAWKS release-window measurement: WTI crude oil moved approximately 24 ticks higher following the 10:30 a.m. ET release. The initial price response suggests that the market placed substantial weight on tightening refined-product inventories despite the unexpected build in crude.

Inventory Results vs. Market Expectations

Commercial Crude +0.922M Reuters expectation: −0.264M barrels
Gasoline −1.7M Reuters expectation: −0.485M
Distillates −2.3M Reuters expectation: −0.190M
WTI Reaction +24 Ticks HAAWKS release-window measurement
Petroleum Field Market Expectation EIA Actual Surprise Market Read-Through
Commercial Crude Oil −0.264M barrels +0.922M barrels Build vs. expected draw Negative for the crude balance in isolation.
Gasoline −0.485M barrels −1.7M barrels Larger draw Supportive product-market signal and substantially tighter than consensus.
Distillates −0.190M barrels −2.3M barrels Much larger draw Particularly relevant given already constrained diesel and heating-oil inventories.
Cushing, Oklahoma — +0.553M barrels Build A negative counter-signal at the NYMEX WTI delivery hub.

WTI Moves 24 Ticks Higher

HAAWKS tick-level analysis recorded a rapid upward response in WTI immediately following the scheduled petroleum release.

+24 WTI Crude Oil Ticks

Measured during the immediate release window following the September 30, 2026 EIA petroleum data.

The move is notable because the crude inventory headline itself was weaker than expected.

A model reacting only to the commercial crude figure would have seen a 922,000-barrel build against expectations for a 264,000-barrel draw. That represents a swing of almost 1.2 million barrels relative to consensus.

Yet WTI initially moved higher. The broader petroleum balance helps explain why.

The Product Draws Were the More Important Tightness Signal

Gasoline and distillates both delivered materially larger inventory draws than expected.

Gasoline stocks fell from approximately 206.0 million barrels to 204.4 million barrels, a decline of about 1.7 million barrels.

Distillate inventories fell from approximately 107.4 million barrels to 105.2 million barrels, a decline of roughly 2.3 million barrels.

The absolute stock levels are also relevant. Gasoline inventories remained approximately 7% below their five-year seasonal average, while distillate inventories were approximately 14% below the five-year average.

HAAWKS view: the crude build weakened the upstream inventory signal, but the significantly larger-than-expected gasoline and distillate draws reinforced an already tight refined-product market. For WTI pricing, the complete petroleum balance carried more information than the crude headline alone.

Total Commercial Petroleum Inventories Fell 7 Million Barrels

Another important detail is that aggregate commercial petroleum stocks declined despite the rise in crude inventories.

EIA data showed total petroleum stocks excluding the Strategic Petroleum Reserve falling from approximately 1.2514 billion barrels to 1.2443 billion barrels.

That represents a weekly decline of approximately 7.0 million barrels.

Inventory Measure Current Week Previous Week Weekly Change
Commercial Crude 427.3M barrels 426.4M barrels +0.9M
Gasoline 204.4M barrels 206.0M barrels −1.7M
Distillates 105.2M barrels 107.4M barrels −2.3M
Total Commercial Stocks ex-SPR 1,244.3M barrels 1,251.4M barrels −7.0M

This is one reason the petroleum release should be evaluated as a multi-variable balance rather than as a single crude-inventory number.

Lower Refinery Runs Help Explain the Inventory Split

U.S. refinery activity slowed meaningfully during the reporting week.

Refinery crude inputs fell by approximately 554,000 barrels per day to 16.257 million barrels per day.

Refinery utilization declined by 1.5 percentage points to 92.5%.

This combination provides an important explanation for the apparently contradictory stock movements.

Lower refinery throughput reduces the amount of crude being processed, which can contribute to a build in crude stocks. At the same time, lower refinery output can tighten gasoline and distillate inventories.

Balance-sheet interpretation: the crude build and product draws were not independent events. Lower refinery runs provided a common mechanism linking the two sides of the report.

Cushing Added a Negative Counter-Signal

Crude inventories at Cushing, Oklahoma increased by approximately 553,000 barrels.

EIA data put Cushing stocks at approximately 24.3 million barrels, up from about 23.7 million barrels one week earlier.

Cushing deserves separate attention because it is the designated delivery location for NYMEX WTI futures.

In this release, Cushing reinforced the negative crude-inventory signal, making the upward WTI response even more notable and highlighting the importance of the product-market data.

Crude Supply and Flow Data

The EIA overview also provided useful information on production, imports, exports and refinery demand.

U.S. Crude Measure Current Week Previous Week Weekly Change
Domestic Production 13.955M b/d 13.939M b/d +16K b/d
Crude Imports 5.698M b/d 5.877M b/d −179K b/d
Crude Exports 3.570M b/d 3.281M b/d +289K b/d
Net Crude Imports 2.128M b/d 2.596M b/d −468K b/d
Refinery Crude Inputs 16.257M b/d 16.811M b/d −554K b/d

Net crude imports fell substantially, while domestic production edged higher. However, the reduction in refinery demand was large enough to contribute to the commercial crude inventory build.

Product Supplied Remained Firm

Measures of petroleum products supplied also provided useful context for the tightening product balances.

Total products supplied averaged approximately 21.5 million barrels per day during the latest week.

On a four-week-average basis, total products supplied were approximately 20.8 million barrels per day, up 2.1% from the comparable period one year earlier.

Product Supplied Latest Week Four-Week Average Four-Week YoY Change
Total Petroleum Products 21.500M b/d 20.779M b/d +2.1%
Finished Motor Gasoline 8.689M b/d 8.721M b/d +0.3%
Distillate Fuel Oil 3.948M b/d 3.776M b/d +5.2%
Jet Fuel 1.809M b/d 1.761M b/d +6.5%

The strong year-over-year increase in four-week distillate product supplied is particularly relevant given the low level of distillate inventories.

Why Could WTI Rise Despite an Unexpected Crude Build?

Product Draws Were Much Larger Than Expected

Gasoline and distillate inventories both tightened materially more than consensus anticipated, providing a strong offset to the crude build.

Distillate Stocks Were Already Tight

Distillate inventories stood roughly 14% below their five-year seasonal average, increasing the information value of another 2.3M-barrel draw.

Total Commercial Stocks Declined

Aggregate petroleum stocks excluding the SPR fell by approximately 7M barrels despite the commercial crude build.

Refining Activity Fell

Lower refinery runs helped explain both the crude build and the simultaneous tightening in product inventories.

The Crude Headline Alone Was Insufficient

The September 30 release demonstrates why high-frequency petroleum analysis requires simultaneous processing of multiple fields.

A crude-only framework would have classified the release negatively: stocks built when the market expected a draw, and Cushing inventories also increased.

A broader balance-sheet framework would immediately have identified substantial tightening in gasoline and distillates, falling refinery runs and a seven-million-barrel decline in total commercial petroleum inventories.

Professional market takeaway: petroleum releases are multi-dimensional. The first price response can reflect the interaction among crude, products, Cushing, refinery runs, trade flows and demand indicators rather than the sign of any single inventory field.

Release-Window Reaction vs. the Broader Oil Session

The measured 24-tick WTI increase represents the immediate response around the scheduled EIA release.

It should be separated from the broader daily oil move.

Crude prices were already trading higher amid continued concerns over Middle Eastern supply, while tightening U.S. gasoline and distillate inventories added support following the EIA data.

WTI ultimately settled at approximately $90.42 per barrel, up about $1.04 on the session.

The distinction matters for event attribution: the release-window movement isolates the market's response to the new petroleum data, while the full-session price reflects a much broader information set.

Implications for Low-Latency Commodity Strategies

Process the Entire Petroleum Balance

Crude, gasoline, distillates and Cushing can deliver conflicting signals. A robust system needs to parse them concurrently rather than sequentially.

Compare Actual Data with Consensus

The absolute direction of a stock change is not sufficient. The magnitude of the deviation from market expectations determines how much new information the release contains.

Preserve Relationships Between Fields

Lower refinery runs helped explain why crude inventories increased while refined-product stocks declined. Treating each field independently can miss these balance-sheet relationships.

Separate Absolute Stocks from Weekly Changes

Commercial crude stocks were above their seasonal five-year average, while gasoline and distillates remained below theirs. Stock levels and weekly changes therefore provided different signals.

Distinguish Release-Window Movement from Daily Performance

HAAWKS measurements focus on the immediate market response surrounding the official publication. They are not intended to represent the direction or magnitude of the entire trading session.

HAAWKS Conclusion

The September 30 EIA petroleum release delivered a clear example of a mixed inventory report in which the crude headline did not determine the initial market direction.

Commercial crude inventories increased by 922,000 barrels against expectations for a 264,000-barrel draw.

Cushing stocks also increased by approximately 553,000 barrels.

Yet gasoline inventories fell by 1.7 million barrels and distillate inventories fell by 2.3 million barrels, both substantially exceeding expected draws.

Total commercial petroleum inventories excluding the SPR declined by approximately 7 million barrels, while refinery utilization fell to 92.5%.

HAAWKS measured an immediate 24-tick upward movement in WTI crude oil following the release.

For professional market participants, the release highlights the value of structured, low-latency access to the full petroleum data set. Crude inventories matter, but so do refined products, refinery activity, delivery-hub stocks, flows and implied demand.

Low-Latency Data. Structured Intelligence. Professional Execution.

Machine-Readable Data for Professional Markets

HAAWKS G4A provides low-latency, structured macroeconomic and commodity data covering the United States, Canada and Europe.

The feed is designed for systematic strategies, professional trading desks and latency-sensitive applications that require field-level economic and commodity data as official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Energy Information Administration — Weekly Petroleum Status Report, September 30, 2026
    Official source for U.S. crude, gasoline, distillate, refinery, supply, inventory and product-supplied data.
  2. Reuters — Oil Prices Rise on Tight Fuel Markets, September 30, 2026
    Used for analyst expectations and broader post-release oil-market context.
  3. Reuters via BOE Report — U.S. Crude Stocks Rise, Gasoline and Distillate Inventories Fall
    Used for consensus estimates, Cushing inventories and refinery utilization context.
  4. HAAWKS internal tick-level market analysis — September 30, 2026
    Source for the measured immediate 24-tick upward WTI crude oil movement.
Data note: Market expectations can vary between surveys and data providers. Consensus figures used above are identified separately from official EIA statistics. HAAWKS market-movement figures are internal release-window measurements.

Disclaimer: This material is provided for informational and research purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movement described is a historical measured market response and does not represent guaranteed or necessarily achievable trading profit. Tick values are instrument-specific. Actual execution depends on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

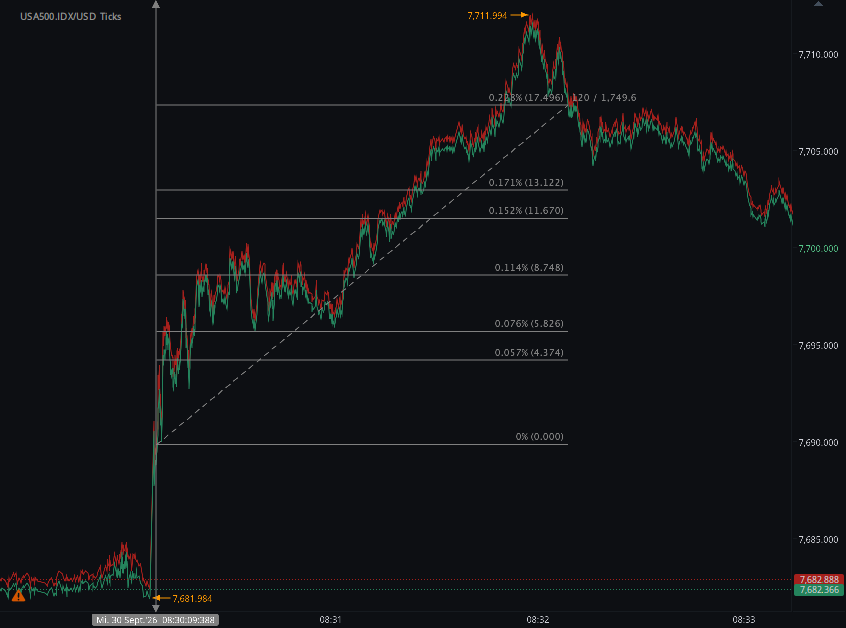
Softer PCE Inflation Sends US500 Up 68 Ticks as Dollar Weakens

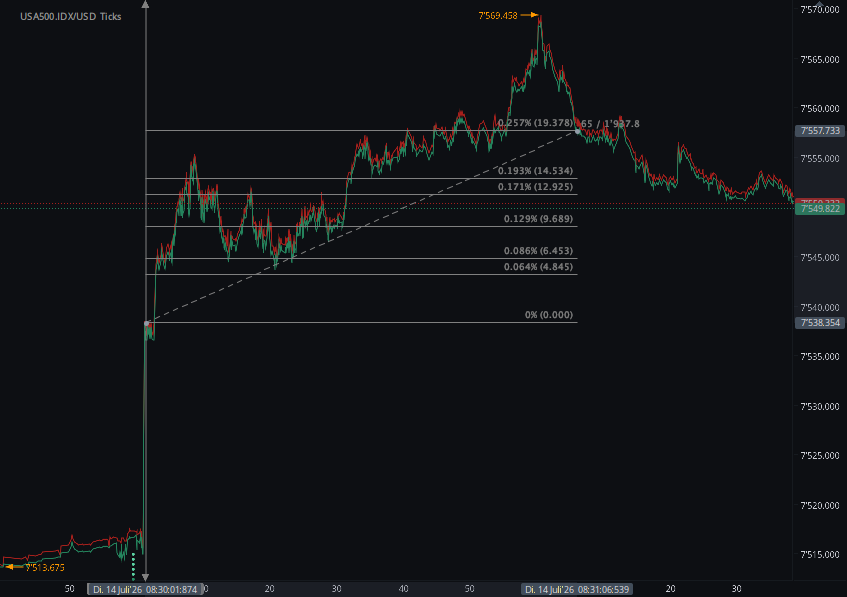
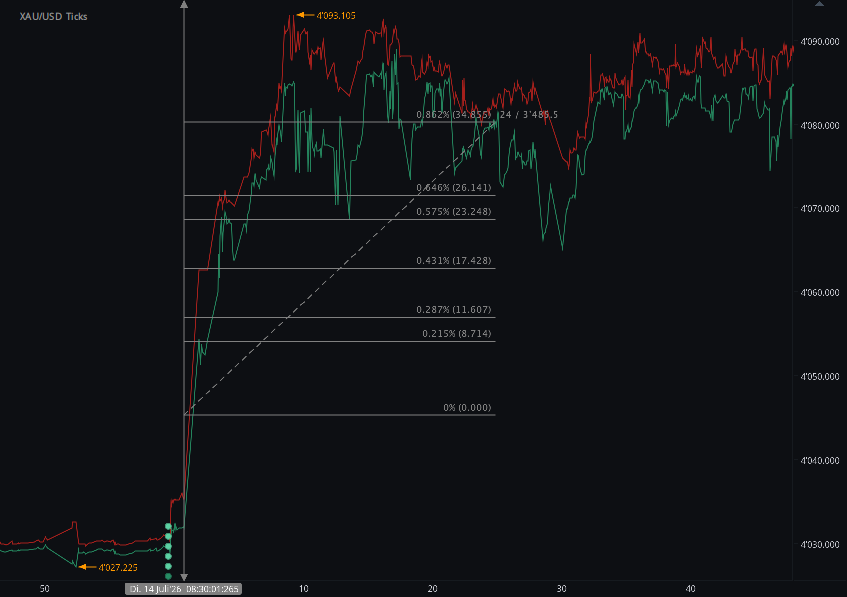
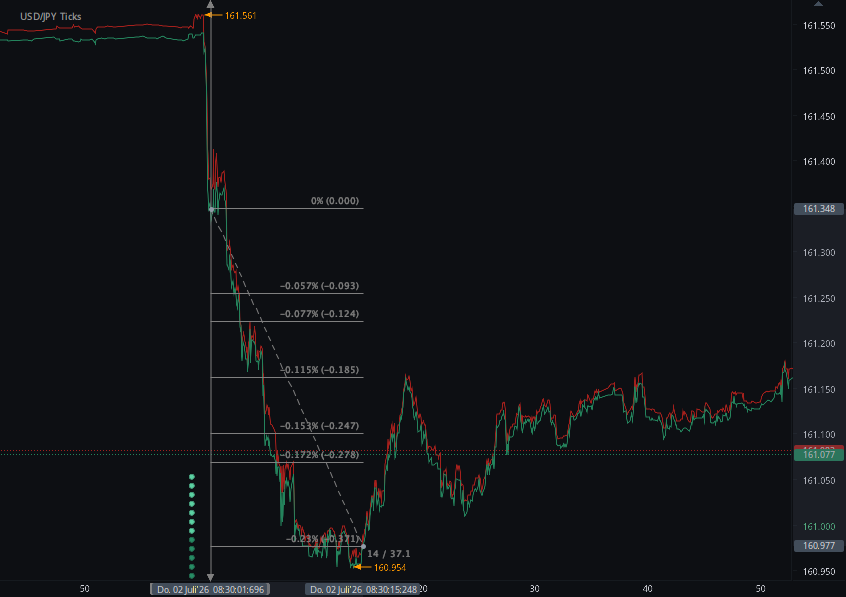
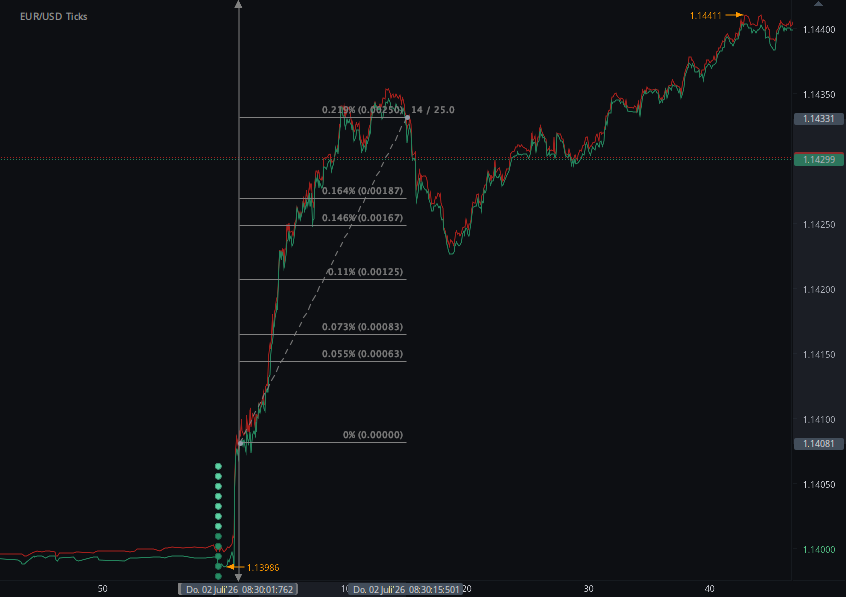
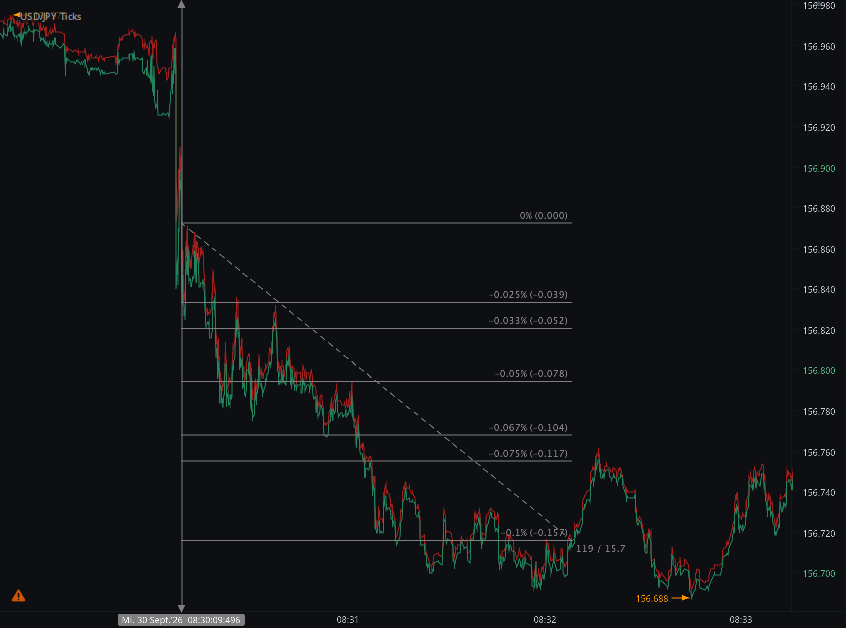
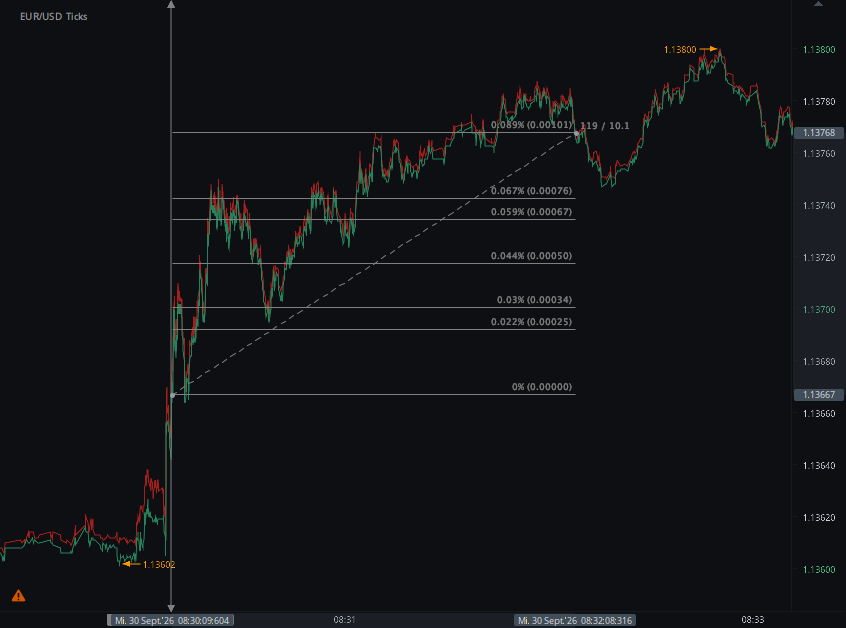
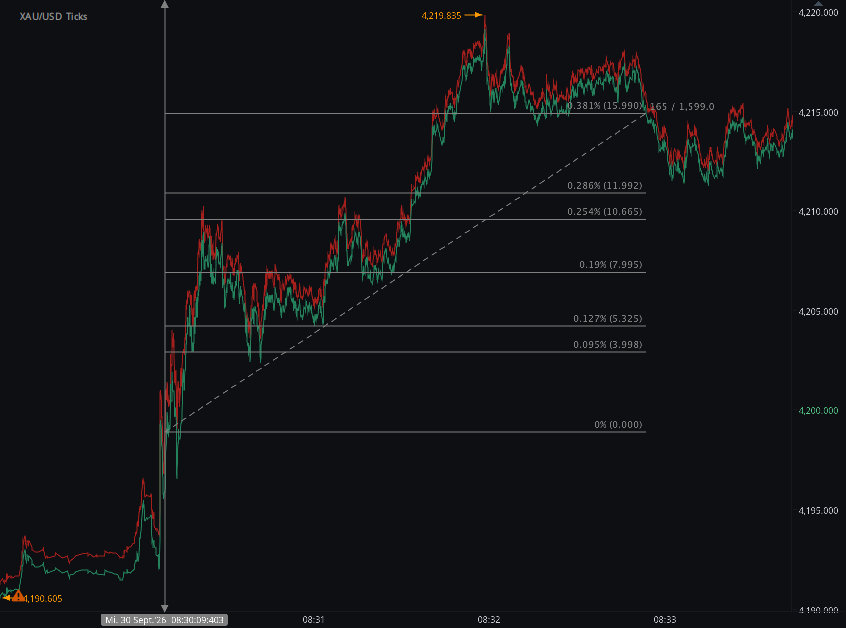
According to our analysis USDJPY moved 15 pips, EURUSD moved 10 pips, US500 moved 68 ticks and XAUUSD 15 points (93 ticks, gold 15 points total) on US BEA Personal Income and Outlays and US BEA Gross Domestic Production (GDP) data on 30 September 2026.

USDJPY (15 pips)

EURUSD (10 pips)

US500 (68 ticks)

XAUUSD (15 points)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Softer PCE Inflation Drives Dollar Lower as US500 and Gold Rally

August PCE inflation undershot expectations while the third estimate of second-quarter U.S. GDP was revised sharply higher. The simultaneous BEA releases produced an immediate cross-asset repricing in FX, equities and gold.

September 30, 2026 • Release time: 8:30 a.m. ET • BEA PCE & GDP

Two major U.S. macroeconomic releases hit institutional trading systems simultaneously at 8:30 a.m. ET on September 30: August Personal Income and Outlays, including the Federal Reserve's preferred PCE inflation measures, and the third estimate of second-quarter GDP.

The combined signal was unusual. Inflation was softer than expected, while economic growth was revised materially higher.

In the first minutes after the release, markets appeared to give greater weight to the inflation surprise and its implications for Federal Reserve policy.

HAAWKS measured an immediate 10-tick rise in EUR/USD, 15-tick decline in USD/JPY, 68-tick rise in US500 and 15-point rise in XAU/USD.

Institutional read-through: the cross-asset configuration — weaker USD, stronger equities and stronger gold — was consistent with a decline in near-term U.S. rate-hike expectations. The much stronger GDP revision provided an important counter-signal, but it did not dominate the initial release-window repricing.

Immediate Cross-Asset Reaction

EUR/USD +10 Ticks USD weaker
USD/JPY −15 Ticks USD weaker
US500 +68 Ticks Immediate equity rally
XAU/USD +15 Points Gold higher
Instrument HAAWKS Measured Move Direction Institutional Interpretation
EUR/USD 10 ticks Higher Broadly consistent with a softer U.S. dollar following the lower-than-expected PCE inflation readings.
USD/JPY 15 ticks Lower Reinforced the initial USD-negative interpretation across major FX pairs.
US500 68 ticks Higher Lower expected policy-rate pressure initially supported equity valuations.
XAU/USD 15 points Higher Gold benefited from the initial decline in U.S. rate expectations and dollar weakness.

August PCE: The Dominant Release-Window Signal

The principal inflation measures came in below market expectations. Headline PCE increased 0.3% month over month, compared with a Reuters consensus estimate of 0.4%.

On a year-over-year basis, headline PCE inflation was 3.4%, below the approximately 3.7% expected before the release.

Core PCE, which excludes food and energy and receives particular attention from Federal Reserve policymakers, rose 0.2% month over month and 3.0% year over year.

Headline PCE MoM +0.3% Reuters expectation: +0.4%
Headline PCE YoY 3.4% Reuters expectation: 3.7%
Core PCE MoM +0.2% Softer underlying inflation
Core PCE YoY 3.0% Revised inflation profile
HAAWKS view: for the first market reaction, the inflation surprise carried greater policy relevance than the backward-looking GDP revision. The combination of EUR/USD higher, USD/JPY lower, US500 higher and gold higher is consistent with the market initially reducing the probability of additional near-term Federal Reserve tightening.

An Important Institutional Caveat: The PCE Data Were Revised

The September 30 release was not a standard monthly update in isolation. It incorporated BEA's 2026 annual update of the National Economic Accounts, with revisions to personal income, spending and inflation estimates beginning in January 2021.

That distinction matters for systematic interpretation.

July headline PCE inflation was revised down to 0.1% month over month, while July core PCE was also revised to 0.1%.

Reuters reported that methodology changes affecting areas including portfolio-management services, software and legal services contributed materially to lower historical inflation readings.

Institutional implication: a low-latency model should distinguish a genuinely new monthly inflation surprise from revisions caused by annual benchmarking or methodology changes. Both can move markets, but they represent different information structures and may deserve different model weights.

The Consumer Remained Exceptionally Strong

The inflation data were softer, but the broader household data were not weak.

Nominal personal consumption expenditures increased 0.9% in August, equivalent to a $190.8 billion increase.

Inflation-adjusted real PCE increased 0.6%, indicating that the spending acceleration was not merely a function of higher prices.

Personal income increased only 0.2%, while disposable personal income increased 0.3%. Real disposable income was unchanged.

The personal saving rate declined to 4.1%, showing that the strength in consumption was accompanied by a lower share of disposable income being saved.

August Household Measure BEA Result Institutional Read-Through
Personal Income +0.2% Income growth remained positive but materially lagged consumption growth.
Disposable Personal Income +0.3% Moderate nominal household-income growth.
Real DPI 0.0% No monthly increase in inflation-adjusted disposable income.
Nominal PCE +0.9% Very strong consumer spending despite elevated borrowing costs.
Real PCE +0.6% Indicates genuine volume growth rather than only price effects.
Saving Rate 4.1% Household spending growth continued to outpace income growth.

GDP Delivered a Powerful Counter-Signal

At exactly the same 8:30 a.m. ET release time, BEA published its third estimate of second-quarter GDP.

Real GDP growth was revised sharply higher to an annualized 2.2%, compared with 1.5% in the second estimate.

The 0.7-percentage-point upward revision reflected stronger investment, consumer spending and government spending.

Q2 U.S. Measure Second Estimate Third Estimate Institutional Significance
Real GDP 1.5% 2.2% Material upward revision to aggregate economic growth.
Real Final Sales to Private Domestic Purchasers 4.2% 4.6% Strong underlying private domestic demand.
Real GDI 2.2% 2.6% Income-side measure also pointed to firmer activity.
Average of GDP and GDI 1.8% 2.4% Broader confirmation that Q2 activity was stronger than previously estimated.

Underlying Domestic Demand Was Stronger Than Headline GDP

For institutional macro investors, the composition of GDP may be more informative than the headline 2.2% figure.

Real final sales to private domestic purchasers — consumer spending plus private fixed investment — increased at a 4.6% annualized rate.

This measure removes several volatile components of GDP and provides a cleaner indication of underlying private domestic demand.

BEA attributed the Q2 GDP expansion to consumer spending, investment and exports, while increased imports subtracted from the headline calculation.

Among industries, the strongest contributors included real estate and rental and leasing, information, durable-goods manufacturing, and finance and insurance.

Corporate Profits Added to the Growth Signal

Profits from current production increased by $384.0 billion in the second quarter, although that figure was revised down by $16.9 billion from the previous estimate.

The combination of stronger consumer activity, investment and corporate earnings helps explain why the GDP release offered a distinctly growth-positive counterweight to the softer inflation figures.

Why the Inflation Signal Won the First Policy Repricing

Inflation Undershot Expectations

Headline monthly PCE rose 0.3% versus a 0.4% Reuters consensus, while the annual rate was 3.4% versus approximately 3.7% expected.

The Data Were Directly Relevant to the Fed

PCE inflation is the Federal Reserve's preferred consumer-inflation framework, making an inflation surprise immediately relevant to policy-rate pricing.

GDP Was Backward Looking

The 2.2% GDP figure described activity during April through June. The August PCE data provided more recent information about the inflation environment.

Growth Remained a Hawkish Counterweight

Strong consumption, a 4.6% increase in private domestic final sales and the GDP revision argue against interpreting the release as a simple growth slowdown.

Institutional takeaway: this was closer to a "soft inflation, strong demand" configuration than a straightforward dovish macro release. The first price response favored the inflation signal, but the underlying growth data remained too strong to justify treating the report as an unambiguously weak U.S. macro outcome.

Federal Reserve Expectations Repriced Lower

The immediate rates-market response reinforced the cross-asset signal.

Reuters reported that the implied probability of another Federal Reserve rate increase at the October meeting fell to approximately 41.5% after the data, from roughly 51.5% immediately beforehand.

U.S. Treasury yields initially declined and the dollar weakened, consistent with the HAAWKS FX, equity and gold observations.

That repricing did not eliminate the possibility of additional tightening. Inflation remained above the Federal Reserve's longer-run objective and household demand remained exceptionally resilient.

One Timestamp, Multiple Macro Signals

September 30 also illustrates a problem that matters directly to institutional news-trading infrastructure: multiple high-value data sets can be released at precisely the same timestamp.

At 8:30 a.m. ET, systems were required to process not merely one PCE figure but a large matrix of information including:

Data Family Examples of Relevant Fields Primary Market Channel
PCE Inflation Headline MoM, headline YoY, core MoM, core YoY Federal Reserve policy expectations
Household Income Personal income, disposable income, real DPI Household purchasing capacity
Consumer Spending Nominal PCE, real PCE, goods and services Current-quarter growth expectations
GDP Real GDP, final sales, investment, consumption Growth and policy outlook
GDI Real GDI and GDP/GDI average Confirmation of economic activity
Corporate Profits Current-production profits and industry measures Equity and growth fundamentals

Implications for Institutional News-Trading Systems

Field-Level Parsing Is Essential

A system reacting only to headline PCE could miss the interaction among core inflation, spending, income, GDP revisions and prior-period revisions.

Release Vintage Must Be Preserved

The 2026 annual update changed historical PCE and GDP estimates. Institutional research and systematic backtesting therefore need to distinguish the data available in real time from subsequently revised historical series.

Surprise Direction Is Not Enough

Softer inflation was dovish, while stronger GDP and spending were comparatively hawkish. A robust model needs to evaluate the magnitude, timeliness and policy relevance of competing surprises.

Cross-Asset Confirmation Adds Information

EUR/USD higher, USD/JPY lower, gold higher and equities higher provided a coherent initial cross-asset signal consistent with reduced near-term U.S. rate expectations.

Release-Window Movement Is Not Full-Session Performance

HAAWKS measurements isolate the immediate market response to the scheduled release. Subsequent price action incorporates liquidity, positioning, policy commentary and additional economic information.

Immediate Reaction vs. the Full Trading Session

The initial response should not be confused with the eventual daily close.

HAAWKS measured a strong 68-tick US500 increase during the release window, reflecting the first repricing of the new information.

The broader U.S. equity session subsequently became more mixed as investors continued to digest the strength of economic activity and elevated longer-term interest rates.

This distinction is central to institutional event analysis: release-window attribution asks a different question from end-of-day market attribution.

HAAWKS Conclusion

The September 30 BEA releases delivered one of the more complex U.S. macro combinations for systematic news traders: softer inflation alongside substantially stronger growth and exceptionally resilient consumer spending.

August headline PCE increased 0.3% month over month and 3.4% year over year, while core PCE increased 0.2% and 3.0%, respectively.

At the same time, second-quarter real GDP was revised from 1.5% to 2.2%, real final sales to private domestic purchasers increased 4.6%, and August nominal consumer spending surged 0.9%.

The market's initial interpretation nevertheless leaned toward the inflation side of the release.

HAAWKS measured EUR/USD +10 ticks, USD/JPY −15 ticks, US500 +68 ticks and XAU/USD +15 points in the immediate release window.

For institutional trading systems, the event demonstrates why a simultaneous macro release cannot be reduced to one headline field. Current values, consensus expectations, prior revisions, annual benchmarking, growth composition and cross-asset confirmation all need to be evaluated while the market is repricing.

Low-Latency Data. Structured Intelligence. Institutional Execution.

Low-Latency Macro Data for Institutional Markets

HAAWKS G4A provides structured, machine-readable macroeconomic and commodity data covering the United States, Canada and Europe.

The feed is designed for professional news-trading desks, systematic macro strategies and latency-sensitive applications that require field-level data immediately when official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Economic Analysis — Personal Income and Outlays, August 2026
    Official source for personal income, consumer spending, headline and core PCE inflation and the personal saving rate.
  2. U.S. Bureau of Economic Analysis — GDP Third Estimate, Industries and Corporate Profits, Second Quarter 2026
    Official source for real GDP, GDI, private domestic final sales, corporate profits and industry-level revisions.
  3. Reuters — U.S. Inflation Rises Less Than Expected in August
    Used for market consensus, Federal Reserve pricing and post-release rates and FX context.
  4. HAAWKS internal tick-chart analysis — September 30, 2026
    Source for the measured immediate release-window reactions: EUR/USD +10 ticks, USD/JPY −15 ticks, US500 +68 ticks and XAU/USD +15 points.
Data note: The September 30 releases incorporated BEA's 2026 annual update of the National Economic Accounts. Historical figures and prior-period readings may therefore differ from figures originally published in earlier release vintages. Quarterly GDP growth rates are seasonally adjusted annual rates and should not be directly compared with monthly or year-over-year PCE inflation rates without accounting for the different measurement basis.

Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The market movements described are historical measured release-window movements and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific and are not standardized measures of financial return. Actual trading results depend on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.
Comment

September 2026 WASDE: Corn Jumps 52 Ticks, Wheat 32 and Soybeans 28

Comment

September 2026 WASDE: Corn Jumps 52 Ticks, Wheat 32 and Soybeans 28

According to our analysis ZC moved 52 ticks, ZW moved 32 ticks and ZS moved 28 ticks (total: 112 ticks) on USDA World Agricultural Supply and Demand Estimates (WASDE) data on 11 September 2026.


HAAWKS Research

September WASDE Triggers Fast Grain Moves: Corn +52 Ticks, Wheat +32 and Soybeans +28

USDA cut the U.S. corn crop and tightened corn and soybean balances, while wheat delivered a more mixed global supply picture. CBOT grain futures reacted immediately to the 12:00 p.m. ET release.

September 11, 2026 • Release time: 12:00 p.m. ET • USDA WASDE

The September 2026 World Agricultural Supply and Demand Estimates produced rapid moves across the major CBOT grain markets as traders processed new USDA forecasts for corn, wheat and soybeans.

HAAWKS measured an immediate 52-tick rise in corn futures (ZC), a 32-tick rise in wheat futures (ZW) and a 28-tick rise in soybean futures (ZS) following the 12:00 p.m. ET release.

The report contained very different signals across the three crops. Corn supplies tightened substantially compared with USDA's August projections. Soybean production increased, but stronger export demand reduced projected ending stocks. U.S. wheat supply and use was largely unchanged, while the global wheat balance became looser.

HAAWKS first read: the initial futures reaction was higher across all three contracts, but the WASDE was not uniformly bullish relative to trade expectations. This is an important distinction for professional news traders: month-to-month USDA revisions and surprise versus consensus are two different signals.

Immediate Futures Market Reaction

CBOT Corn — ZC +52 Ticks Immediate HAAWKS release-window move
CBOT Wheat — ZW +32 Ticks Immediate HAAWKS release-window move
CBOT Soybeans — ZS +28 Ticks Immediate HAAWKS release-window move

Corn: USDA Cuts Yield, Production and Ending Stocks

Corn contained the clearest month-over-month tightening in the September report.

USDA reduced the 2026/27 national corn yield by 2.2 bushels per acre, from 180.7 to 178.5 bpa.

Production was cut by 213 million bushels to 15.800 billion bushels.

With lower beginning stocks and smaller production only partly offset by reduced feed demand, projected U.S. ending stocks fell from 1.653 billion to 1.567 billion bushels.

U.S. Corn August USDA Trade Average September USDA Interpretation
Yield 180.7 bpa 178.1 bpa 178.5 bpa Large cut vs. August, but slightly above consensus.
Production 16.013B bu 15.768B bu 15.800B bu 213M-bushel USDA cut, but slightly above the trade average.
2026/27 Ending Stocks 1.653B bu 1.533B bu 1.567B bu Tighter month over month, though not as tight as expected.
Season-Average Farm Price $4.50/bu — $4.80/bu USDA raised the price forecast by $0.30.
Corn takeaway: the balance sheet tightened substantially compared with August, which was supportive, but the headline yield, production and ending stocks figures were all slightly above pre-report trade averages. For a news trader, that makes the release more nuanced than simply calling the corn figures a bullish surprise.

Soybeans: Bigger Crop, but Stronger Exports Tighten Carryout

Soybeans delivered a mixed supply-and-demand signal.

USDA increased the soybean yield from 52.7 to 52.8 bushels per acre and raised production by 16 million bushels to a record 4.535 billion bushels.

That increase in supply was more than absorbed by stronger demand. USDA raised projected soybean exports by 25 million bushels to approximately 1.685 billion bushels.

As a result, projected ending stocks actually declined from 320 million to 310 million bushels.

U.S. Soybeans August USDA Trade Average September USDA Interpretation
Yield 52.7 bpa 52.5 bpa 52.8 bpa Higher than both August and the trade average.
Production 4.519B bu 4.492B bu 4.535B bu Larger crop than traders expected.
Exports 1.660B bu — 1.685B bu USDA raised exports by 25M bushels.
2026/27 Ending Stocks 320M bu 289M bu 310M bu Lower than August, but above the trade average.
Season-Average Farm Price $11.40/bu — $12.00/bu USDA raised its price projection by $0.60.

Wheat: U.S. Balance Unchanged, Global Supplies Rise

Wheat was arguably the most interesting market response because the underlying WASDE changes were less supportive than the immediate 32-tick upward move might suggest.

USDA left aggregate U.S. wheat supply and use unchanged. Production remained at 1.531 billion bushels and ending stocks remained at 717 million bushels.

USDA did make changes within wheat classes. White wheat exports were raised by 20 million bushels, while Hard Red Winter exports were reduced by 15 million and Hard Red Spring exports by 5 million.

The season-average wheat price was increased by $0.20 to $6.40 per bushel.

Globally, however, wheat supplies increased substantially. USDA raised production forecasts for Australia, Canada and Ukraine, while world ending stocks increased to approximately 276.3 million metric tons.

Wheat Measure August USDA Trade Average September USDA Interpretation
U.S. Production 1.531B bu — 1.531B bu Unchanged.
U.S. Ending Stocks 717M bu 720M bu 717M bu Slightly below the average trade estimate.
World Ending Stocks 273.3 MMT about 273.2 MMT 276.3 MMT The clearest bearish supply surprise among the three crops.
U.S. Farm Price $6.20/bu — $6.40/bu Raised by $0.20.
Wheat takeaway: the immediate 32-tick ZW rally should not be interpreted as proof that the WASDE itself was fundamentally bullish for wheat. Global wheat supplies and ending stocks increased, while the U.S. balance was essentially unchanged. Positioning, order flow and the interaction of multiple USDA data points can matter during the first seconds after a major agricultural release.

Global Ending Stocks: Another Layer for News Traders

The global balance sheets provided an important counterweight to the tighter U.S. corn and soybean figures.

2026/27 Global Ending Stocks August USDA Trade Estimate September USDA Signal vs. Consensus
Corn 274.7 MMT about 271.9 MMT 272.1 MMT Much tighter vs. August, but slightly above expectations.
Soybeans 124.2 MMT about 123.1 MMT 124.0 MMT Slightly tighter month over month, but above consensus.
Wheat 273.3 MMT about 273.2 MMT 276.3 MMT Significantly above expectations.

Why Can Futures Rally on a Mixed WASDE?

Algorithms Process Many Fields at Once

WASDE is not one number. Yield, production, exports, domestic use, ending stocks, global stocks and price forecasts arrive together. Different trading models may assign different weights to each field.

Month-over-Month Changes Matter

Corn production fell by 213M bushels from USDA's August estimate, while U.S. corn ending stocks declined by 86M bushels. Those are substantial directional changes even though the final figures were slightly above trade consensus.

Consensus Matters Too

Professional traders also compare the published figures with pre-report expectations. A number can tighten relative to last month and still be less bullish than traders anticipated.

Positioning Can Amplify the First Move

Futures prices reflect existing positions as well as fundamentals. Stop orders, hedging flows, spread positions and thin liquidity immediately after a release can amplify short-duration moves.

Immediate Reaction vs. the Rest of the Session

The HAAWKS measurements describe the immediate release-window reaction. They should not be confused with the direction of grain futures over the entire trading day.

HAAWKS recorded upward moves of 52 ticks in ZC, 32 ticks in ZW and 28 ticks in ZS following the USDA release.

Later in the session, grain markets reassessed the complete balance sheets. CME noted that corn and soybean futures ultimately finished the week lower, illustrating how an initial data-release move can differ from the subsequent market trend.

News-trader takeaway: release-window trading measures how prices respond when new information first enters the market. Later price action reflects additional interpretation, positioning, liquidity and broader market factors.

What the September WASDE Shows News Traders

WASDE Requires Multi-Field Parsing

Unlike a simple one-number economic release, WASDE contains hundreds of interconnected supply-and-demand fields. A professional system needs to identify which numbers changed and which differences matter most.

U.S. and Global Numbers Can Conflict

U.S. corn supplies tightened materially while world corn stocks still came in slightly above expectations. Wheat provided an even clearer example: U.S. ending stocks were slightly below the trade average, while world stocks were sharply above it.

Prior Estimates Are as Important as Consensus

Comparing September with August tells a trader how USDA changed its fundamental outlook. Comparing September with market expectations tells a trader how surprising the new information actually was.

Speed Alone Is Not Enough

Receiving the report quickly is valuable, but an automated system must also correctly map the crop, marketing year, country, unit and balance sheet field before acting.

Measured Movement Is Not Guaranteed Profit

The 52-, 32- and 28-tick figures represent historical measured price movement. Actual results depend on market depth, latency, spread, slippage, execution venue, order type and risk management.

HAAWKS Conclusion

The September 2026 WASDE triggered rapid price movement across all three major CBOT grain contracts monitored by HAAWKS.

HAAWKS measured approximately 52 ticks higher in corn futures, 32 ticks higher in wheat futures and 28 ticks higher in soybeans in the immediate release window.

Corn showed the clearest month-over-month tightening. USDA cut the national yield to 178.5 bpa, lowered production by 213 million bushels and reduced projected ending stocks to 1.567 billion bushels.

Soybean production increased to 4.535 billion bushels, but higher exports reduced ending stocks to 310 million bushels.

U.S. wheat supply and use was largely unchanged, while the global wheat balance became looser and world ending stocks rose to roughly 276.3 million metric tons.

The release therefore provides an important lesson for professional news traders: the initial price reaction cannot always be explained by one headline number or even by a simple bullish-versus-bearish label.

Low-latency access to structured USDA data allows trading systems to compare many fields simultaneously — current values, previous estimates, consensus expectations and global balances — while the market is still repricing.

Trade smart. Stay informed. Stay ahead.

Machine-Readable Data for Professional News Traders

HAAWKS G4A provides low-latency machine-readable U.S. macroeconomic and commodity data, together with macroeconomic data covering Canada and Europe.

Data is delivered via API access in Chicago, New York and London for professional and latency-sensitive news-trading applications.

Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. USDA — World Agricultural Supply and Demand Estimates, September 11, 2026
    Official source for U.S. and world corn, wheat and soybean supply-and-demand forecasts.
  2. USDA — WASDE Report
    Official WASDE publication page and release schedule.
  3. Price Futures Group — September 11 Grain Report
    Reproduces the pre-report analyst averages and ranges for U.S. production, yield and ending stocks used in this analysis.
  4. DTN — USDA Lowers Corn Yield 2.2 BPA, Slightly Increases Soy Yield
    Independent post-release analysis of the September WASDE and Crop Production reports.
  5. CME Group — Corn and Soybean Futures React to Latest WASDE Estimates
    Used for broader post-release grain-market context.
  6. HAAWKS internal tick-chart analysis — September 11, 2026
    Source for the measured immediate market reactions: ZC +52 ticks, ZW +32 ticks and ZS +28 ticks.
Data note: Pre-report market expectations can vary between surveys and data vendors. Figures identified as trade averages in this article are external consensus estimates, while USDA figures are official published data. HAAWKS market movements are internal release-window measurements.

Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick values are contract-specific. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.
Comment

Comment

August 2026 CPI: Hotter Core CPI Sends US500 Down 48 Ticks and Gold Down 19 Points

According to our analysis US500 moved 48 ticks and XAUUSD 19 points on US BLS Consumer Price Index (CPI) data on 11 September 2026.

US500 (48 ticks)

XAUUSD (19 points)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Hotter Core CPI Sends US500 Down 48 Ticks and Gold Down 19 Points

August U.S. inflation data delivered a hotter-than-expected core CPI reading, triggering an immediate hawkish repricing across equities, gold and interest-rate expectations.

September 11, 2026 • Release time: 8:30 a.m. ET • U.S. Consumer Price Index

The August 2026 U.S. Consumer Price Index delivered a mixed headline but a more important upside surprise in underlying inflation.

Headline CPI increased 0.4% month over month, in line with expectations, while the annual rate stood at 3.4%.

The more market-sensitive core measure increased 0.3% month over month, above the 0.2% consensus forecast. Core inflation was 2.4% year over year.

HAAWKS first read: the headline CPI result itself was not the key surprise. The immediate hawkish signal came primarily from the hotter 0.3% core CPI reading versus 0.2% expected. HAAWKS measured an initial 48-tick decline in US500 and 19-point decline in XAU/USD.

August CPI: Estimates vs. Actual

Headline CPI MoM +0.4% Expected: +0.4%
Headline CPI YoY 3.4% Expected: 3.4%
Core CPI MoM +0.3% Expected: +0.2%
Core CPI YoY 2.4% Expected: 2.4%
Inflation Measure Consensus Actual HAAWKS News-Trader Read
Headline CPI MoM +0.4% +0.4% Matched expectations and therefore provided little standalone surprise.
Headline CPI YoY 3.4% 3.4% Annual headline inflation remained elevated.
Core CPI MoM +0.2% +0.3% The key upside surprise and the most clearly hawkish element of the release.
Core CPI YoY 2.4% 2.4% Matched expectations.

Immediate Market Reaction

HAAWKS tick-chart analysis captured an immediate downside reaction in both US500 and gold following the 8:30 a.m. ET inflation release.

US500 −48 Ticks Immediate release-window decline
XAU/USD −19 Points Immediate release-window decline
Market Measured Move Direction News-Trader Interpretation
US500 48 ticks Lower The hotter core CPI increased expectations for tighter Federal Reserve policy, initially pressuring equities.
XAU/USD 19 points Lower Higher expected policy rates reduced the immediate appeal of non-yielding gold.

Why the Core CPI Number Mattered Most

For news traders, this release provides another example of why headline inflation cannot be read in isolation.

Headline CPI at 0.4% was in line with expectations. If that had been the only relevant data point, the inflation release would have contained relatively little immediate surprise.

Core CPI told a different story. Prices excluding food and energy rose 0.3% during August instead of the 0.2% economists had expected.

That difference strengthened the view that underlying inflation pressure remained persistent enough to influence Federal Reserve policy expectations.

HAAWKS view: the initial US500 and gold reaction was driven less by the headline CPI number, which broadly matched expectations, and more by the upside surprise in monthly core inflation and its implications for interest rates.

What Drove August Inflation?

CPI Component August MoM 12-Month Change HAAWKS Read-Through
All Items +0.4% +3.4% Headline monthly inflation accelerated.
Core CPI +0.3% +2.4% Monthly core inflation exceeded consensus.
Energy +2.1% +16.3% Energy remained an important source of headline inflation pressure.
Gasoline +3.9% +27.4% Gasoline accounted for more than one-third of the monthly increase in headline CPI.
Shelter +0.3% +3.0% Shelter accelerated from the previous month.
Food +0.1% +2.7% Food inflation remained comparatively moderate.
Services Less Energy Services +0.3% +3.0% Continued services inflation remained relevant to the underlying inflation picture.

Gasoline Drove Part of the Headline Increase

Energy prices were an important contributor to August inflation. The energy index increased 2.1% during the month.

Gasoline prices increased 3.9% and accounted for more than one-third of the monthly increase in the all-items CPI. Over the previous 12 months, gasoline prices increased 27.4%.

Fuel oil also increased sharply during the month, while other energy components were less inflationary.

Underlying Inflation Was Broader Than Energy

The core inflation increase was distributed across several categories, reinforcing the importance of looking beyond volatile energy prices.

Shelter increased 0.3%, while several transportation and service categories also recorded price increases.

This combination helped explain why the monthly core figure exceeded expectations despite some categories continuing to show weaker price pressure.

The Federal Reserve Repricing

The CPI report arrived shortly before the September Federal Reserve policy decision, increasing its significance for rate-sensitive markets.

Recent employment data had already demonstrated stronger labor-market conditions. The hotter core CPI figure added another argument for maintaining tighter monetary policy.

Core CPI Beat Expectations

A 0.3% monthly increase compared with 0.2% expected was the clearest hawkish surprise in the report.

Energy Inflation Accelerated

Energy increased 2.1%, with gasoline up 3.9%, keeping headline inflation pressure elevated.

Shelter Increased 0.3%

Shelter remained an important component of underlying consumer inflation.

Policy Expectations Changed

The combination of stronger employment data and firmer core inflation reinforced expectations for restrictive monetary policy.

Immediate Reaction vs. the Rest of the Trading Session

News traders should distinguish the immediate release-window response from subsequent full-session market performance.

HAAWKS measured an initial 48-tick decline in US500 and a 19-point decline in XAU/USD around the CPI release.

Markets can subsequently retrace or reverse these initial moves as liquidity normalizes, traders reassess individual components and additional market information enters prices.

News-trader takeaway: release-window analysis measures the market's first response to new information. It should not be confused with the direction or size of the move over the entire trading session.

What This CPI Release Shows News Traders

Actual vs. Consensus Is the Primary Signal

Headline CPI at 0.4% carried limited surprise because it matched expectations. Core CPI at 0.3% mattered because the market had expected only 0.2%.

Headline and Core CPI Can Send Different Signals

A professional news-trading system should distinguish all-items CPI from the core measure. Each field can have a different surprise magnitude and a different effect on interest-rate expectations.

Component Data Adds Context

Gasoline, energy, shelter and service-price components help traders understand whether inflation pressure is concentrated in volatile categories or is becoming more broadly distributed.

Cross-Asset Confirmation Matters

The initial simultaneous declines in US500 and gold were consistent with a more hawkish interpretation of the inflation data.

Measured Movement Is Not Guaranteed Profit

The 48-tick US500 and 19-point XAU/USD moves represent measured historical price movement. Actual execution can differ materially due to latency, spreads, liquidity, slippage, order type and execution venue.

HAAWKS Conclusion

The August CPI report delivered a more nuanced result than the headline number alone suggested.

Headline CPI increased 0.4%, broadly matching market expectations, while annual inflation stood at 3.4%.

The key market-moving surprise was core CPI, which increased 0.3% month over month against expectations for 0.2%.

Energy also accelerated, with gasoline increasing 3.9%, while shelter prices rose 0.3%.

HAAWKS measured an immediate 48-tick decline in US500 and 19-point decline in XAU/USD following the release.

For professional news traders, the release demonstrates why receiving only the headline CPI figure is not enough. Headline CPI, core CPI, expectations and individual components need to be processed together to identify the actual surprise and understand the market's initial interpretation.

Trade smart. Stay informed. Stay ahead.

Built for Professional News Traders

HAAWKS G4A provides low-latency machine-readable data for U.S. macroeconomic and commodity releases, together with macroeconomic data from Norway, Sweden, Switzerland and Turkey, as well as ECB interest-rate decisions and statements.

All data is machine readable and available via API access in Chicago, New York and London. Free trials are available for qualified professionals.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Labor Statistics — Consumer Price Index, August 2026
    Official source for headline CPI, core CPI and detailed inflation components.
  2. HAAWKS internal tick-chart analysis — September 11, 2026
    Source for the measured immediate release-window movements of 48 ticks in US500 and 19 points in XAU/USD.
Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific measures and should not be treated as standardized financial returns. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.
Comment

Comment

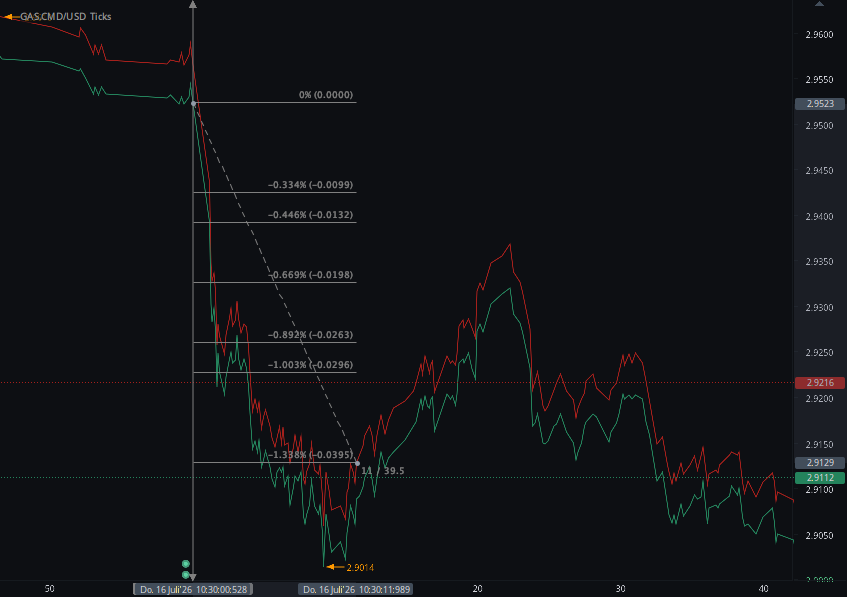
EIA Petroleum Report Sends WTI Crude Oil Down 30 Ticks

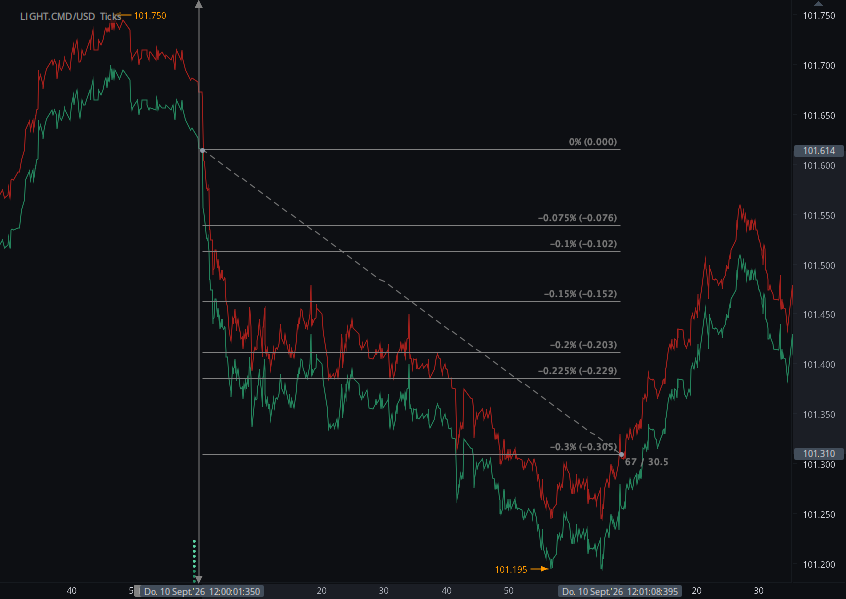
According to our analysis crude oil moved 39 ticks on DOE Weekly Petroleum Status Report (WPSR) data on 10 September 2026.

WTI crude oil (30 ticks)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Early EIA Petroleum Data Sends WTI Crude Oil Down 30 Ticks

The market reacted to EIA's early Weekly Petroleum Status Report data before publication of the full report, as a smaller-than-expected crude draw and surprise gasoline and distillate builds delivered a bearish inventory signal.

September 10, 2026 • Early release: 12:00 p.m. ET • WTI Crude Oil

On September 10, 2026, WTI crude oil reacted immediately when the first EIA Weekly Petroleum Status Report data became available at 12:00 p.m. ET — before publication of the complete report later in the day.

The early EIA overview and petroleum tables already contained the high-value fields news traders needed to assess the release: commercial crude stocks, gasoline, distillates, Cushing inventories, refinery inputs and utilization, production, imports, exports and product supplied.

Commercial crude stocks declined by only 391,000 barrels, substantially less than the approximately 1.55 million-barrel draw expected in a Reuters analyst survey.

At the same time, gasoline and distillate inventories unexpectedly increased, reinforcing the initial bearish interpretation.

HAAWKS release-window analysis: the early petroleum data triggered approximately 30 ticks of downside movement in WTI crude oil. The price reaction occurred before traders needed to wait for the complete WPSR PDF and HTML publication.

Why the Early EIA Release Matters to News Traders

The important distinction: EIA does not require traders to wait for the complete Weekly Petroleum Status Report before key petroleum statistics become available.

The early release includes the WPSR summary, overview and core statistical tables. The remaining full-report PDF and HTML material is published later.

For traditional analysis, waiting for the complete report may make little difference. For latency-sensitive news trading, however, the distinction is critical.

The market can begin repricing as soon as the key inventory and supply fields become public. By the time a trader manually opens and reads the complete report, part of the initial market reaction may already have taken place.

HAAWKS view: for WPSR news trading, the relevant event is the first public dissemination of the market-moving data — not the later appearance of the full formatted report.

Key Inventory Surprises at 12:00 p.m. ET

Commercial Crude −0.391M Reuters estimate: −1.55M barrels
Gasoline +1.269M StreetInsider estimate: −1.09M
Distillates +2.087M StreetInsider estimate: −0.632M
Cushing −0.684M WTI delivery hub
Inventory Field Market Estimate Actual Surprise News-Trader Read
Commercial Crude Oil −1.55M
Reuters survey
−0.391M Smaller draw Bearish relative to expectations despite the negative headline inventory change.
Gasoline −1.09M
StreetInsider estimate
+1.269M Build vs. expected draw A large bearish swing relative to expectations.
Distillates −0.632M
StreetInsider estimate
+2.087M Build vs. expected draw Another clear bearish product-inventory surprise.
Cushing, Oklahoma — −0.684M Draw A bullish counter-signal because Cushing is the delivery point for NYMEX WTI futures.

WTI Falls 30 Ticks on the Early Data

HAAWKS tick-chart analysis recorded an immediate downside reaction as the petroleum figures entered the market.

30 WTI Crude Oil Ticks Lower

HAAWKS measured the move following the 12:00 p.m. ET early EIA petroleum-data release on September 10, 2026.

The reaction illustrates an important principle in petroleum news trading: a negative crude-stock number is not automatically bullish.

What matters is the difference between the actual data and what the market had already priced in.

Traders expected a materially larger crude draw. Instead, inventories fell by only 391,000 barrels. Gasoline and distillates simultaneously moved in the opposite direction from expectations and posted inventory builds.

What Was Already Available in the Early Overview?

The early EIA overview contained considerably more information than the three headline inventory figures.

Early-Release Data Point Current Week Previous Week Change / Context
Commercial Crude Stocks 424.1M barrels 424.5M barrels Approximately −0.4M barrels
Cushing Crude Stocks 21.8M barrels 22.5M barrels Approximately −0.7M barrels
Gasoline Stocks 206.9M barrels 205.7M barrels Approximately +1.3M barrels
Distillate Stocks 106.3M barrels 104.2M barrels Approximately +2.1M barrels
Total Commercial Petroleum Stocks Ex-SPR 1,248.6M barrels 1,242.3M barrels +6.3M barrels
Refinery Crude Inputs 17.586M b/d 17.496M b/d +91K b/d
Refinery Utilization 97.8% 98.0% Refineries remained near very high utilization levels.
U.S. Crude Production 13.947M b/d 13.862M b/d +85K b/d

In other words, a news-trading system did not need the later full report to know that crude inventories disappointed expectations, product inventories built, Cushing drew, refinery utilization remained very high and U.S. crude production increased.

Imports, Exports and Supply Added More Context

The early overview also showed a material change in crude trade flows.

Crude Supply Measure Current Week Previous Week Weekly Change
Crude Imports 6.824M b/d 6.770M b/d +53K b/d
Crude Exports 3.417M b/d 4.483M b/d −1.066M b/d
Net Crude Imports 3.407M b/d 2.287M b/d +1.119M b/d

The large decline in crude exports and increase in net imports helped explain why domestic commercial crude stocks registered only a small draw despite exceptionally high refinery runs.

Demand Indicators Were Also Available Before the Full Report

The overview included product-supplied statistics, giving news traders an immediate view of implied petroleum demand.

Product Supplied Latest Week Four-Week Average Four-Week YoY
Total Products 19.313M b/d 20.119M b/d −3.7%
Finished Motor Gasoline 8.551M b/d 8.801M b/d −1.4%
Distillate Fuel Oil 3.678M b/d 3.715M b/d −2.6%
Jet Fuel 1.785M b/d 1.731M b/d −2.3%

Why the Initial WTI Signal Was Bearish

Crude Drew Less Than Expected

The market expected a substantially larger decline in commercial crude stocks. A 391K draw was therefore bearish relative to the consensus expectation despite being a draw in absolute terms.

Gasoline Swung to a Build

Gasoline inventories increased by approximately 1.27M barrels versus expectations for a decline. That created one of the clearest bearish surprises in the early data.

Distillates Also Built

Distillate inventories increased by approximately 2.09M barrels rather than posting the expected draw, reinforcing the product-side bearish signal.

Total Commercial Stocks Rose

Total commercial petroleum inventories excluding the Strategic Petroleum Reserve increased by 6.3M barrels during the week, providing broader evidence of inventory accumulation.

But the Release Was Not Bearish in Every Detail

Professional news traders also had to process several opposing signals.

Cushing inventories fell by approximately 684,000 barrels, which was supportive for WTI because Cushing is the NYMEX crude futures delivery point.

Refineries were also operating at a very high 97.8% utilization rate, with crude inputs of 17.586 million barrels per day.

Meanwhile, early EIA summary information showed gasoline and distillate inventories still below their respective five-year seasonal averages despite the week's builds.

HAAWKS view: the dominant immediate surprise was bearish because crude missed the expected draw and both major refined-product categories built. However, the Cushing draw and historically tight product inventories provided counter-signals that a complete trading model should not ignore.

What This Release Shows Professional News Traders

The Market Does Not Wait for the Full PDF

The key trading information was already public in the early overview, summary and statistical tables. The later complete report added presentation and additional context, but the principal inventory surprises were already available to the market.

Machine-Readable Fields Matter

A WPSR strategy may need to process crude inventories, Cushing stocks, gasoline, distillates, production, refinery utilization, imports, exports and product supplied at virtually the same time.

Consensus Is Essential

A crude draw is not automatically bullish. The 391K decline was bearish relative to expectations because traders had positioned for a much larger draw.

Different Fields Can Conflict

National crude and product inventories produced a bearish initial signal, while Cushing inventories produced a bullish one. News traders need rules for weighting conflicting data rather than reacting to only one field.

Low Latency Is About the First Public Data

For latency-sensitive trading, the relevant workflow begins when the earliest official data become available. Waiting for a later formatted report can mean waiting until after the first market repricing has already occurred.

The 30-Tick Reaction Was Not the Full-Day Oil Story

HAAWKS measured approximately 30 ticks of downside WTI movement in response to the early EIA data.

That should be separated from the broader September 10 oil session. Global crude prices were simultaneously being driven by severe geopolitical supply risks.

WTI ultimately settled above $100 per barrel and rose more than 6% on the day as attacks on shipping and Middle Eastern energy infrastructure increased concerns about global supply disruptions.

News-trading distinction: a release-window move measures the immediate repricing caused by a specific data event. It does not necessarily predict the direction of the market for the remainder of the trading session.

HAAWKS Conclusion

The September 10 EIA release provides a useful example of why publication timing matters for professional news traders.

The market-moving petroleum data were available at 12:00 p.m. ET, before publication of the complete Weekly Petroleum Status Report.

Commercial crude stocks declined by 391,000 barrels, considerably less than expected. Gasoline inventories increased by 1.269 million barrels, while distillate stocks rose by 2.087 million barrels.

Total commercial petroleum stocks excluding the SPR increased by 6.3 million barrels, while Cushing crude stocks provided a counter-signal with a roughly 684,000-barrel draw.

HAAWKS measured approximately 30 ticks of immediate downside movement in WTI crude oil following the early release.

For professional news traders, the lesson is straightforward: the trading event begins when the first official machine-readable information enters the market — not when the complete report becomes convenient to read manually.

Trade smart. Stay informed. Stay ahead.

Low-Latency Data for Professional News Traders

HAAWKS G4A provides low-latency machine-readable U.S. macroeconomic and commodity data, together with macroeconomic data covering Canada and Europe.

Data is delivered in structured machine-readable format via API access in Chicago, New York and London, supporting professional and latency-sensitive automated news-trading applications.

Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Energy Information Administration — Weekly Petroleum Status Report
    Official EIA source for the September 10, 2026 petroleum data covering the week ending September 4.
  2. EIA — Weekly Petroleum Status Report Release Schedule
    EIA publication schedule explaining the earlier release of the WPSR summary, overview and core tables ahead of the remaining full-report PDF and HTML files.
  3. Reuters — September 10, 2026 Oil Market Report
    Source for the Reuters analyst expectation of a 1.55M-barrel crude draw and broader oil-market context.
  4. StreetInsider — EIA Inventory Release, September 10, 2026
    Timestamped at 12:00 p.m. EDT and used for the product inventory consensus estimates: gasoline −1.09M barrels and distillates −0.632M barrels.
  5. HAAWKS internal tick-chart analysis — September 10, 2026
    Source for the measured immediate 30-tick WTI crude oil reaction.
Data note: Market consensus estimates can vary between surveys and data vendors. Estimates in this article identify their source where appropriate. EIA figures are official reported values, while HAAWKS market-reaction measurements are based on internal tick-chart analysis.

Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movement described is a historical measured market reaction and does not represent guaranteed or necessarily achievable trading profit. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.
Comment

Comment

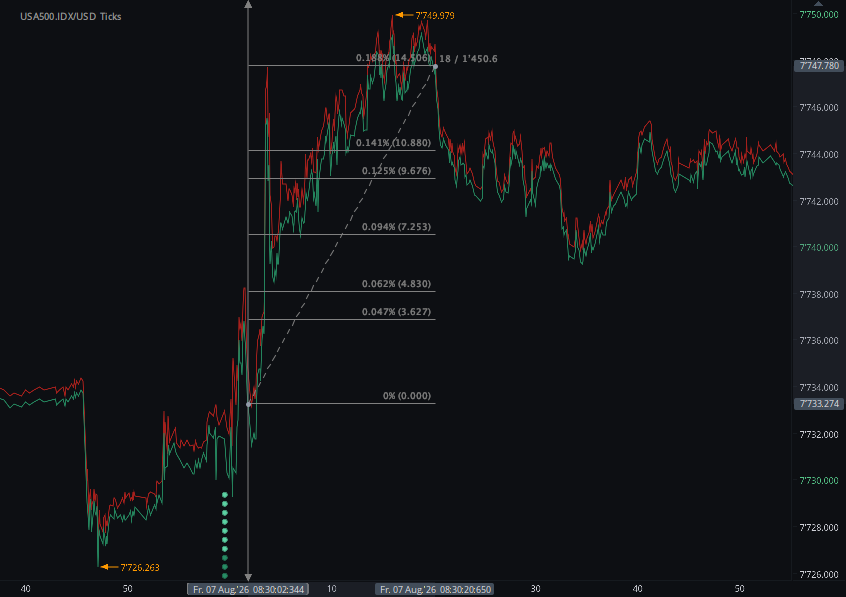
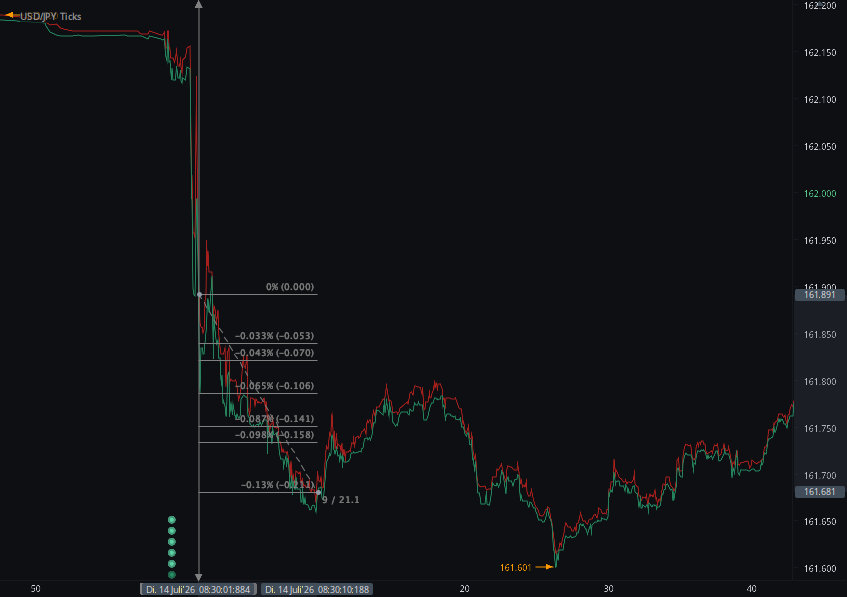
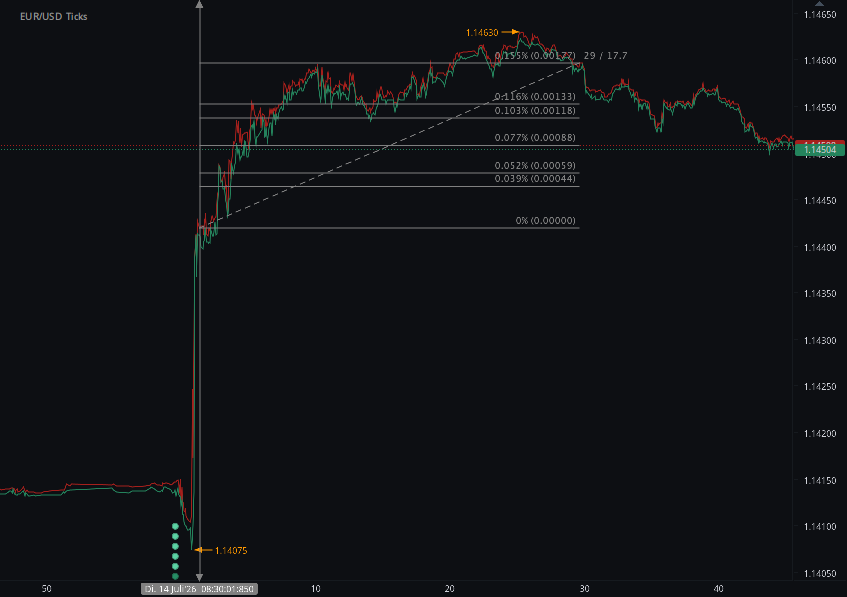
July 2026 NFP Shock: 23K Job Loss Triggers Sharp Moves in FX, Gold and US500

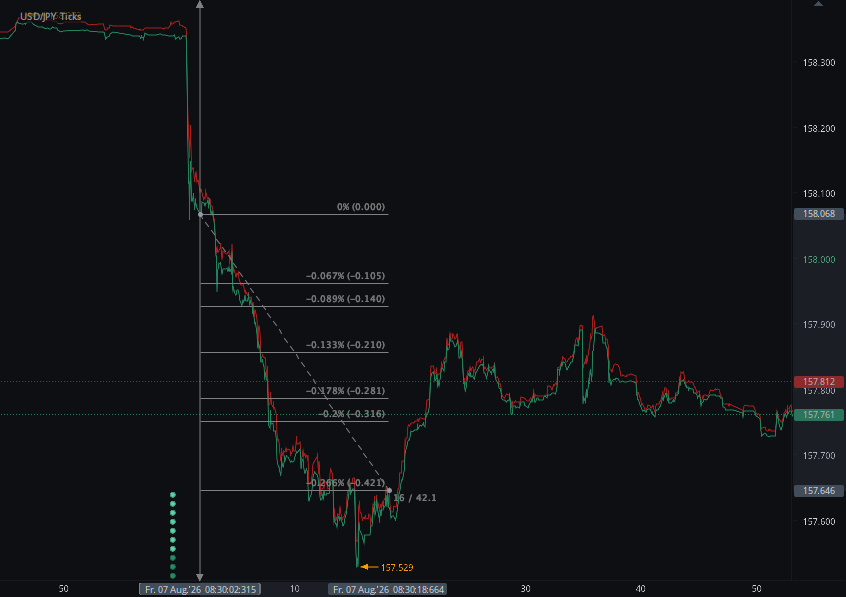
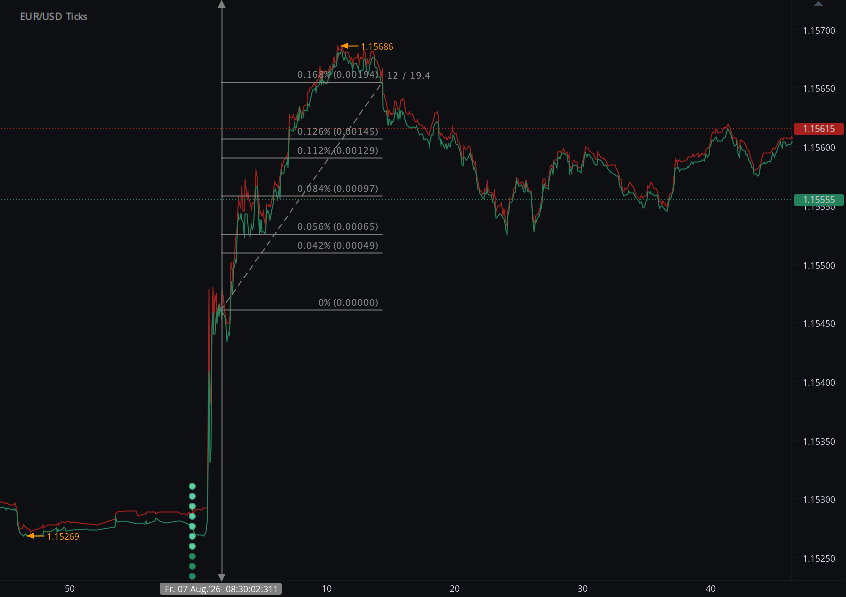
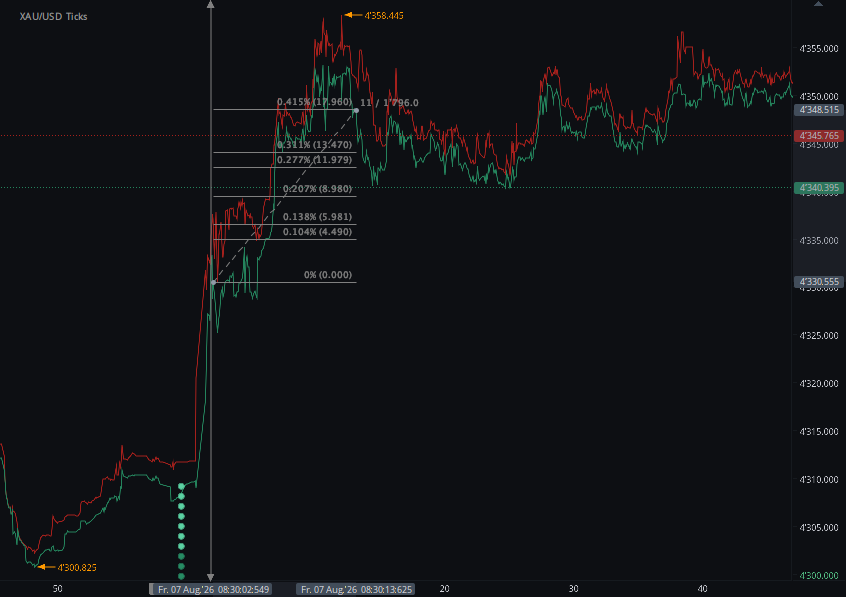
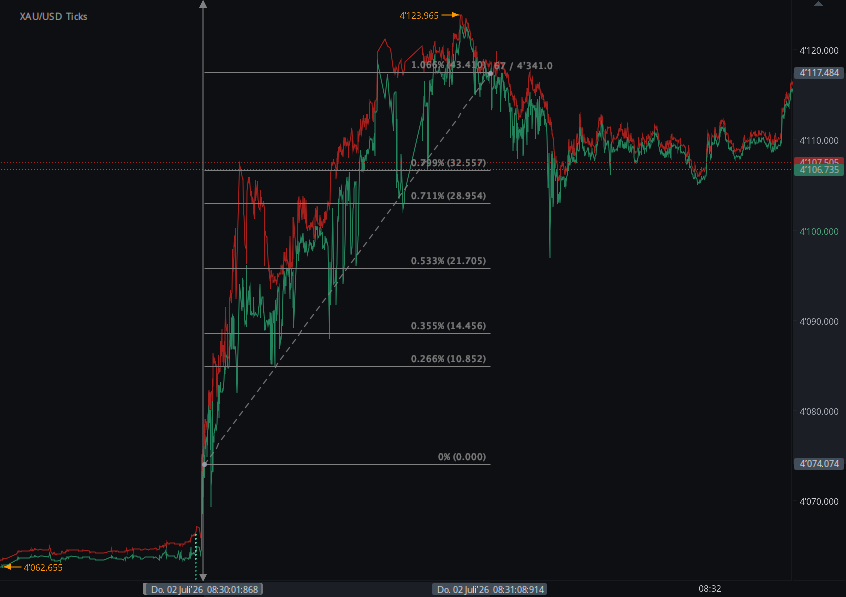
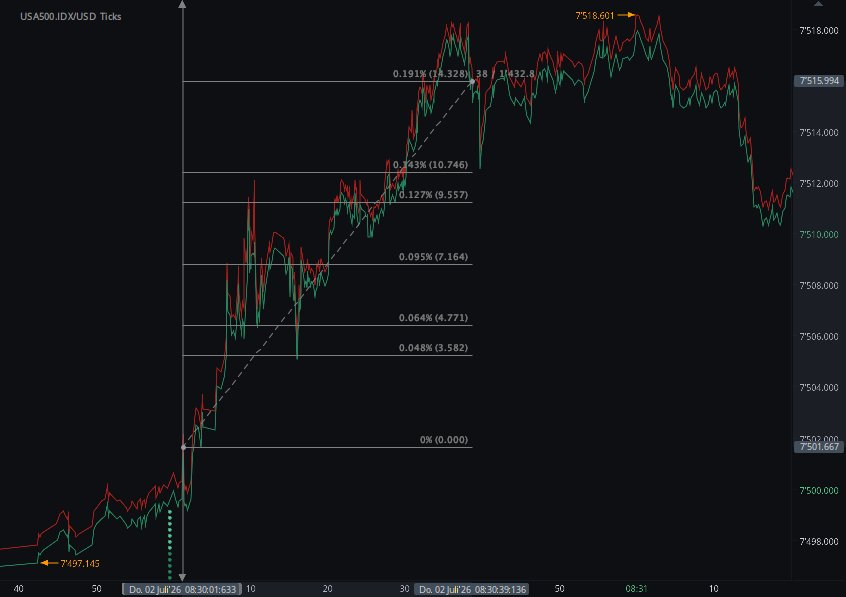
According to our analysis USDJPY moved 42 pips, EURUSD moved 19 pips, XAUUSD (spot gold) moved 17 points and US500 moved 56 ticks (117 ticks total) on US Employment Situation (Non-farm payrolls / NFP) data on 7 August 2026.

USDJPY (42 pips)

EURUSD (19 pips)

XAUUSD (17 points)

US500 (56 ticks)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

July 2026 NFP Shock: Payrolls Fall 23K as Markets Reprice the Fed

A surprise contraction in U.S. payrolls, weaker wage growth and another round of large downward revisions triggered rapid moves across FX, gold and U.S. equity indices.

August 7, 2026 • Release time: 8:30 a.m. ET • U.S. Employment Situation

The July 2026 U.S. Employment Situation delivered a significantly weaker labor-market signal than news traders had expected. Nonfarm payrolls declined by 23,000, compared with a Reuters consensus forecast for an 80,000 increase.

The unemployment rate fell from 4.2% to 4.1%, but the improvement in the headline rate came alongside another decline in labor force participation. The participation rate slipped to 61.4%, while the civilian labor force contracted by 264,000.

For news traders, the details behind the headline were arguably even more important. May and June payroll growth was revised lower by a combined 103,000 jobs, while annual average hourly earnings growth slowed to 3.2%.

HAAWKS first read: this was not simply a weak headline NFP print. The combination of a 103,000-job downside surprise versus consensus, substantial prior-month revisions, softer wage growth and weaker labor-force participation produced a distinctly dovish labor-market signal.

NFP Estimates vs. Actual Release

Nonfarm Payrolls −23K Reuters consensus: +80K
Unemployment Rate 4.1% Forecast: 4.2%
Wage Growth YoY 3.2% Forecast: 3.5%
Prior Revisions −103K May + June combined
July 2026 U.S. Employment Situation estimates compared with actual results
Labor Indicator Expectation Actual HAAWKS News-Trader Read
Nonfarm Payrolls +80K −23K A 103K downside surprise versus consensus and the primary negative headline for the dollar.
Unemployment Rate 4.2% 4.1% Better on the surface, but less supportive once the decline in labor-force participation was taken into account.
Average Hourly Earnings YoY 3.5% 3.2% Softer wage pressure reinforced the dovish interpretation of the employment report.
Labor Force Participation — 61.4% Participation edged down from 61.5%, helping explain why the unemployment rate fell despite weak employment conditions.
May Payroll Revision Previous: +129K +63K Revised lower by 66K.
June Payroll Revision Previous: +57K +20K Revised lower by 37K.

Immediate Market Reaction

The HAAWKS release-window measurements show how quickly the labor-market surprise was incorporated into prices. The initial response was consistent across the major macro markets: the U.S. dollar weakened, gold rallied and U.S. equities moved higher as traders reduced expectations for near-term Federal Reserve tightening.

USD/JPY −42.1 pips 16 seconds
EUR/USD +19.4 pips 12 seconds
XAU/USD +17.96 points 11 seconds
US500 +14.6 points 18 seconds
Immediate market reaction following the July 2026 NFP release
Market Measured Move Time Window Direction News-Trader Interpretation
USD/JPY 42.1 pips 16 seconds Lower The strongest measured FX reaction as the weak employment figures triggered rapid dollar selling against the yen.
EUR/USD 19.4 pips 12 seconds Higher Broad dollar weakness pushed the euro higher immediately after the release.
XAU/USD 17.96 points 11 seconds Higher Gold reacted quickly to lower yields, dollar weakness and a reduction in expected Federal Reserve tightening.
US500 14.6 index points 18 seconds Higher Equity traders initially focused on the lower-rate implications of the employment miss rather than the negative growth signal.

Why This Release Mattered to News Traders

1. The Headline Surprise Was Large

Payrolls were expected to rise by 80,000 but instead declined by 23,000. For automated and discretionary news traders, the 103,000-job gap versus consensus immediately changed the macro interpretation of the release.

2. Revisions Reinforced the Signal

May and June were revised down by a combined 103,000 jobs. That mattered because the release did not just report a weak July; it also showed that the preceding labor-market picture had been weaker than initially reported.

3. Unemployment Sent a Mixed Message

A fall in unemployment to 4.1% would ordinarily be interpreted as labor-market strength. However, the labor force shrank and participation slipped to 61.4%, reducing the positive impact of the headline unemployment rate.

4. Wage Growth Also Missed

Annual average hourly earnings growth slowed to 3.2% versus the 3.5% rate economists had expected. For rate-sensitive markets, softer wages added another dovish element to an already weak payroll report.

HAAWKS view: for news traders, this was a release where the components largely pointed in the same direction. The headline payroll miss, negative revisions and softer wage growth outweighed the lower unemployment rate. The result was a fast cross-asset repricing: USD lower, gold higher and equities higher.

Sector Detail: Where the Jobs Were Lost

The weakness was not evenly distributed across the economy. Local government education employment declined by 50,000, while retail trade lost 19,000 jobs. Financial activities employment continued to trend lower, falling by 14,000.

Health care remained one of the few areas of continued employment growth, adding 22,000 jobs during July, although that was slower than its average monthly gain over the previous year.

Selected July 2026 employment changes by industry
Industry July Change HAAWKS Read-through
Local Government Education −50K The largest highlighted sector decline in the July report.
Retail Trade −19K Added to the evidence of weaker overall hiring momentum.
Financial Activities −14K Continued an existing downward employment trend.
Health Care +22K Continued to add jobs, but at a slower pace than its prior 12-month average.

The Fed Repricing

Before the release, markets were debating whether persistent inflation could lead the Federal Reserve to raise rates at its September meeting. The unexpectedly weak jobs report materially reduced that probability.

That shift helps explain why assets that normally benefit from lower interest-rate expectations reacted so quickly. Treasury yields fell, the U.S. dollar weakened, gold advanced and U.S. stock futures initially rallied.

For news traders, the key point is that the market was not trading the payroll number in isolation. It was trading how the employment surprise changed the expected path of monetary policy.

News Trading Takeaways

Headline Data Is Only the First Layer

A fast NFP strategy must be able to process more than the payroll headline. Unemployment, wage growth and revisions can either confirm or contradict the initial signal.

Revisions Can Be Market-Moving

The 103,000 combined downward revision to May and June strengthened the bearish labor-market message. In some releases, prior-period revisions can matter as much as the current month's number.

Cross-Asset Confirmation Matters

USD/JPY lower, EUR/USD higher, gold higher and US500 higher represented a coherent initial macro reaction. When several rate-sensitive markets respond in the same direction, news traders receive useful confirmation of the market's interpretation.

Execution Risk Remains Critical

A measured market move is not the same as an achievable trading result. During high-impact releases, spreads can widen, liquidity can disappear, prices can gap and slippage can increase. Latency, order type, venue and risk controls remain critical to actual execution.

HAAWKS Conclusion

The July 2026 NFP release delivered a much weaker labor-market picture than traders had expected.

Nonfarm payrolls declined by 23,000 versus expectations for an 80,000 increase. May and June were revised down by another 103,000 jobs, while annual wage growth slowed to 3.2%.

Although unemployment fell to 4.1%, declining labor-force participation reduced the strength of that signal. The broader message from the report was therefore clearly softer than the headline unemployment rate alone suggested.

The immediate market reaction reflected that interpretation. HAAWKS measured 42.1 pips in USD/JPY in 16 seconds, 19.4 pips in EUR/USD in 12 seconds, 17.96 points in XAU/USD in 11 seconds and 14.6 index points in US500 in 18 seconds.

For news traders, the release is a useful example of why low-latency access to the complete data set matters. The payroll headline, unemployment rate, wage figures and revisions all arrived together and collectively determined the market's interpretation within seconds.

Trade smart. Stay informed. Stay ahead.

Built for News Traders

HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data directly from official sources for professional algorithmic and manual news trading.

Explore HAAWKS G4A Data Feeds

Sources

  1. U.S. Bureau of Labor Statistics — Employment Situation, July 2026
    Official source for nonfarm payrolls, unemployment, labor-force participation, earnings, industry employment and prior-month revisions.
  2. Reuters — U.S. job growth expected to pick up in July
    Used for the pre-release economist consensus of +80K payrolls, 4.2% unemployment and 3.5% annual wage growth.
  3. Reuters — U.S. suffers unexpected job losses in July
    Used for post-release labor-market and financial-market context.
  4. Reuters — Dollar drops after weak U.S. jobs data
    Used for broader FX and gold-market reaction following the report.
  5. Reuters — Markets reduce odds of September Fed rate hike
    Used for the post-NFP monetary-policy repricing.
  6. HAAWKS internal tick-chart analysis — August 7, 2026
    Used for the measured release-window reactions in USD/JPY, EUR/USD, XAU/USD and US500.
Disclaimer: This material is provided for informational and educational purposes only. It does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The market moves described above are historical measured price reactions and do not represent guaranteed or necessarily achievable profits. Actual execution depends on latency, liquidity, spreads, slippage, order type, venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for qualified professionals.

Comment

Comment

Natural Gas Futures Drop 39 Ticks in 11 Seconds After EIA Storage Report

According to our analysis natural gas moved 39 ticks on DOE Natural Gas Storage Report (WNGSR) data on 16 July 2026.

Natural gas (39 ticks)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Natural Gas Storage Build Triggers a 39-Tick Selloff in 11 Seconds

U.S. natural gas futures reacted sharply after the EIA reported a 41 Bcf storage injection, with the market looking beyond the slightly smaller-than-expected build to focus on abundant inventories and strong domestic production.

July 16, 2026 • Release time: 10:30 a.m. ET • Week ending July 10, 2026

The U.S. Energy Information Administration reported that working natural gas inventories increased by 41 billion cubic feet during the week ending July 10, bringing total Lower 48 storage to 3,024 Bcf.

The build was slightly smaller than the Reuters analyst consensus of 43 Bcf and below the five-year average injection of 45 Bcf. Despite the modestly tighter weekly flow, natural gas sold off immediately after the release.

HAAWKS first read: The market did not treat the smaller-than-expected injection as a sustainable bullish signal. Traders instead focused on inventories remaining 6.4% above the five-year average, rising production and softer LNG feedgas demand.

Storage Report at a Glance

Weekly Injection +41 Bcf Reuters consensus: +43 Bcf
Total Storage 3,024 Bcf Lower 48 working gas
vs. Five-Year Average +181 Bcf 6.4% above average
vs. One Year Ago −21 Bcf 0.7% below last year
Weekly natural gas storage report compared with forecasts and historical levels
Storage Indicator Reported Comparison HAAWKS Read-through
Weekly Net Change +41 Bcf Reuters forecast: +43 Bcf The injection was 2 Bcf below consensus, representing a slightly tighter weekly result than expected.
Five-Year Average Injection +45 Bcf Actual was 4 Bcf smaller The weekly flow was below normal, but the total inventory surplus remained substantial.
Total Working Gas 3,024 Bcf 3,045 Bcf one year ago Inventories were 21 Bcf, or 0.7%, below the comparable year-earlier level.
Five-Year Average Stocks 2,843 Bcf Current stocks: +181 Bcf The 6.4% storage surplus continued to provide a bearish buffer against weather-driven demand.

Immediate Market Reaction

39 Ticks Lower

Natural Gas Fell 39 Ticks in 11 Seconds

The HAAWKS tick chart recorded an immediate 39-tick decline in natural gas within the first 11 seconds following the 10:30 a.m. ET storage release. The speed of the move showed that the market interpreted the broader storage and supply backdrop as bearish, despite the injection coming in slightly below expectations.

Natural gas market reaction following the weekly EIA storage report
Market Measured Move Time Window Initial Direction Interpretation
Natural Gas 39 ticks 11 seconds Lower Immediate selling indicated that surplus inventories and broader supply conditions outweighed the slightly smaller weekly build.

Regional Storage Breakdown

The Midwest recorded the largest regional injection at 20 Bcf, followed by the East with 14 Bcf. The South Central region added only 3 Bcf as a 5 Bcf withdrawal from salt facilities partially offset an 8 Bcf injection into nonsalt storage.

Regional changes in U.S. natural gas storage for the week ending July 10, 2026
Region Working Gas Weekly Change vs. Last Year vs. Five-Year Average
East 614 Bcf +14 Bcf −1.9% +1.7%
Midwest 749 Bcf +20 Bcf +3.0% +6.2%
Mountain 240 Bcf +4 Bcf +2.6% +21.2%
Pacific 319 Bcf 0 Bcf +8.5% +21.8%
South Central 1,103 Bcf +3 Bcf −5.2% +2.7%
Total Lower 48 3,024 Bcf +41 Bcf −0.7% +6.4%

Why Did Natural Gas Fall?

The Storage Surplus Remained Large

Although the weekly injection was slightly smaller than expected, inventories remained 181 Bcf above the five-year average. That surplus continued to limit concerns about supply availability during the summer cooling season.

Production Remained Strong

Lower 48 natural gas production averaged approximately 110.3 Bcf per day during July. Strong output gave the market confidence that storage could remain adequately supplied even as electricity demand increased.

LNG Feedgas Flows Were Below Their Peak

Feedgas flows to major U.S. LNG export terminals averaged around 17.4 Bcf per day during July, below the record level reached in April. Reduced export demand left more domestic supply available to the U.S. market.

HAAWKS view: The 41 Bcf injection was nominally supportive because it came in below both consensus and the five-year average. However, the 39-tick selloff showed that traders placed greater weight on the continuing inventory surplus, high production and subdued LNG demand.

What Traders Should Watch Next

Weather remains the most important near-term variable. Sustained heat across the Midwest and East could increase power-sector gas consumption and produce a smaller injection in the next storage report.

Traders should also monitor Lower 48 production, LNG terminal activity and the pace at which the five-year storage surplus narrows. A series of tighter injections would be more important than a single below-average build.

The next EIA Weekly Natural Gas Storage Report is scheduled for July 23, 2026, at 10:30 a.m. ET.

HAAWKS Conclusion

The July 16 natural gas storage report delivered a slightly tighter result than expected. The 41 Bcf injection was below the 43 Bcf Reuters consensus and the 45 Bcf five-year average build.

The immediate market response was nevertheless decisively bearish. Natural gas dropped 39 ticks in only 11 seconds, demonstrating that the market remained more concerned with abundant total inventories than with the modest weekly miss.

Total working gas stood at 3,024 Bcf—21 Bcf below the prior-year level but still 181 Bcf above the five-year average. This left the market adequately supplied and reduced the urgency to price a near-term shortage.

The key message is that the headline injection cannot be viewed in isolation. Storage levels, production, weather, electricity demand and LNG exports collectively determine whether a report is genuinely bullish or bearish.

Trade smart. Stay informed. Stay ahead.

Sources

  1. U.S. Energy Information Administration — Weekly Natural Gas Storage Report
    Official source for the 41 Bcf injection, total Lower 48 inventories, regional storage changes and comparisons with last year and the five-year average.
  2. Reuters — U.S. natural gas prices slide on rising production and ample storage
    Used for the 43 Bcf analyst consensus, five-year average injection, production, LNG flows and broader futures-market context.
  3. HAAWKS internal natural gas tick-chart analysis — July 16, 2026
    Used for the measured release-window market reaction of 39 ticks lower in 11 seconds.
Disclaimer: This material is provided for informational and educational purposes only. It does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. Trading involves risk, and past market behavior is not indicative of future results.

Haawks G4A low latency machine-readable data is one of the fastest data feeds for DOE data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

June 2026 CPI: Cooler Inflation Sends the Dollar Lower and Risk Assets Higher

According to our analysis USDJPY moved 21 pips, EURUSD moved 17 pips, US500 moved 76 ticks and XAUUSD 34 points on US BLS Consumer Price Index (CPI) data on 14 July 2026.

USDJPY (21 pips)

EURUSD (17 pips)

US500 (76 ticks)

XAUUSD (34 points)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

June 2026 CPI: Inflation Cools Faster Than Expected

A sharp decline in energy prices and an unexpectedly soft core reading triggered immediate moves across currencies, gold and U.S. equities.

July 14, 2026 • Release time: 8:30 a.m. ET • Consumer Price Index

The June 2026 U.S. Consumer Price Index delivered a clear downside inflation surprise. Headline CPI declined 0.4% month over month, while annual inflation slowed to 3.5%. Core CPI, which excludes food and energy, was unchanged during the month and slowed to 2.6% year over year.

The report was softer than economists had expected at both the headline and core levels. Markets responded by selling the U.S. dollar and moving into rate-sensitive assets, including gold and U.S. equities.

HAAWKS first read: The release reduced immediate inflation anxiety, but the details require balance. Falling energy prices drove much of the headline decline, while the unchanged core reading showed that underlying inflation also cooled during June.

CPI Estimates vs. Actual Release

Headline CPI MoM −0.4% Forecast: −0.1%
Headline CPI YoY 3.5% Forecast: 3.8%
Core CPI MoM 0.0% Forecast: +0.2%
Core CPI YoY 2.6% Forecast: 2.8%
June 2026 CPI estimates compared with actual results
Inflation Indicator Estimate Actual HAAWKS Read-through
Headline CPI MoM −0.1% −0.4% A materially softer monthly reading, driven primarily by lower energy prices.
Headline CPI YoY 3.8% 3.5% Annual inflation slowed more quickly than markets expected.
Core CPI MoM +0.2% 0.0% The unchanged core index was an important downside surprise.
Core CPI YoY 2.8% 2.6% Underlying annual inflation continued moving toward a more moderate pace.

What Drove the Inflation Decline?

Energy was the largest contributor to the monthly decline. The energy index fell 5.7%, while gasoline prices dropped 9.7%. Those declines more than offset increases in food and shelter.

Food prices increased 0.2% during June, while shelter rose only 0.1%—its smallest monthly increase since January 2021. Motor vehicle insurance, communication, apparel, medical care and used vehicle prices also declined.

Key components of the June 2026 Consumer Price Index
CPI Component Monthly Change Annual Change Interpretation
All Items −0.4% +3.5% The largest monthly headline decline since April 2020.
Core CPI 0.0% +2.6% Underlying price pressures were unchanged during the month.
Energy −5.7% +15.7% The largest contributor to the monthly CPI decline.
Gasoline −9.7% +26.7% A sharp monthly reversal, although prices remained elevated compared with a year earlier.
Shelter +0.1% +3.3% The smallest monthly shelter increase since January 2021.
Food +0.2% +3.0% Food inflation remained positive but relatively contained.

Market Impact at a Glance

HAAWKS tick charts captured the initial release-window moves immediately following the 8:30 a.m. ET CPI announcement.

Market impact following the June 2026 CPI release
Market Measured Move Initial Direction HAAWKS Interpretation
USD/JPY 21 pips Lower The dollar weakened against the yen as traders reduced the probability of near-term Federal Reserve tightening.
EUR/USD 17 pips Higher The euro advanced as the softer inflation reading pressured the broader U.S. dollar.
US500 76 ticks Higher Equities rallied as the inflation surprise reduced immediate concerns about restrictive monetary policy.
XAU/USD 34 points Higher Gold benefited from a weaker dollar and lower expectations for near-term interest-rate increases.

Cross-Asset Market Reading

Foreign Exchange

The immediate FX response was a weaker U.S. dollar. USD/JPY moved lower, while EUR/USD moved higher. This was consistent with markets reducing expectations that the Federal Reserve would need to tighten policy in the immediate future.

Gold

Gold produced one of the strongest reactions. Softer inflation generally supports non-yielding assets when it lowers Treasury yields and weakens the dollar. The HAAWKS measurement recorded a 34-point release-window advance.

U.S. Equities

The US500 initially gained 76 ticks. The market interpreted the report as supportive for valuations because inflation cooled without the release itself presenting a direct signal of collapsing economic demand.

HAAWKS view: The release created a broadly dovish cross-asset response—USD lower, gold higher and equities higher. The core CPI miss strengthened the move because the moderation was not limited entirely to volatile energy prices.

What the CPI Report Means for the Fed

The June figures gave policymakers additional breathing room. Headline inflation remained above the Federal Reserve’s longer-term objective, but both headline and core CPI came in below expectations.

The report does not eliminate future inflation risk. Much of the headline decline reflected lower gasoline and energy prices, which can reverse quickly. Renewed pressure on oil markets could therefore make upcoming inflation reports less favorable.

For traders, the key question is whether the softer core readings continue. A sustained moderation in shelter and services inflation would provide a stronger signal than a single energy-driven monthly decline.

HAAWKS Conclusion

The June CPI release was decisively softer than expected. Headline prices fell 0.4%, core prices were unchanged and both annual measures undershot consensus forecasts.

Markets reacted in a clear and coordinated manner: the dollar weakened, gold advanced and the US500 rallied. The HAAWKS measurements recorded 21 pips in USD/JPY, 17 pips in EUR/USD, 76 ticks in the US500 and 34 points in XAU/USD.

The report offered short-term relief from inflation concerns, but it should not be viewed as an all-clear signal. Energy volatility remains a material risk, and annual headline inflation was still elevated.

The central message is therefore one of moderation rather than victory: inflation cooled faster than expected, underlying pressure eased and markets rapidly repriced the near-term policy outlook.

Trade smart. Stay informed. Stay ahead.

Sources

  1. U.S. Bureau of Labor Statistics — Consumer Price Index, June 2026 . Official CPI figures, component data and release details.
  2. Reuters — U.S. consumer inflation preview and economist consensus
    Used for the pre-release market estimates for headline and core consumer inflation.
  3. Reuters — Traders reduce expectations for a July Fed rate increase
    Used for market-implied Federal Reserve policy expectations following the report.
  4. HAAWKS internal tick-chart screenshots captured on July 14, 2026. Used for the measured release-window moves in USD/JPY, EUR/USD, US500 and XAU/USD.
Disclaimer: This material is provided for informational and educational purposes only. It does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. Trading involves risk, and past market behavior is not indicative of future results.

Start futures forex fx news trading with Haawks G4A low latency machine-readable data, one of the fastest machine-readable news trading feed for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

June 2026 NFP: Softer Payroll Growth Triggers Sharp Moves Across FX, Gold and US500 on US Employment Situation (NFP)

According to our analysis USDJPY moved 37 pips, EURUSD moved 25 pips, XAUUSD (spot gold) moved 43 points and US500 moved 56 ticks (118 ticks total) on US Employment Situation (Non-farm payrolls / NFP) data on 2 July 2026.

USDJPY (37 pips)

EURUSD (25 pips)

XAUUSD (43 points)

US500 (56 ticks)

Charts are exported from JForex (Dukascopy).


June 2026 NFP: Softer Jobs, Stable Wages, Sharp Market Reaction

HAAWKS Research | July 2, 2026

HAAWKS NFP market impact summary showing June 2026 labor market figures and release-window moves in USDJPY, EURUSD, XAUUSD, and US500

The June 2026 U.S. Nonfarm Payrolls release delivered a classic “soft but not broken” labor-market signal. Payroll growth slowed materially, but unemployment remained low and wage growth stayed contained. For markets, that combination was enough to trigger immediate volatility across FX, gold, and equity index futures.

The Bureau of Labor Statistics reported that total nonfarm payroll employment rose by 57,000 in June, while the unemployment rate stood at 4.2%. Average hourly earnings increased 0.3% month over month and 3.5% year over year. The prior two months were also revised lower by a combined 74,000 jobs, with April revised to +148,000 and May revised to +129,000.

Research Estimates vs. Actual Release

Ahead of the release, market expectations were for a stronger labor print. Consensus estimates pointed to nonfarm payrolls rising by roughly 110,000, unemployment near 4.3%, and average hourly earnings increasing 0.3% month over month.

The actual release came in softer on headline job creation, but broadly stable on unemployment and wages.

Indicator Estimate Actual HAAWKS Read-through
Nonfarm Payrolls +110K +57K Clear downside miss. Headline job creation came in softer than expected.
Unemployment Rate 4.3% 4.2% Better than expected, though the participation-rate decline softened the signal.
Average Hourly Earnings MoM +0.3% +0.3% In line. Wage growth remained contained.
Average Hourly Earnings YoY +3.5% +3.5% In line. No upside wage shock.
Prior-Month Revisions — -74K April and May were revised lower, pointing to softer labor momentum than previously reported.

The headline payroll miss was the main surprise. However, wage growth did not accelerate, unemployment remained low, and the report avoided the kind of broad deterioration that would suggest an immediate labor-market break.

Market Impact: HAAWKS Tick-Chart Reaction

The HAAWKS market-impact screenshots captured the immediate release-window volatility:

Market Measured Impact Direction HAAWKS Interpretation
USD/JPY 37 pips Lower The U.S. dollar sold off sharply against the yen after the softer payroll print.
EUR/USD 25 pips Higher The euro rallied as dollar weakness spread across major FX pairs.
XAU/USD 43 points Higher Gold rallied as traders repriced rate expectations following the weaker jobs number.
US500 56 ticks Higher Equities initially caught a bid as slower job growth supported the soft-landing narrative.

The market reaction was consistent with a softer-than-expected labor report. The U.S. dollar weakened, gold rallied, and equities reacted positively to the possibility that slower job growth could reduce pressure on the Federal Reserve to keep policy restrictive for longer.

Sector Detail: Slower Hiring, Not a Full Breakdown

The report showed continued job gains in professional and business services, social assistance, and health care, while leisure and hospitality lost 61,000 jobs. That divergence matters. It suggests the labor market is not uniformly weak, but momentum is becoming narrower.

The downward revisions were also important. A one-month payroll miss can be dismissed as noise; a miss combined with negative revisions tells a more cautious story. The labor market still appears functional, but the pace of hiring is clearly cooling.

HAAWKS Conclusion

The June NFP release was not a recession signal, but it was a warning that the labor market is losing speed.

For traders, the key takeaway was not simply that payrolls missed. It was the combination of:

Soft job creation, stable wages, lower unemployment, and negative revisions.

That mix created a “Goldilocks” reaction in markets: weak enough to pressure the dollar and support rate-sensitive assets, but not weak enough to trigger immediate risk-off panic.

Asset Class Reaction Why It Moved Trading Takeaway
FX Dollar weaker The headline payroll miss reduced near-term support for the U.S. dollar. USD vulnerability remained the cleanest immediate signal.
Gold Gold stronger Softer labor data supported lower-rate sensitivity and demand for precious metals. XAU/USD remained supported while rate-cut expectations held firm.
Equities Risk initially bid Stable wages and softer hiring helped support the soft-landing view. US500 strength reflected relief rather than a broad growth acceleration signal.
Rates Narrative Dovish lean The report was soft enough to support easing expectations, but not weak enough to trigger panic. The market reaction fit a classic “Goldilocks” setup.

The HAAWKS read:

USD vulnerability remains the cleanest short-term signal, while gold and equity indices may continue to benefit if incoming data supports the view that inflation pressure is easing without a sharp employment shock.

Final Takeaway

The June 2026 NFP report reinforced a market theme that traders cannot ignore:

Labor momentum is cooling, wage pressure is stable, and markets are increasingly sensitive to every data point that affects the Fed path.

For HAAWKS traders, the opportunity is not just in the headline number. It is in understanding how that number moves liquidity, volatility, and cross-asset positioning in real time.

Trade smart. Stay informed. Stay ahead.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Sources

  1. U.S. Bureau of Labor Statistics — Employment Situation Summary, June 2026
    Used for the official NFP release figures, including +57K nonfarm payrolls, 4.2% unemployment, +0.3% monthly wage growth, +3.5% annual wage growth, labor-force participation, sector detail, and prior-month revisions.
  2. Reuters — U.S. job growth likely cooled in June after recent string of big gains
    Used for pre-release market expectations, including the +110K nonfarm payroll estimate and 4.3% unemployment forecast.
  3. Reuters — Nasdaq, S&P 500 decline with tech; investors assess softer jobs data
    Used for equity-market context following the softer-than-expected jobs report.
  4. Reuters — Dollar slides after soft jobs report, yen surges
    Used for U.S. dollar and yen market reaction after the NFP release.
  5. Reuters — Gold gains after weak U.S. payrolls report
    Used for gold-market reaction and rate-expectation context after the payroll miss.
  6. HAAWKS internal tick-chart screenshots, captured July 2, 2026.
    Used for measured release-window market impact: USD/JPY 37 pips, EUR/USD 25 pips, XAU/USD 43 points, and US500 56 ticks.

Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

30 ticks potential profit in 97 seconds on 28 May 2026, analysis on futures news trading natural gas on DOE Natural Gas Storage Report (WNGSR) data

According to our analysis natural gas moved 30 ticks on DOE Natural Gas Storage Report (WNGSR) data on 28 May 2026.

Natural gas (30 ticks)

Charts are exported from JForex (Dukascopy).


U.S. Natural Gas Storage Climbs by 92 Bcf, Staying Above the Five-Year Average

U.S. working natural gas in underground storage rose sharply for the week ending May 22, 2026, according to the latest Weekly Natural Gas Storage Report from the U.S. Energy Information Administration. Total working gas stocks reached 2,483 billion cubic feet (Bcf), reflecting a net increase of 92 Bcf from the prior week.

The latest build keeps storage levels slightly above both last year’s mark and the five-year average. Stocks were 21 Bcf higher than the same week in 2025 and 144 Bcf above the five-year average of 2,339 Bcf. At 2,483 Bcf, total working gas remains within the five-year historical range.

Regional Storage Trends

The weekly increase was broad-based across all major Lower 48 storage regions.

The East region reported working gas stocks of 447 Bcf, up 28 Bcf from the previous week. Compared with historical levels, East inventories were 2.4% below last year but 1.1% above the five-year average.

The Midwest posted one of the larger regional gains, rising 34 Bcf to 539 Bcf. That placed Midwest stocks 0.4% above year-ago levels and 1.5% above the five-year average.

In the Mountain region, inventories increased by 3 Bcf to 213 Bcf. Storage levels there remained notably elevated, standing 8.1% above last year and 35.7% above the five-year average.

The Pacific region added 6 Bcf, bringing stocks to 292 Bcf. Pacific inventories were 15.4% higher than last year and 30.9% above the five-year average, making it one of the strongest regions relative to historical norms.

The South Central region reported stocks of 993 Bcf, up 21 Bcf from the previous week. Inventories were 2.4% below last year but still 0.6% above the five-year average.

Within South Central, salt storage rose by 7 Bcf to 305 Bcf, while nonsalt storage increased by 15 Bcf to 688 Bcf. Salt storage remained 6.7% below year-ago levels, though it was 2.0% above the five-year average. Nonsalt storage was nearly unchanged from both last year and the five-year average.

Storage Remains Comfortable Heading Into Summer

The 92 Bcf injection marks a sizable weekly build and leaves U.S. natural gas inventories in a relatively comfortable position heading into the summer cooling season. Total storage is not dramatically above historical norms, but it remains meaningfully stronger than the five-year average.

The regional breakdown also shows important differences. The Mountain and Pacific regions continue to hold inventories far above their five-year averages, while the East and South Central regions are modestly below last year’s levels. Still, the national picture points to adequate storage, with total working gas safely within the five-year historical range.

Key Takeaways

For the week ending May 22, 2026:

  • Total U.S. working natural gas in storage was 2,483 Bcf

  • Inventories increased by 92 Bcf from the previous week

  • Stocks were 21 Bcf higher than last year

  • Storage was 144 Bcf above the five-year average

  • Total working gas remained within the five-year historical range

  • The largest weekly regional increases came from the Midwest, East, and South Central regions

Overall, the latest EIA report suggests that U.S. natural gas storage remains well-positioned, with inventories above average and continued injections supporting supply levels ahead of peak summer demand.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://ir.eia.gov/ngs/ngs.html


Start futures forex fx commodity news trading with Haawks G4A low latency machine-readable data, one of the fastest data feeds for DOE data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment