Viewing entries tagged
US500

Comment

Softer PCE Inflation Sends US500 Up 68 Ticks as Dollar Weakens

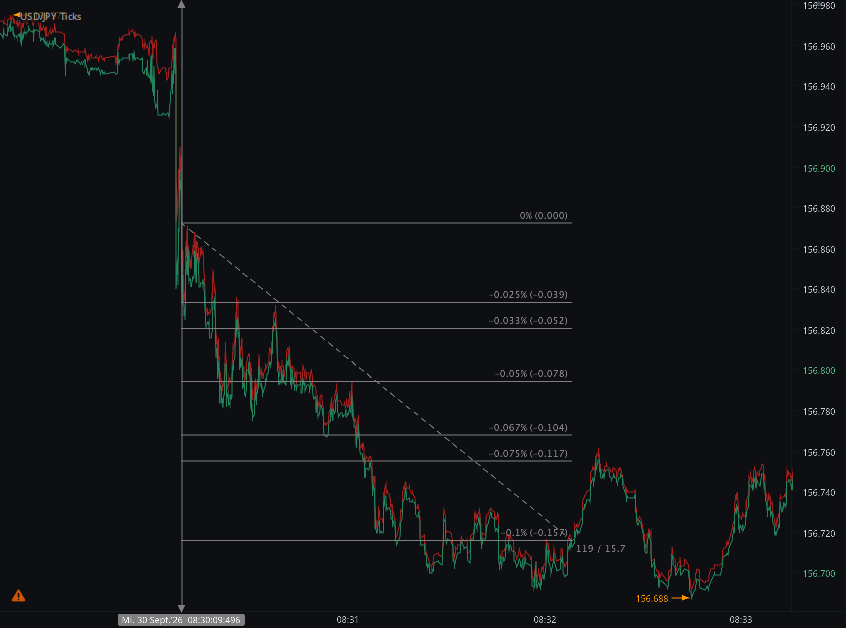
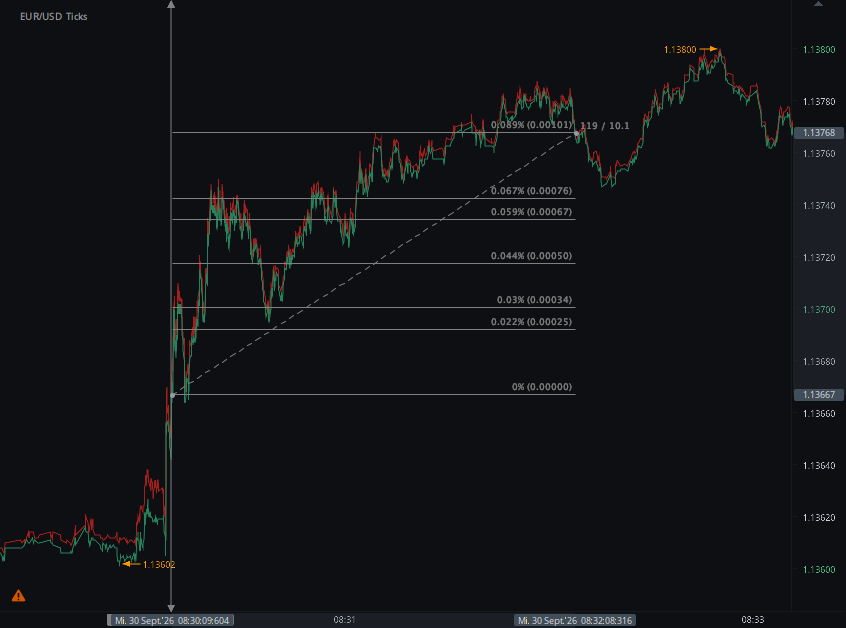
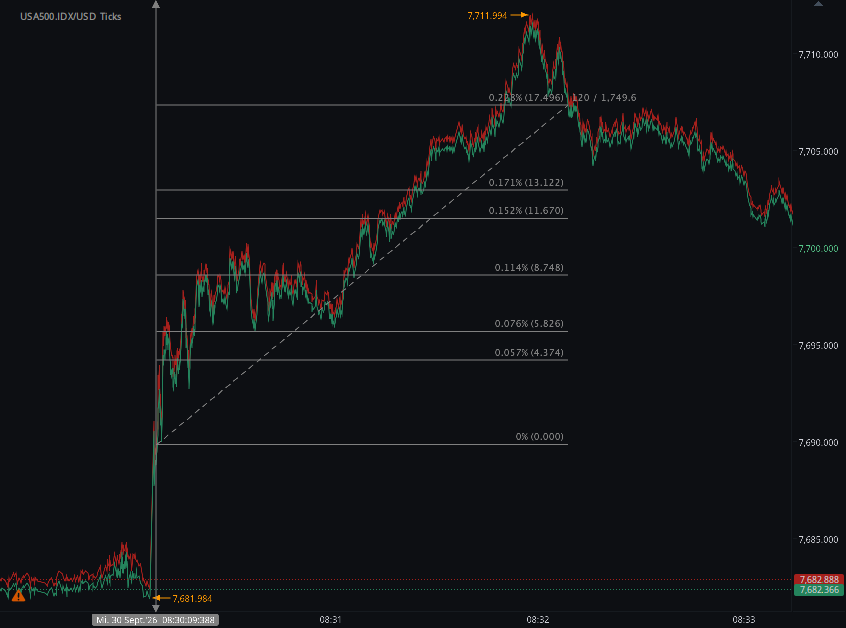
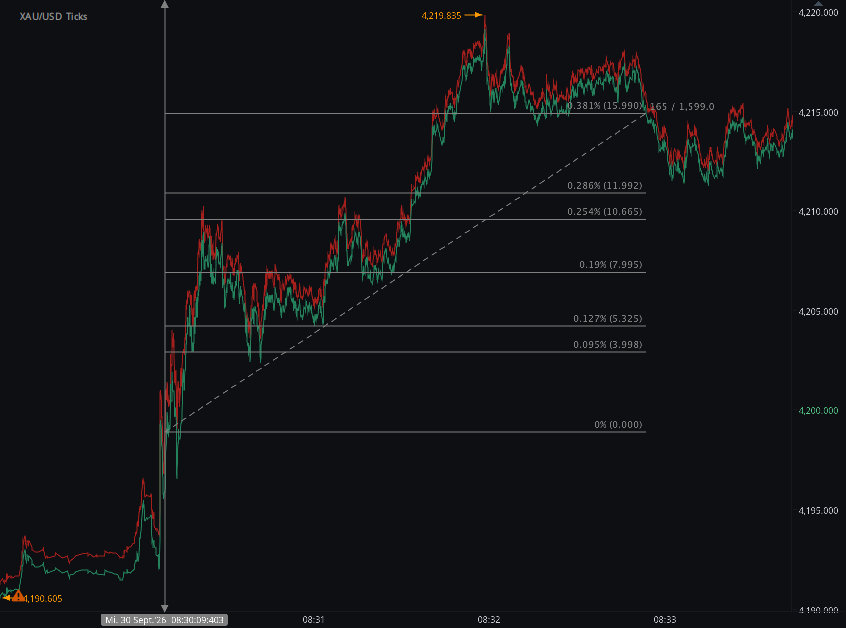
According to our analysis USDJPY moved 15 pips, EURUSD moved 10 pips, US500 moved 68 ticks and XAUUSD 15 points (93 ticks, gold 15 points total) on US BEA Personal Income and Outlays and US BEA Gross Domestic Production (GDP) data on 30 September 2026.

USDJPY (15 pips)
EURUSD (10 pips)
US500 (68 ticks)
XAUUSD (15 points)
Charts are exported from JForex (Dukascopy).


HAAWKS Research

Softer PCE Inflation Drives Dollar Lower as US500 and Gold Rally

August PCE inflation undershot expectations while the third estimate of second-quarter U.S. GDP was revised sharply higher. The simultaneous BEA releases produced an immediate cross-asset repricing in FX, equities and gold.

September 30, 2026 • Release time: 8:30 a.m. ET • BEA PCE & GDP

Two major U.S. macroeconomic releases hit institutional trading systems simultaneously at 8:30 a.m. ET on September 30: August Personal Income and Outlays, including the Federal Reserve's preferred PCE inflation measures, and the third estimate of second-quarter GDP.

The combined signal was unusual. Inflation was softer than expected, while economic growth was revised materially higher.

In the first minutes after the release, markets appeared to give greater weight to the inflation surprise and its implications for Federal Reserve policy.

HAAWKS measured an immediate 10-tick rise in EUR/USD, 15-tick decline in USD/JPY, 68-tick rise in US500 and 15-point rise in XAU/USD.

Institutional read-through: the cross-asset configuration — weaker USD, stronger equities and stronger gold — was consistent with a decline in near-term U.S. rate-hike expectations. The much stronger GDP revision provided an important counter-signal, but it did not dominate the initial release-window repricing.

Immediate Cross-Asset Reaction

EUR/USD +10 Ticks USD weaker
USD/JPY −15 Ticks USD weaker
US500 +68 Ticks Immediate equity rally
XAU/USD +15 Points Gold higher
Instrument HAAWKS Measured Move Direction Institutional Interpretation
EUR/USD 10 ticks Higher Broadly consistent with a softer U.S. dollar following the lower-than-expected PCE inflation readings.
USD/JPY 15 ticks Lower Reinforced the initial USD-negative interpretation across major FX pairs.
US500 68 ticks Higher Lower expected policy-rate pressure initially supported equity valuations.
XAU/USD 15 points Higher Gold benefited from the initial decline in U.S. rate expectations and dollar weakness.

August PCE: The Dominant Release-Window Signal

The principal inflation measures came in below market expectations. Headline PCE increased 0.3% month over month, compared with a Reuters consensus estimate of 0.4%.

On a year-over-year basis, headline PCE inflation was 3.4%, below the approximately 3.7% expected before the release.

Core PCE, which excludes food and energy and receives particular attention from Federal Reserve policymakers, rose 0.2% month over month and 3.0% year over year.

Headline PCE MoM +0.3% Reuters expectation: +0.4%
Headline PCE YoY 3.4% Reuters expectation: 3.7%
Core PCE MoM +0.2% Softer underlying inflation
Core PCE YoY 3.0% Revised inflation profile
HAAWKS view: for the first market reaction, the inflation surprise carried greater policy relevance than the backward-looking GDP revision. The combination of EUR/USD higher, USD/JPY lower, US500 higher and gold higher is consistent with the market initially reducing the probability of additional near-term Federal Reserve tightening.

An Important Institutional Caveat: The PCE Data Were Revised

The September 30 release was not a standard monthly update in isolation. It incorporated BEA's 2026 annual update of the National Economic Accounts, with revisions to personal income, spending and inflation estimates beginning in January 2021.

That distinction matters for systematic interpretation.

July headline PCE inflation was revised down to 0.1% month over month, while July core PCE was also revised to 0.1%.

Reuters reported that methodology changes affecting areas including portfolio-management services, software and legal services contributed materially to lower historical inflation readings.

Institutional implication: a low-latency model should distinguish a genuinely new monthly inflation surprise from revisions caused by annual benchmarking or methodology changes. Both can move markets, but they represent different information structures and may deserve different model weights.

The Consumer Remained Exceptionally Strong

The inflation data were softer, but the broader household data were not weak.

Nominal personal consumption expenditures increased 0.9% in August, equivalent to a $190.8 billion increase.

Inflation-adjusted real PCE increased 0.6%, indicating that the spending acceleration was not merely a function of higher prices.

Personal income increased only 0.2%, while disposable personal income increased 0.3%. Real disposable income was unchanged.

The personal saving rate declined to 4.1%, showing that the strength in consumption was accompanied by a lower share of disposable income being saved.

August Household Measure BEA Result Institutional Read-Through
Personal Income +0.2% Income growth remained positive but materially lagged consumption growth.
Disposable Personal Income +0.3% Moderate nominal household-income growth.
Real DPI 0.0% No monthly increase in inflation-adjusted disposable income.
Nominal PCE +0.9% Very strong consumer spending despite elevated borrowing costs.
Real PCE +0.6% Indicates genuine volume growth rather than only price effects.
Saving Rate 4.1% Household spending growth continued to outpace income growth.

GDP Delivered a Powerful Counter-Signal

At exactly the same 8:30 a.m. ET release time, BEA published its third estimate of second-quarter GDP.

Real GDP growth was revised sharply higher to an annualized 2.2%, compared with 1.5% in the second estimate.

The 0.7-percentage-point upward revision reflected stronger investment, consumer spending and government spending.

Q2 U.S. Measure Second Estimate Third Estimate Institutional Significance
Real GDP 1.5% 2.2% Material upward revision to aggregate economic growth.
Real Final Sales to Private Domestic Purchasers 4.2% 4.6% Strong underlying private domestic demand.
Real GDI 2.2% 2.6% Income-side measure also pointed to firmer activity.
Average of GDP and GDI 1.8% 2.4% Broader confirmation that Q2 activity was stronger than previously estimated.

Underlying Domestic Demand Was Stronger Than Headline GDP

For institutional macro investors, the composition of GDP may be more informative than the headline 2.2% figure.

Real final sales to private domestic purchasers — consumer spending plus private fixed investment — increased at a 4.6% annualized rate.

This measure removes several volatile components of GDP and provides a cleaner indication of underlying private domestic demand.

BEA attributed the Q2 GDP expansion to consumer spending, investment and exports, while increased imports subtracted from the headline calculation.

Among industries, the strongest contributors included real estate and rental and leasing, information, durable-goods manufacturing, and finance and insurance.

Corporate Profits Added to the Growth Signal

Profits from current production increased by $384.0 billion in the second quarter, although that figure was revised down by $16.9 billion from the previous estimate.

The combination of stronger consumer activity, investment and corporate earnings helps explain why the GDP release offered a distinctly growth-positive counterweight to the softer inflation figures.

Why the Inflation Signal Won the First Policy Repricing

Inflation Undershot Expectations

Headline monthly PCE rose 0.3% versus a 0.4% Reuters consensus, while the annual rate was 3.4% versus approximately 3.7% expected.

The Data Were Directly Relevant to the Fed

PCE inflation is the Federal Reserve's preferred consumer-inflation framework, making an inflation surprise immediately relevant to policy-rate pricing.

GDP Was Backward Looking

The 2.2% GDP figure described activity during April through June. The August PCE data provided more recent information about the inflation environment.

Growth Remained a Hawkish Counterweight

Strong consumption, a 4.6% increase in private domestic final sales and the GDP revision argue against interpreting the release as a simple growth slowdown.

Institutional takeaway: this was closer to a "soft inflation, strong demand" configuration than a straightforward dovish macro release. The first price response favored the inflation signal, but the underlying growth data remained too strong to justify treating the report as an unambiguously weak U.S. macro outcome.

Federal Reserve Expectations Repriced Lower

The immediate rates-market response reinforced the cross-asset signal.

Reuters reported that the implied probability of another Federal Reserve rate increase at the October meeting fell to approximately 41.5% after the data, from roughly 51.5% immediately beforehand.

U.S. Treasury yields initially declined and the dollar weakened, consistent with the HAAWKS FX, equity and gold observations.

That repricing did not eliminate the possibility of additional tightening. Inflation remained above the Federal Reserve's longer-run objective and household demand remained exceptionally resilient.

One Timestamp, Multiple Macro Signals

September 30 also illustrates a problem that matters directly to institutional news-trading infrastructure: multiple high-value data sets can be released at precisely the same timestamp.

At 8:30 a.m. ET, systems were required to process not merely one PCE figure but a large matrix of information including:

Data Family Examples of Relevant Fields Primary Market Channel
PCE Inflation Headline MoM, headline YoY, core MoM, core YoY Federal Reserve policy expectations
Household Income Personal income, disposable income, real DPI Household purchasing capacity
Consumer Spending Nominal PCE, real PCE, goods and services Current-quarter growth expectations
GDP Real GDP, final sales, investment, consumption Growth and policy outlook
GDI Real GDI and GDP/GDI average Confirmation of economic activity
Corporate Profits Current-production profits and industry measures Equity and growth fundamentals

Implications for Institutional News-Trading Systems

Field-Level Parsing Is Essential

A system reacting only to headline PCE could miss the interaction among core inflation, spending, income, GDP revisions and prior-period revisions.

Release Vintage Must Be Preserved

The 2026 annual update changed historical PCE and GDP estimates. Institutional research and systematic backtesting therefore need to distinguish the data available in real time from subsequently revised historical series.

Surprise Direction Is Not Enough

Softer inflation was dovish, while stronger GDP and spending were comparatively hawkish. A robust model needs to evaluate the magnitude, timeliness and policy relevance of competing surprises.

Cross-Asset Confirmation Adds Information

EUR/USD higher, USD/JPY lower, gold higher and equities higher provided a coherent initial cross-asset signal consistent with reduced near-term U.S. rate expectations.

Release-Window Movement Is Not Full-Session Performance

HAAWKS measurements isolate the immediate market response to the scheduled release. Subsequent price action incorporates liquidity, positioning, policy commentary and additional economic information.

Immediate Reaction vs. the Full Trading Session

The initial response should not be confused with the eventual daily close.

HAAWKS measured a strong 68-tick US500 increase during the release window, reflecting the first repricing of the new information.

The broader U.S. equity session subsequently became more mixed as investors continued to digest the strength of economic activity and elevated longer-term interest rates.

This distinction is central to institutional event analysis: release-window attribution asks a different question from end-of-day market attribution.

HAAWKS Conclusion

The September 30 BEA releases delivered one of the more complex U.S. macro combinations for systematic news traders: softer inflation alongside substantially stronger growth and exceptionally resilient consumer spending.

August headline PCE increased 0.3% month over month and 3.4% year over year, while core PCE increased 0.2% and 3.0%, respectively.

At the same time, second-quarter real GDP was revised from 1.5% to 2.2%, real final sales to private domestic purchasers increased 4.6%, and August nominal consumer spending surged 0.9%.

The market's initial interpretation nevertheless leaned toward the inflation side of the release.

HAAWKS measured EUR/USD +10 ticks, USD/JPY −15 ticks, US500 +68 ticks and XAU/USD +15 points in the immediate release window.

For institutional trading systems, the event demonstrates why a simultaneous macro release cannot be reduced to one headline field. Current values, consensus expectations, prior revisions, annual benchmarking, growth composition and cross-asset confirmation all need to be evaluated while the market is repricing.

Low-Latency Data. Structured Intelligence. Institutional Execution.

Low-Latency Macro Data for Institutional Markets

HAAWKS G4A provides structured, machine-readable macroeconomic and commodity data covering the United States, Canada and Europe.

The feed is designed for professional news-trading desks, systematic macro strategies and latency-sensitive applications that require field-level data immediately when official releases become public.

API access is available through infrastructure in Chicago, New York and London. Free trials are available for qualified professional users.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Economic Analysis — Personal Income and Outlays, August 2026
    Official source for personal income, consumer spending, headline and core PCE inflation and the personal saving rate.
  2. U.S. Bureau of Economic Analysis — GDP Third Estimate, Industries and Corporate Profits, Second Quarter 2026
    Official source for real GDP, GDI, private domestic final sales, corporate profits and industry-level revisions.
  3. Reuters — U.S. Inflation Rises Less Than Expected in August
    Used for market consensus, Federal Reserve pricing and post-release rates and FX context.
  4. HAAWKS internal tick-chart analysis — September 30, 2026
    Source for the measured immediate release-window reactions: EUR/USD +10 ticks, USD/JPY −15 ticks, US500 +68 ticks and XAU/USD +15 points.
Data note: The September 30 releases incorporated BEA's 2026 annual update of the National Economic Accounts. Historical figures and prior-period readings may therefore differ from figures originally published in earlier release vintages. Quarterly GDP growth rates are seasonally adjusted annual rates and should not be directly compared with monthly or year-over-year PCE inflation rates without accounting for the different measurement basis.

Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The market movements described are historical measured release-window movements and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific and are not standardized measures of financial return. Actual trading results depend on market-data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

August 2026 CPI: Hotter Core CPI Sends US500 Down 48 Ticks and Gold Down 19 Points

According to our analysis US500 moved 48 ticks and XAUUSD 19 points on US BLS Consumer Price Index (CPI) data on 11 September 2026.

US500 (48 ticks)

XAUUSD (19 points)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

Hotter Core CPI Sends US500 Down 48 Ticks and Gold Down 19 Points

August U.S. inflation data delivered a hotter-than-expected core CPI reading, triggering an immediate hawkish repricing across equities, gold and interest-rate expectations.

September 11, 2026 • Release time: 8:30 a.m. ET • U.S. Consumer Price Index

The August 2026 U.S. Consumer Price Index delivered a mixed headline but a more important upside surprise in underlying inflation.

Headline CPI increased 0.4% month over month, in line with expectations, while the annual rate stood at 3.4%.

The more market-sensitive core measure increased 0.3% month over month, above the 0.2% consensus forecast. Core inflation was 2.4% year over year.

HAAWKS first read: the headline CPI result itself was not the key surprise. The immediate hawkish signal came primarily from the hotter 0.3% core CPI reading versus 0.2% expected. HAAWKS measured an initial 48-tick decline in US500 and 19-point decline in XAU/USD.

August CPI: Estimates vs. Actual

Headline CPI MoM +0.4% Expected: +0.4%
Headline CPI YoY 3.4% Expected: 3.4%
Core CPI MoM +0.3% Expected: +0.2%
Core CPI YoY 2.4% Expected: 2.4%
Inflation Measure Consensus Actual HAAWKS News-Trader Read
Headline CPI MoM +0.4% +0.4% Matched expectations and therefore provided little standalone surprise.
Headline CPI YoY 3.4% 3.4% Annual headline inflation remained elevated.
Core CPI MoM +0.2% +0.3% The key upside surprise and the most clearly hawkish element of the release.
Core CPI YoY 2.4% 2.4% Matched expectations.

Immediate Market Reaction

HAAWKS tick-chart analysis captured an immediate downside reaction in both US500 and gold following the 8:30 a.m. ET inflation release.

US500 −48 Ticks Immediate release-window decline
XAU/USD −19 Points Immediate release-window decline
Market Measured Move Direction News-Trader Interpretation
US500 48 ticks Lower The hotter core CPI increased expectations for tighter Federal Reserve policy, initially pressuring equities.
XAU/USD 19 points Lower Higher expected policy rates reduced the immediate appeal of non-yielding gold.

Why the Core CPI Number Mattered Most

For news traders, this release provides another example of why headline inflation cannot be read in isolation.

Headline CPI at 0.4% was in line with expectations. If that had been the only relevant data point, the inflation release would have contained relatively little immediate surprise.

Core CPI told a different story. Prices excluding food and energy rose 0.3% during August instead of the 0.2% economists had expected.

That difference strengthened the view that underlying inflation pressure remained persistent enough to influence Federal Reserve policy expectations.

HAAWKS view: the initial US500 and gold reaction was driven less by the headline CPI number, which broadly matched expectations, and more by the upside surprise in monthly core inflation and its implications for interest rates.

What Drove August Inflation?

CPI Component August MoM 12-Month Change HAAWKS Read-Through
All Items +0.4% +3.4% Headline monthly inflation accelerated.
Core CPI +0.3% +2.4% Monthly core inflation exceeded consensus.
Energy +2.1% +16.3% Energy remained an important source of headline inflation pressure.
Gasoline +3.9% +27.4% Gasoline accounted for more than one-third of the monthly increase in headline CPI.
Shelter +0.3% +3.0% Shelter accelerated from the previous month.
Food +0.1% +2.7% Food inflation remained comparatively moderate.
Services Less Energy Services +0.3% +3.0% Continued services inflation remained relevant to the underlying inflation picture.

Gasoline Drove Part of the Headline Increase

Energy prices were an important contributor to August inflation. The energy index increased 2.1% during the month.

Gasoline prices increased 3.9% and accounted for more than one-third of the monthly increase in the all-items CPI. Over the previous 12 months, gasoline prices increased 27.4%.

Fuel oil also increased sharply during the month, while other energy components were less inflationary.

Underlying Inflation Was Broader Than Energy

The core inflation increase was distributed across several categories, reinforcing the importance of looking beyond volatile energy prices.

Shelter increased 0.3%, while several transportation and service categories also recorded price increases.

This combination helped explain why the monthly core figure exceeded expectations despite some categories continuing to show weaker price pressure.

The Federal Reserve Repricing

The CPI report arrived shortly before the September Federal Reserve policy decision, increasing its significance for rate-sensitive markets.

Recent employment data had already demonstrated stronger labor-market conditions. The hotter core CPI figure added another argument for maintaining tighter monetary policy.

Core CPI Beat Expectations

A 0.3% monthly increase compared with 0.2% expected was the clearest hawkish surprise in the report.

Energy Inflation Accelerated

Energy increased 2.1%, with gasoline up 3.9%, keeping headline inflation pressure elevated.

Shelter Increased 0.3%

Shelter remained an important component of underlying consumer inflation.

Policy Expectations Changed

The combination of stronger employment data and firmer core inflation reinforced expectations for restrictive monetary policy.

Immediate Reaction vs. the Rest of the Trading Session

News traders should distinguish the immediate release-window response from subsequent full-session market performance.

HAAWKS measured an initial 48-tick decline in US500 and a 19-point decline in XAU/USD around the CPI release.

Markets can subsequently retrace or reverse these initial moves as liquidity normalizes, traders reassess individual components and additional market information enters prices.

News-trader takeaway: release-window analysis measures the market's first response to new information. It should not be confused with the direction or size of the move over the entire trading session.

What This CPI Release Shows News Traders

Actual vs. Consensus Is the Primary Signal

Headline CPI at 0.4% carried limited surprise because it matched expectations. Core CPI at 0.3% mattered because the market had expected only 0.2%.

Headline and Core CPI Can Send Different Signals

A professional news-trading system should distinguish all-items CPI from the core measure. Each field can have a different surprise magnitude and a different effect on interest-rate expectations.

Component Data Adds Context

Gasoline, energy, shelter and service-price components help traders understand whether inflation pressure is concentrated in volatile categories or is becoming more broadly distributed.

Cross-Asset Confirmation Matters

The initial simultaneous declines in US500 and gold were consistent with a more hawkish interpretation of the inflation data.

Measured Movement Is Not Guaranteed Profit

The 48-tick US500 and 19-point XAU/USD moves represent measured historical price movement. Actual execution can differ materially due to latency, spreads, liquidity, slippage, order type and execution venue.

HAAWKS Conclusion

The August CPI report delivered a more nuanced result than the headline number alone suggested.

Headline CPI increased 0.4%, broadly matching market expectations, while annual inflation stood at 3.4%.

The key market-moving surprise was core CPI, which increased 0.3% month over month against expectations for 0.2%.

Energy also accelerated, with gasoline increasing 3.9%, while shelter prices rose 0.3%.

HAAWKS measured an immediate 48-tick decline in US500 and 19-point decline in XAU/USD following the release.

For professional news traders, the release demonstrates why receiving only the headline CPI figure is not enough. Headline CPI, core CPI, expectations and individual components need to be processed together to identify the actual surprise and understand the market's initial interpretation.

Trade smart. Stay informed. Stay ahead.

Built for Professional News Traders

HAAWKS G4A provides low-latency machine-readable data for U.S. macroeconomic and commodity releases, together with macroeconomic data from Norway, Sweden, Switzerland and Turkey, as well as ECB interest-rate decisions and statements.

All data is machine readable and available via API access in Chicago, New York and London. Free trials are available for qualified professionals.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Labor Statistics — Consumer Price Index, August 2026
    Official source for headline CPI, core CPI and detailed inflation components.
  2. HAAWKS internal tick-chart analysis — September 11, 2026
    Source for the measured immediate release-window movements of 48 ticks in US500 and 19 points in XAU/USD.
Disclaimer: This material is provided for informational and educational purposes only and does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific measures and should not be treated as standardized financial returns. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

August 2026 NFP Surprise: US500 Drops 68 Ticks and Gold Falls 57 Points

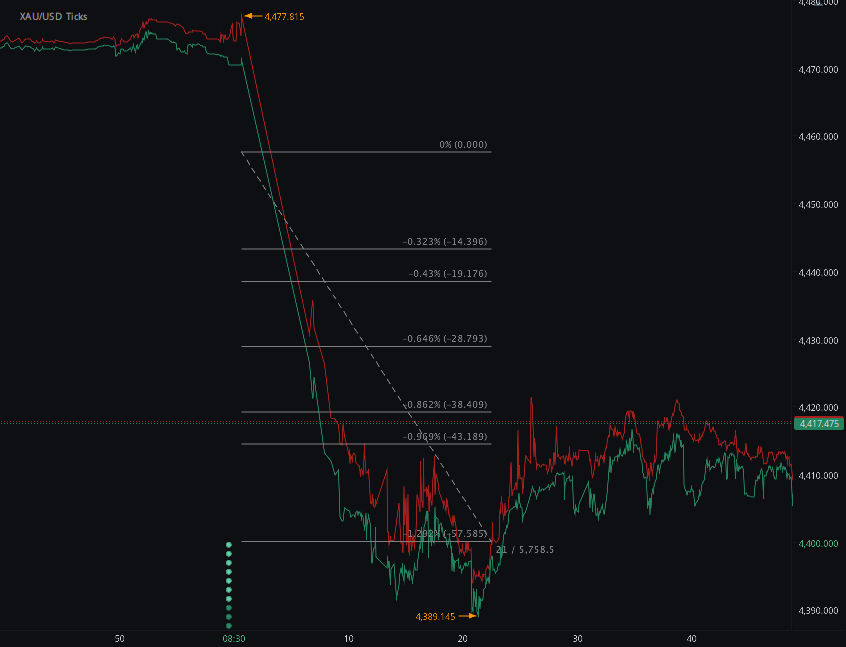
According to our analysis XAUUSD (spot gold) moved 57 points and US500 moved 68 ticks on US Employment Situation (Non-farm payrolls / NFP) data on 4 September 2026.

XAUUSD (57 points)

US500 (68 ticks)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

August NFP Surprise Sends US500 Down 68 Ticks and Gold Down 57 Points

U.S. payroll growth nearly tripled expectations, triggering a rapid hawkish repricing across rate-sensitive markets as traders increased expectations for a September Federal Reserve rate hike.

September 4, 2026 • Release time: 8:30 a.m. ET • U.S. Employment Situation

The August 2026 U.S. Employment Situation delivered a major upside surprise for news traders. Nonfarm payroll employment increased by 162,000, almost three times the 56,000 consensus forecast.

The unemployment rate remained unchanged at 4.1%, while labor-force participation recovered to 61.6%. Previous payroll estimates were also revised higher, strengthening the overall labor-market signal.

The immediate market response was notably different from the weak July jobs report. Instead of falling yields, dollar weakness and stronger gold, the August data prompted traders to price a greater probability of tighter Federal Reserve policy.

HAAWKS release-window analysis: US500 moved approximately 68 ticks lower, while XAU/USD fell approximately 57 points as the stronger-than-expected employment report drove a rapid hawkish repricing.

August NFP: Estimates vs. Actual

Nonfarm Payrolls +162K Consensus: +56K
Unemployment Rate 4.1% Consensus: 4.1%
Wage Growth YoY 3.1% July: 3.2%
June + July Revisions +55K Combined upward revision
Labor Indicator Expectation / Prior Actual HAAWKS News-Trader Read
Nonfarm Payrolls +56K expected +162K A 106K upside surprise and the strongest headline component of the release.
Unemployment Rate 4.1% expected 4.1% Unchanged and in line with consensus.
Labor Force Participation 61.4% prior 61.6% Participation rebounded while the labor force expanded, strengthening the quality of the headline result.
Average Hourly Earnings MoM — +0.3% Wage growth remained moderate despite the payroll surge.
Average Hourly Earnings YoY 3.0% expected 3.1% Slightly above consensus, but slower than July's 3.2%.
June + July Revisions Previously reported levels +55K Upward revisions reinforced the stronger current-month signal.

The Revisions Added to the Surprise

The payroll headline was already substantially stronger than expected, but the revisions made the release more hawkish.

June payroll growth was revised up by 11,000, from +20,000 to +31,000. July was revised up by 44,000, transforming the previously reported −23,000 decline into a +21,000 increase.

Together, the two prior months contained 55,000 more jobs than previously reported.

HAAWKS view: this was not simply a +162K headline. News traders received a large upside surprise in current payrolls, an increase in participation and positive revisions to both prior months. Several important employment fields therefore reinforced the same stronger-labor-market signal.

Immediate Market Reaction

HAAWKS tick-chart analysis captured a sharp downside reaction in both U.S. equities and gold immediately following the 8:30 a.m. ET release.

US500 −68 Ticks Strong jobs data increased expectations for tighter Fed policy
XAU/USD −57 Points Rising yields and a stronger dollar pressured gold
Market Measured Reaction Direction News-Trader Interpretation
US500 68 ticks Lower The stronger jobs report increased expectations that the Fed could tighten monetary policy, creating a "good news is bad news" response in equities.
XAU/USD 57 points Lower Higher Treasury yields, a stronger dollar and increased Fed hike expectations reduced demand for non-yielding gold.

Why Did US500 and Gold Fall?

Payrolls Beat by 106K

Economists expected only 56,000 new jobs. The 162,000 actual result created a very large upside surprise for algorithmic and discretionary news traders to process.

Prior Months Were Revised Higher

June and July payroll growth was revised up by 55,000 combined. That reduced concerns that the previous slowdown represented a rapidly deteriorating labor market.

Participation Improved

Labor-force participation rose from 61.4% to 61.6% while unemployment remained at 4.1%. The labor force increased substantially during the month.

Fed Hike Expectations Increased

The strong labor data gave policymakers more room to focus on inflation. Rate markets increased the probability of a September Federal Reserve rate hike after the release.

Where the Jobs Came From

The employment rebound was concentrated in several areas that had been weak in previous months.

Industry August Employment Change HAAWKS Read-Through
Food Services & Drinking Places +59K The largest highlighted source of employment growth.
Local Government Education +42K Largely reversed the prior month's decline.
Construction +22K BLS characterized overall construction employment as little changed, with strength in nonresidential specialty trades.
Manufacturing +16K Continued an upward employment trend.
Health Care +13K Continued to add jobs, although below its prior 12-month average pace.
Information −23K The principal highlighted sector showing employment losses.

Strong Jobs, but Wage Inflation Stayed Moderate

One feature prevented the report from being uniformly inflationary. Average hourly earnings increased by 0.3% month over month and 3.1% year over year.

Annual wage growth therefore slowed slightly from July's 3.2%. That distinction mattered because the report showed stronger employment without a corresponding acceleration in wage inflation.

For news traders, this created an important second layer to the release. The payroll and revision fields were clearly hawkish, while the wage data provided a modest counterweight.

The Fed Repricing

Before the report, markets were already debating whether persistent inflation could force the Federal Reserve to raise rates at its September meeting.

The stronger employment data increased the probability of a rate hike. Reuters reported that short-term rate futures moved to imply roughly a 59% probability of a September increase immediately after the report, compared with approximately 55% beforehand.

Treasury yields rose and the U.S. dollar strengthened. Those moves created a difficult combination for both gold and rate-sensitive equities.

News-trader takeaway: the market was not trading +162K jobs in isolation. It was trading the impact of +162K payrolls, +55K in revisions, stronger participation and steady unemployment on the expected path of Federal Reserve policy.

What This Release Shows News Traders

Consensus Matters as Much as the Actual Number

A +162K payroll result means little without knowing that the market expected only +56K. The surprise relative to expectations was the immediate trading catalyst.

Revisions Can Strengthen or Reverse a Signal

July had originally been reported as a 23,000 employment decline. The September release revised that result to a 21,000 increase. That 44,000 adjustment materially changed the historical employment picture.

Multiple Fields Need to Be Processed Together

Payrolls, unemployment, participation, wages and prior-month revisions arrived as part of the same release. Professional news-trading systems therefore benefit from receiving the complete data set rather than only the headline NFP number.

Good Economic News Can Be Bad Market News

Stronger employment would normally be supportive for economic growth, but in an environment where traders are focused on inflation and monetary policy, stronger data can increase expected interest rates and pressure equities and gold.

Execution Risk Remains Critical

The 68-tick US500 and 57-point XAU/USD figures represent measured historical price movement, not guaranteed executable profit. Spreads, liquidity, slippage, order type, venue and data latency can materially affect actual trading results.

What Comes Next?

Following the strong employment report, attention shifted immediately toward U.S. inflation data and the September Federal Reserve meeting. With labor-market weakness becoming less of a constraint, inflation readings gained even greater importance for the policy decision.

The next U.S. Employment Situation, covering September 2026, is scheduled for Friday, October 2, 2026 at 8:30 a.m. ET.

HAAWKS Conclusion

The August 2026 Employment Situation delivered a substantially stronger U.S. labor-market signal than traders had expected.

Nonfarm payrolls increased by 162,000 against a consensus forecast of only 56,000. The unemployment rate remained at 4.1%, participation increased to 61.6%, and June and July payroll growth was revised higher by a combined 55,000 jobs.

The release strengthened expectations that the Federal Reserve could tighten policy in September. Treasury yields and the dollar moved higher, while rate-sensitive assets came under immediate pressure.

HAAWKS measured approximately 68 ticks of downside movement in US500 and 57 points in XAU/USD following the release.

For professional news traders, the event demonstrates why low-latency access to both the headline number and the supporting data fields is important. Payrolls, expectations, revisions, wages, unemployment and participation combined to determine the market interpretation within seconds.

Trade smart. Stay informed. Stay ahead.

Built for Professional News Traders

HAAWKS G4A provides low-latency machine-readable data for U.S. macroeconomic and commodity releases, together with macroeconomic data from Norway, Sweden, Switzerland and Turkey, as well as ECB interest-rate decisions and statements.

All data is machine readable and available via API access in Chicago, New York and London. Free trials are available for qualified professionals.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Labor Statistics — Employment Situation, August 2026
    Official source for payroll employment, unemployment, participation, wages, industry employment and payroll revisions.
  2. Reuters — U.S. job growth expected to rebound in August
    Used for the pre-release economist consensus of +56K payrolls, 4.1% unemployment and 3.0% annual wage growth.
  3. Reuters — U.S. nonfarm payrolls surge in August
    Used for post-release labor-market and Federal Reserve context.
  4. Reuters — Strong August jobs report sends yields higher
    Used for immediate rates, dollar, equities and gold market reaction.
  5. Reuters — Gold slides after robust U.S. payrolls
    Used for gold-market and Federal Reserve rate-expectation context.
  6. HAAWKS internal tick-chart analysis — September 4, 2026
    Used for the measured release-window movements in US500 and XAU/USD.
Disclaimer: This material is provided for informational and educational purposes only. It does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific and should not be treated as standardized financial returns. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.
Comment