Viewing entries tagged
Non-Farm Payrolls

Comment

August 2026 NFP Surprise: US500 Drops 68 Ticks and Gold Falls 57 Points

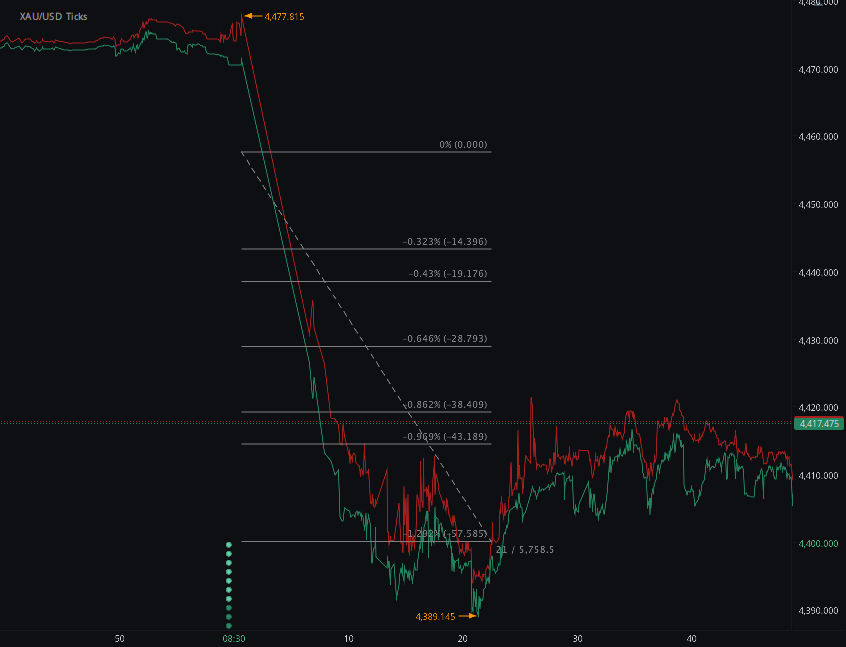
According to our analysis XAUUSD (spot gold) moved 57 points and US500 moved 68 ticks on US Employment Situation (Non-farm payrolls / NFP) data on 4 September 2026.

XAUUSD (57 points)
US500 (68 ticks)
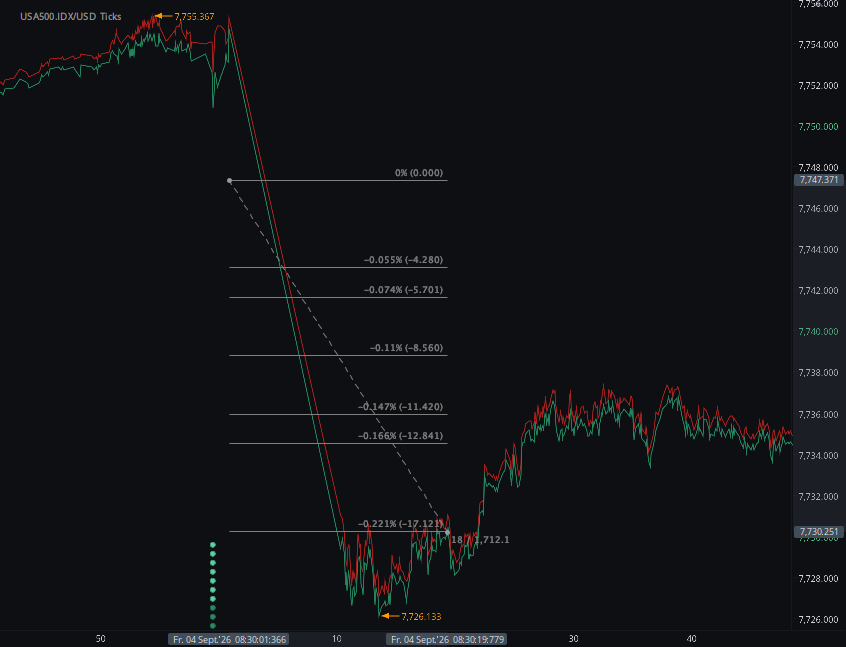
Charts are exported from JForex (Dukascopy).


HAAWKS Research

August NFP Surprise Sends US500 Down 68 Ticks and Gold Down 57 Points

U.S. payroll growth nearly tripled expectations, triggering a rapid hawkish repricing across rate-sensitive markets as traders increased expectations for a September Federal Reserve rate hike.

September 4, 2026 • Release time: 8:30 a.m. ET • U.S. Employment Situation

The August 2026 U.S. Employment Situation delivered a major upside surprise for news traders. Nonfarm payroll employment increased by 162,000, almost three times the 56,000 consensus forecast.

The unemployment rate remained unchanged at 4.1%, while labor-force participation recovered to 61.6%. Previous payroll estimates were also revised higher, strengthening the overall labor-market signal.

The immediate market response was notably different from the weak July jobs report. Instead of falling yields, dollar weakness and stronger gold, the August data prompted traders to price a greater probability of tighter Federal Reserve policy.

HAAWKS release-window analysis: US500 moved approximately 68 ticks lower, while XAU/USD fell approximately 57 points as the stronger-than-expected employment report drove a rapid hawkish repricing.

August NFP: Estimates vs. Actual

Nonfarm Payrolls +162K Consensus: +56K
Unemployment Rate 4.1% Consensus: 4.1%
Wage Growth YoY 3.1% July: 3.2%
June + July Revisions +55K Combined upward revision
Labor Indicator Expectation / Prior Actual HAAWKS News-Trader Read
Nonfarm Payrolls +56K expected +162K A 106K upside surprise and the strongest headline component of the release.
Unemployment Rate 4.1% expected 4.1% Unchanged and in line with consensus.
Labor Force Participation 61.4% prior 61.6% Participation rebounded while the labor force expanded, strengthening the quality of the headline result.
Average Hourly Earnings MoM — +0.3% Wage growth remained moderate despite the payroll surge.
Average Hourly Earnings YoY 3.0% expected 3.1% Slightly above consensus, but slower than July's 3.2%.
June + July Revisions Previously reported levels +55K Upward revisions reinforced the stronger current-month signal.

The Revisions Added to the Surprise

The payroll headline was already substantially stronger than expected, but the revisions made the release more hawkish.

June payroll growth was revised up by 11,000, from +20,000 to +31,000. July was revised up by 44,000, transforming the previously reported −23,000 decline into a +21,000 increase.

Together, the two prior months contained 55,000 more jobs than previously reported.

HAAWKS view: this was not simply a +162K headline. News traders received a large upside surprise in current payrolls, an increase in participation and positive revisions to both prior months. Several important employment fields therefore reinforced the same stronger-labor-market signal.

Immediate Market Reaction

HAAWKS tick-chart analysis captured a sharp downside reaction in both U.S. equities and gold immediately following the 8:30 a.m. ET release.

US500 −68 Ticks Strong jobs data increased expectations for tighter Fed policy
XAU/USD −57 Points Rising yields and a stronger dollar pressured gold
Market Measured Reaction Direction News-Trader Interpretation
US500 68 ticks Lower The stronger jobs report increased expectations that the Fed could tighten monetary policy, creating a "good news is bad news" response in equities.
XAU/USD 57 points Lower Higher Treasury yields, a stronger dollar and increased Fed hike expectations reduced demand for non-yielding gold.

Why Did US500 and Gold Fall?

Payrolls Beat by 106K

Economists expected only 56,000 new jobs. The 162,000 actual result created a very large upside surprise for algorithmic and discretionary news traders to process.

Prior Months Were Revised Higher

June and July payroll growth was revised up by 55,000 combined. That reduced concerns that the previous slowdown represented a rapidly deteriorating labor market.

Participation Improved

Labor-force participation rose from 61.4% to 61.6% while unemployment remained at 4.1%. The labor force increased substantially during the month.

Fed Hike Expectations Increased

The strong labor data gave policymakers more room to focus on inflation. Rate markets increased the probability of a September Federal Reserve rate hike after the release.

Where the Jobs Came From

The employment rebound was concentrated in several areas that had been weak in previous months.

Industry August Employment Change HAAWKS Read-Through
Food Services & Drinking Places +59K The largest highlighted source of employment growth.
Local Government Education +42K Largely reversed the prior month's decline.
Construction +22K BLS characterized overall construction employment as little changed, with strength in nonresidential specialty trades.
Manufacturing +16K Continued an upward employment trend.
Health Care +13K Continued to add jobs, although below its prior 12-month average pace.
Information −23K The principal highlighted sector showing employment losses.

Strong Jobs, but Wage Inflation Stayed Moderate

One feature prevented the report from being uniformly inflationary. Average hourly earnings increased by 0.3% month over month and 3.1% year over year.

Annual wage growth therefore slowed slightly from July's 3.2%. That distinction mattered because the report showed stronger employment without a corresponding acceleration in wage inflation.

For news traders, this created an important second layer to the release. The payroll and revision fields were clearly hawkish, while the wage data provided a modest counterweight.

The Fed Repricing

Before the report, markets were already debating whether persistent inflation could force the Federal Reserve to raise rates at its September meeting.

The stronger employment data increased the probability of a rate hike. Reuters reported that short-term rate futures moved to imply roughly a 59% probability of a September increase immediately after the report, compared with approximately 55% beforehand.

Treasury yields rose and the U.S. dollar strengthened. Those moves created a difficult combination for both gold and rate-sensitive equities.

News-trader takeaway: the market was not trading +162K jobs in isolation. It was trading the impact of +162K payrolls, +55K in revisions, stronger participation and steady unemployment on the expected path of Federal Reserve policy.

What This Release Shows News Traders

Consensus Matters as Much as the Actual Number

A +162K payroll result means little without knowing that the market expected only +56K. The surprise relative to expectations was the immediate trading catalyst.

Revisions Can Strengthen or Reverse a Signal

July had originally been reported as a 23,000 employment decline. The September release revised that result to a 21,000 increase. That 44,000 adjustment materially changed the historical employment picture.

Multiple Fields Need to Be Processed Together

Payrolls, unemployment, participation, wages and prior-month revisions arrived as part of the same release. Professional news-trading systems therefore benefit from receiving the complete data set rather than only the headline NFP number.

Good Economic News Can Be Bad Market News

Stronger employment would normally be supportive for economic growth, but in an environment where traders are focused on inflation and monetary policy, stronger data can increase expected interest rates and pressure equities and gold.

Execution Risk Remains Critical

The 68-tick US500 and 57-point XAU/USD figures represent measured historical price movement, not guaranteed executable profit. Spreads, liquidity, slippage, order type, venue and data latency can materially affect actual trading results.

What Comes Next?

Following the strong employment report, attention shifted immediately toward U.S. inflation data and the September Federal Reserve meeting. With labor-market weakness becoming less of a constraint, inflation readings gained even greater importance for the policy decision.

The next U.S. Employment Situation, covering September 2026, is scheduled for Friday, October 2, 2026 at 8:30 a.m. ET.

HAAWKS Conclusion

The August 2026 Employment Situation delivered a substantially stronger U.S. labor-market signal than traders had expected.

Nonfarm payrolls increased by 162,000 against a consensus forecast of only 56,000. The unemployment rate remained at 4.1%, participation increased to 61.6%, and June and July payroll growth was revised higher by a combined 55,000 jobs.

The release strengthened expectations that the Federal Reserve could tighten policy in September. Treasury yields and the dollar moved higher, while rate-sensitive assets came under immediate pressure.

HAAWKS measured approximately 68 ticks of downside movement in US500 and 57 points in XAU/USD following the release.

For professional news traders, the event demonstrates why low-latency access to both the headline number and the supporting data fields is important. Payrolls, expectations, revisions, wages, unemployment and participation combined to determine the market interpretation within seconds.

Trade smart. Stay informed. Stay ahead.

Built for Professional News Traders

HAAWKS G4A provides low-latency machine-readable data for U.S. macroeconomic and commodity releases, together with macroeconomic data from Norway, Sweden, Switzerland and Turkey, as well as ECB interest-rate decisions and statements.

All data is machine readable and available via API access in Chicago, New York and London. Free trials are available for qualified professionals.

Explore HAAWKS G4A Low-Latency Data

Sources

  1. U.S. Bureau of Labor Statistics — Employment Situation, August 2026
    Official source for payroll employment, unemployment, participation, wages, industry employment and payroll revisions.
  2. Reuters — U.S. job growth expected to rebound in August
    Used for the pre-release economist consensus of +56K payrolls, 4.1% unemployment and 3.0% annual wage growth.
  3. Reuters — U.S. nonfarm payrolls surge in August
    Used for post-release labor-market and Federal Reserve context.
  4. Reuters — Strong August jobs report sends yields higher
    Used for immediate rates, dollar, equities and gold market reaction.
  5. Reuters — Gold slides after robust U.S. payrolls
    Used for gold-market and Federal Reserve rate-expectation context.
  6. HAAWKS internal tick-chart analysis — September 4, 2026
    Used for the measured release-window movements in US500 and XAU/USD.
Disclaimer: This material is provided for informational and educational purposes only. It does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The price movements described are historical measured market reactions and do not represent guaranteed or necessarily achievable trading profits. Tick and point values are instrument-specific and should not be treated as standardized financial returns. Actual trading results depend on data latency, processing latency, liquidity, spreads, slippage, order type, execution venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for financial institutions.

Comment

Comment

July 2026 NFP Shock: 23K Job Loss Triggers Sharp Moves in FX, Gold and US500

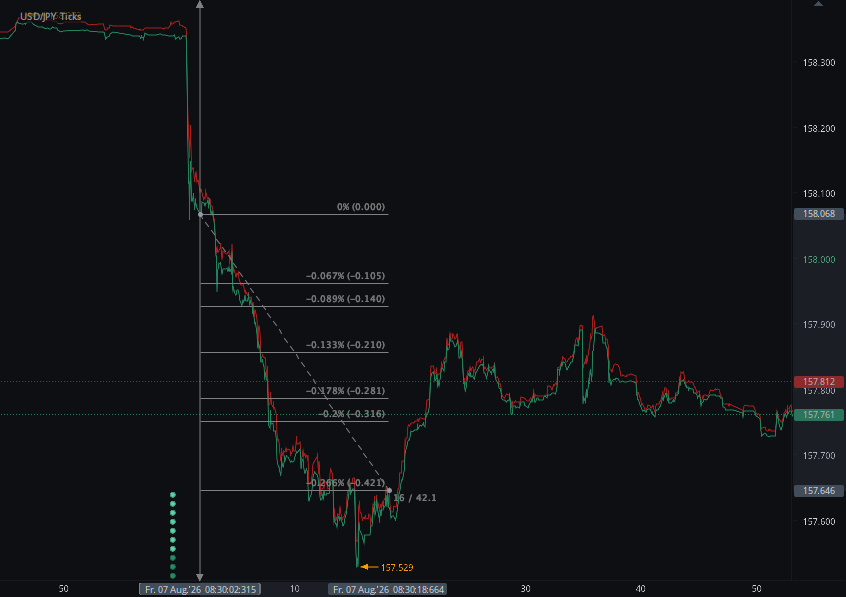
According to our analysis USDJPY moved 42 pips, EURUSD moved 19 pips, XAUUSD (spot gold) moved 17 points and US500 moved 56 ticks (117 ticks total) on US Employment Situation (Non-farm payrolls / NFP) data on 7 August 2026.

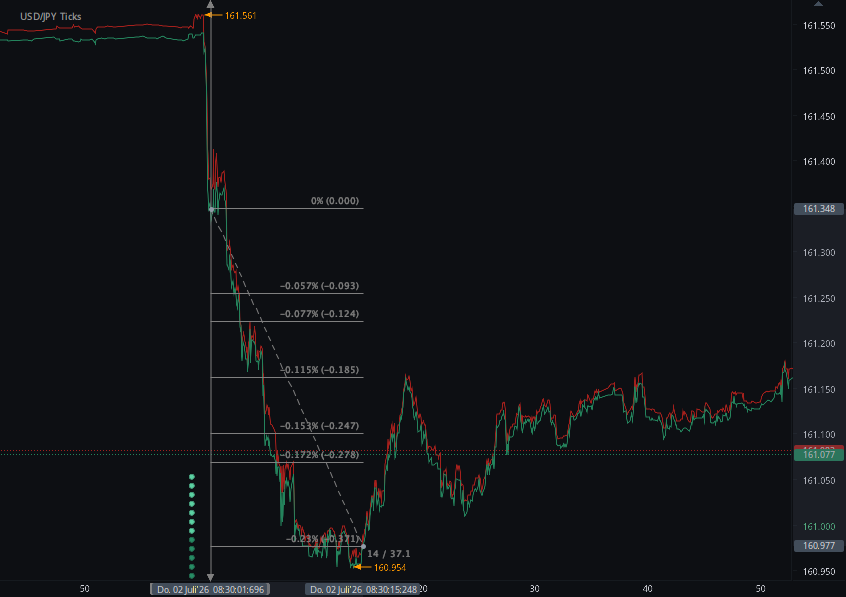
USDJPY (42 pips)

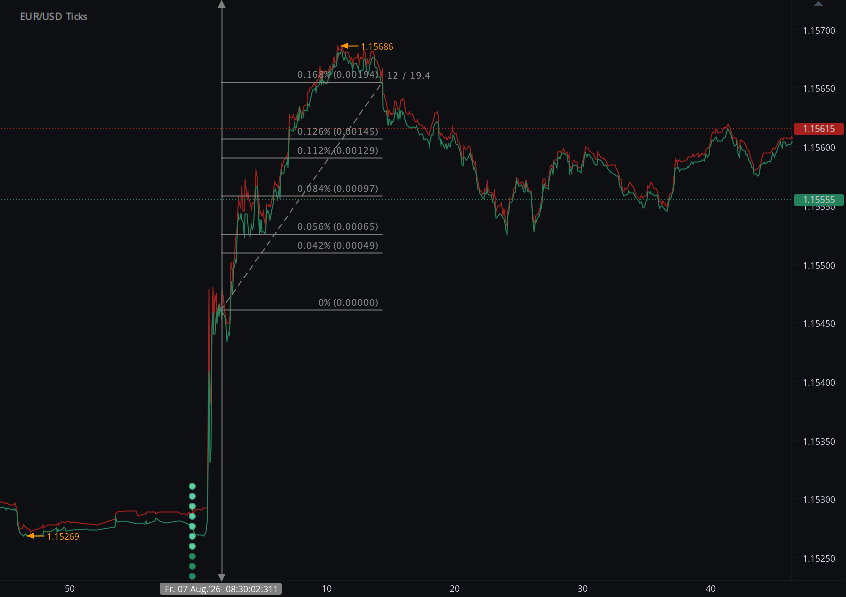
EURUSD (19 pips)

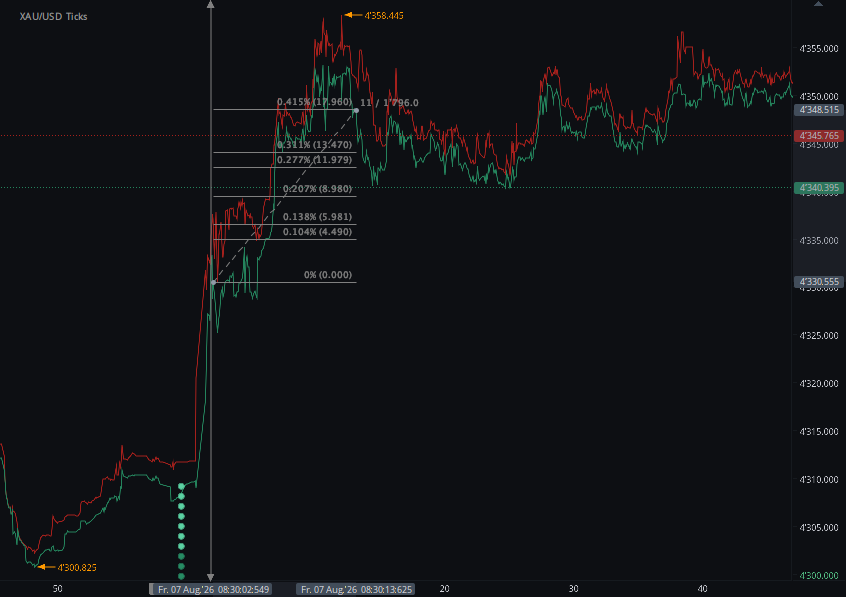
XAUUSD (17 points)

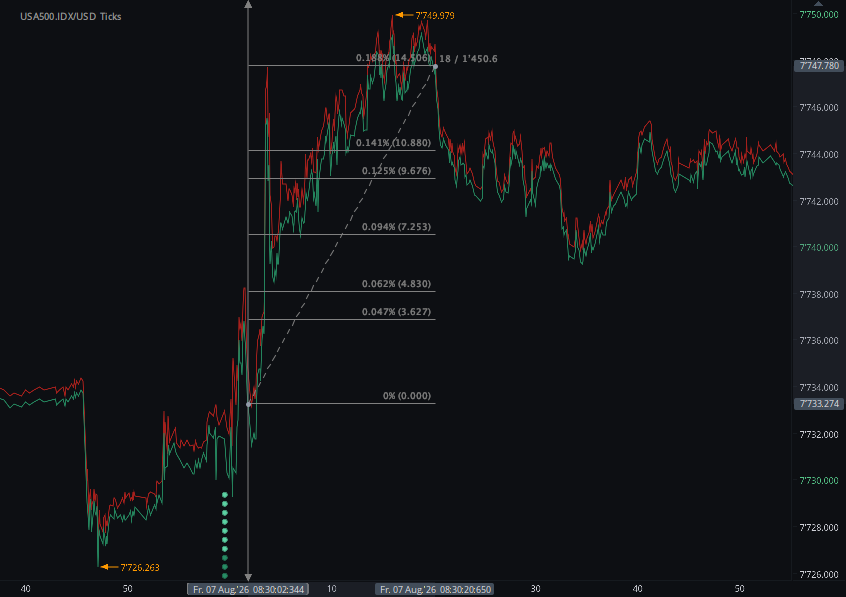
US500 (56 ticks)

Charts are exported from JForex (Dukascopy).


HAAWKS Research

July 2026 NFP Shock: Payrolls Fall 23K as Markets Reprice the Fed

A surprise contraction in U.S. payrolls, weaker wage growth and another round of large downward revisions triggered rapid moves across FX, gold and U.S. equity indices.

August 7, 2026 • Release time: 8:30 a.m. ET • U.S. Employment Situation

The July 2026 U.S. Employment Situation delivered a significantly weaker labor-market signal than news traders had expected. Nonfarm payrolls declined by 23,000, compared with a Reuters consensus forecast for an 80,000 increase.

The unemployment rate fell from 4.2% to 4.1%, but the improvement in the headline rate came alongside another decline in labor force participation. The participation rate slipped to 61.4%, while the civilian labor force contracted by 264,000.

For news traders, the details behind the headline were arguably even more important. May and June payroll growth was revised lower by a combined 103,000 jobs, while annual average hourly earnings growth slowed to 3.2%.

HAAWKS first read: this was not simply a weak headline NFP print. The combination of a 103,000-job downside surprise versus consensus, substantial prior-month revisions, softer wage growth and weaker labor-force participation produced a distinctly dovish labor-market signal.

NFP Estimates vs. Actual Release

Nonfarm Payrolls −23K Reuters consensus: +80K
Unemployment Rate 4.1% Forecast: 4.2%
Wage Growth YoY 3.2% Forecast: 3.5%
Prior Revisions −103K May + June combined
July 2026 U.S. Employment Situation estimates compared with actual results
Labor Indicator Expectation Actual HAAWKS News-Trader Read
Nonfarm Payrolls +80K −23K A 103K downside surprise versus consensus and the primary negative headline for the dollar.
Unemployment Rate 4.2% 4.1% Better on the surface, but less supportive once the decline in labor-force participation was taken into account.
Average Hourly Earnings YoY 3.5% 3.2% Softer wage pressure reinforced the dovish interpretation of the employment report.
Labor Force Participation — 61.4% Participation edged down from 61.5%, helping explain why the unemployment rate fell despite weak employment conditions.
May Payroll Revision Previous: +129K +63K Revised lower by 66K.
June Payroll Revision Previous: +57K +20K Revised lower by 37K.

Immediate Market Reaction

The HAAWKS release-window measurements show how quickly the labor-market surprise was incorporated into prices. The initial response was consistent across the major macro markets: the U.S. dollar weakened, gold rallied and U.S. equities moved higher as traders reduced expectations for near-term Federal Reserve tightening.

USD/JPY −42.1 pips 16 seconds
EUR/USD +19.4 pips 12 seconds
XAU/USD +17.96 points 11 seconds
US500 +14.6 points 18 seconds
Immediate market reaction following the July 2026 NFP release
Market Measured Move Time Window Direction News-Trader Interpretation
USD/JPY 42.1 pips 16 seconds Lower The strongest measured FX reaction as the weak employment figures triggered rapid dollar selling against the yen.
EUR/USD 19.4 pips 12 seconds Higher Broad dollar weakness pushed the euro higher immediately after the release.
XAU/USD 17.96 points 11 seconds Higher Gold reacted quickly to lower yields, dollar weakness and a reduction in expected Federal Reserve tightening.
US500 14.6 index points 18 seconds Higher Equity traders initially focused on the lower-rate implications of the employment miss rather than the negative growth signal.

Why This Release Mattered to News Traders

1. The Headline Surprise Was Large

Payrolls were expected to rise by 80,000 but instead declined by 23,000. For automated and discretionary news traders, the 103,000-job gap versus consensus immediately changed the macro interpretation of the release.

2. Revisions Reinforced the Signal

May and June were revised down by a combined 103,000 jobs. That mattered because the release did not just report a weak July; it also showed that the preceding labor-market picture had been weaker than initially reported.

3. Unemployment Sent a Mixed Message

A fall in unemployment to 4.1% would ordinarily be interpreted as labor-market strength. However, the labor force shrank and participation slipped to 61.4%, reducing the positive impact of the headline unemployment rate.

4. Wage Growth Also Missed

Annual average hourly earnings growth slowed to 3.2% versus the 3.5% rate economists had expected. For rate-sensitive markets, softer wages added another dovish element to an already weak payroll report.

HAAWKS view: for news traders, this was a release where the components largely pointed in the same direction. The headline payroll miss, negative revisions and softer wage growth outweighed the lower unemployment rate. The result was a fast cross-asset repricing: USD lower, gold higher and equities higher.

Sector Detail: Where the Jobs Were Lost

The weakness was not evenly distributed across the economy. Local government education employment declined by 50,000, while retail trade lost 19,000 jobs. Financial activities employment continued to trend lower, falling by 14,000.

Health care remained one of the few areas of continued employment growth, adding 22,000 jobs during July, although that was slower than its average monthly gain over the previous year.

Selected July 2026 employment changes by industry
Industry July Change HAAWKS Read-through
Local Government Education −50K The largest highlighted sector decline in the July report.
Retail Trade −19K Added to the evidence of weaker overall hiring momentum.
Financial Activities −14K Continued an existing downward employment trend.
Health Care +22K Continued to add jobs, but at a slower pace than its prior 12-month average.

The Fed Repricing

Before the release, markets were debating whether persistent inflation could lead the Federal Reserve to raise rates at its September meeting. The unexpectedly weak jobs report materially reduced that probability.

That shift helps explain why assets that normally benefit from lower interest-rate expectations reacted so quickly. Treasury yields fell, the U.S. dollar weakened, gold advanced and U.S. stock futures initially rallied.

For news traders, the key point is that the market was not trading the payroll number in isolation. It was trading how the employment surprise changed the expected path of monetary policy.

News Trading Takeaways

Headline Data Is Only the First Layer

A fast NFP strategy must be able to process more than the payroll headline. Unemployment, wage growth and revisions can either confirm or contradict the initial signal.

Revisions Can Be Market-Moving

The 103,000 combined downward revision to May and June strengthened the bearish labor-market message. In some releases, prior-period revisions can matter as much as the current month's number.

Cross-Asset Confirmation Matters

USD/JPY lower, EUR/USD higher, gold higher and US500 higher represented a coherent initial macro reaction. When several rate-sensitive markets respond in the same direction, news traders receive useful confirmation of the market's interpretation.

Execution Risk Remains Critical

A measured market move is not the same as an achievable trading result. During high-impact releases, spreads can widen, liquidity can disappear, prices can gap and slippage can increase. Latency, order type, venue and risk controls remain critical to actual execution.

HAAWKS Conclusion

The July 2026 NFP release delivered a much weaker labor-market picture than traders had expected.

Nonfarm payrolls declined by 23,000 versus expectations for an 80,000 increase. May and June were revised down by another 103,000 jobs, while annual wage growth slowed to 3.2%.

Although unemployment fell to 4.1%, declining labor-force participation reduced the strength of that signal. The broader message from the report was therefore clearly softer than the headline unemployment rate alone suggested.

The immediate market reaction reflected that interpretation. HAAWKS measured 42.1 pips in USD/JPY in 16 seconds, 19.4 pips in EUR/USD in 12 seconds, 17.96 points in XAU/USD in 11 seconds and 14.6 index points in US500 in 18 seconds.

For news traders, the release is a useful example of why low-latency access to the complete data set matters. The payroll headline, unemployment rate, wage figures and revisions all arrived together and collectively determined the market's interpretation within seconds.

Trade smart. Stay informed. Stay ahead.

Built for News Traders

HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data directly from official sources for professional algorithmic and manual news trading.

Explore HAAWKS G4A Data Feeds

Sources

  1. U.S. Bureau of Labor Statistics — Employment Situation, July 2026
    Official source for nonfarm payrolls, unemployment, labor-force participation, earnings, industry employment and prior-month revisions.
  2. Reuters — U.S. job growth expected to pick up in July
    Used for the pre-release economist consensus of +80K payrolls, 4.2% unemployment and 3.5% annual wage growth.
  3. Reuters — U.S. suffers unexpected job losses in July
    Used for post-release labor-market and financial-market context.
  4. Reuters — Dollar drops after weak U.S. jobs data
    Used for broader FX and gold-market reaction following the report.
  5. Reuters — Markets reduce odds of September Fed rate hike
    Used for the post-NFP monetary-policy repricing.
  6. HAAWKS internal tick-chart analysis — August 7, 2026
    Used for the measured release-window reactions in USD/JPY, EUR/USD, XAU/USD and US500.
Disclaimer: This material is provided for informational and educational purposes only. It does not constitute financial advice, investment advice or a recommendation to buy or sell any financial instrument. The market moves described above are historical measured price reactions and do not represent guaranteed or necessarily achievable profits. Actual execution depends on latency, liquidity, spreads, slippage, order type, venue and risk management. Past market behavior is not indicative of future results.

Built for traders who compete on speed. HAAWKS G4A delivers low-latency, machine-readable macroeconomic and commodity data via API infrastructure in Chicago, New York and London. Explore the feed, share your feedback, or contact us to request a free trial for qualified professionals.

Comment

Comment

June 2026 NFP: Softer Payroll Growth Triggers Sharp Moves Across FX, Gold and US500 on US Employment Situation (NFP)

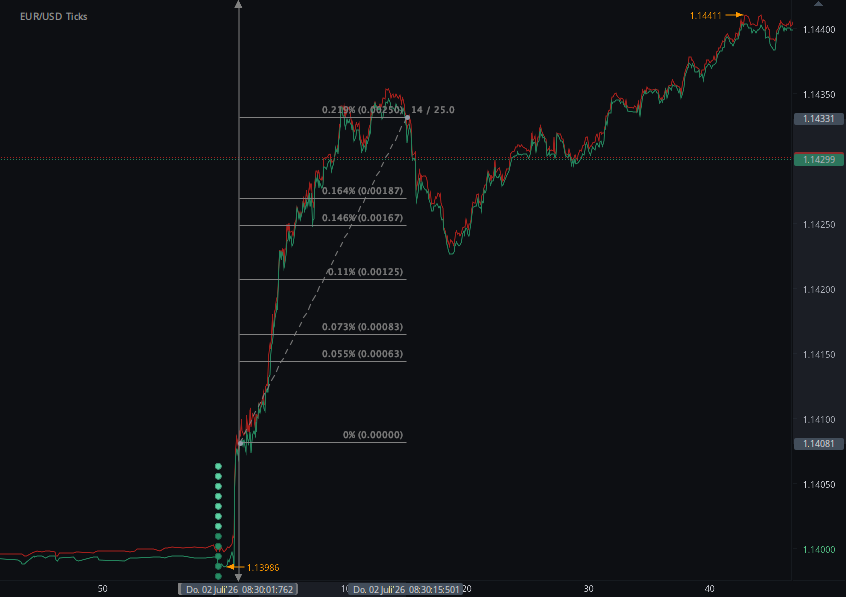
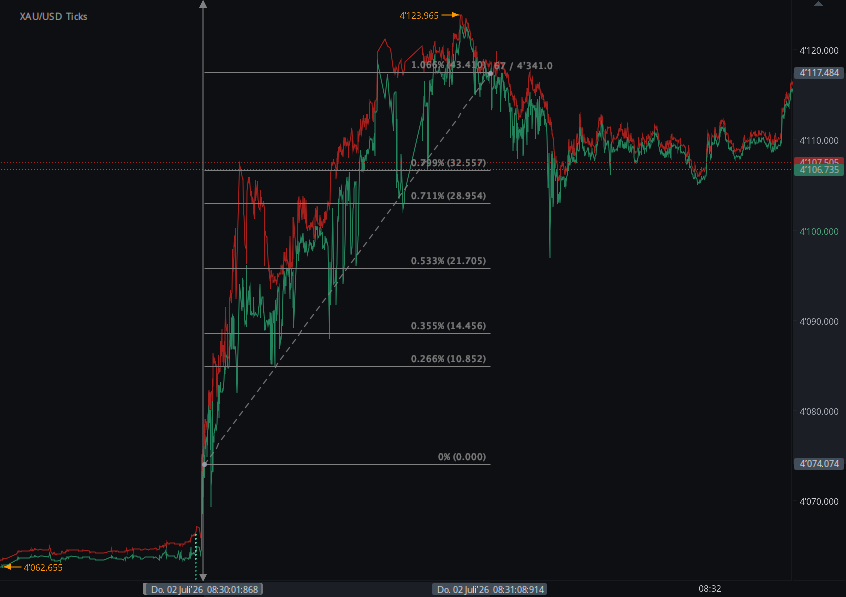
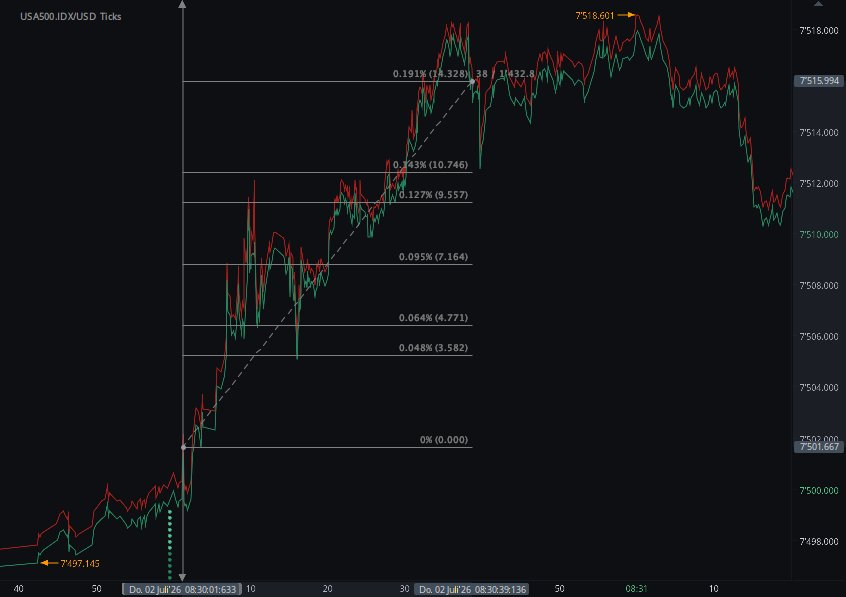
According to our analysis USDJPY moved 37 pips, EURUSD moved 25 pips, XAUUSD (spot gold) moved 43 points and US500 moved 56 ticks (118 ticks total) on US Employment Situation (Non-farm payrolls / NFP) data on 2 July 2026.

USDJPY (37 pips)

EURUSD (25 pips)

XAUUSD (43 points)

US500 (56 ticks)

Charts are exported from JForex (Dukascopy).


June 2026 NFP: Softer Jobs, Stable Wages, Sharp Market Reaction

HAAWKS Research | July 2, 2026

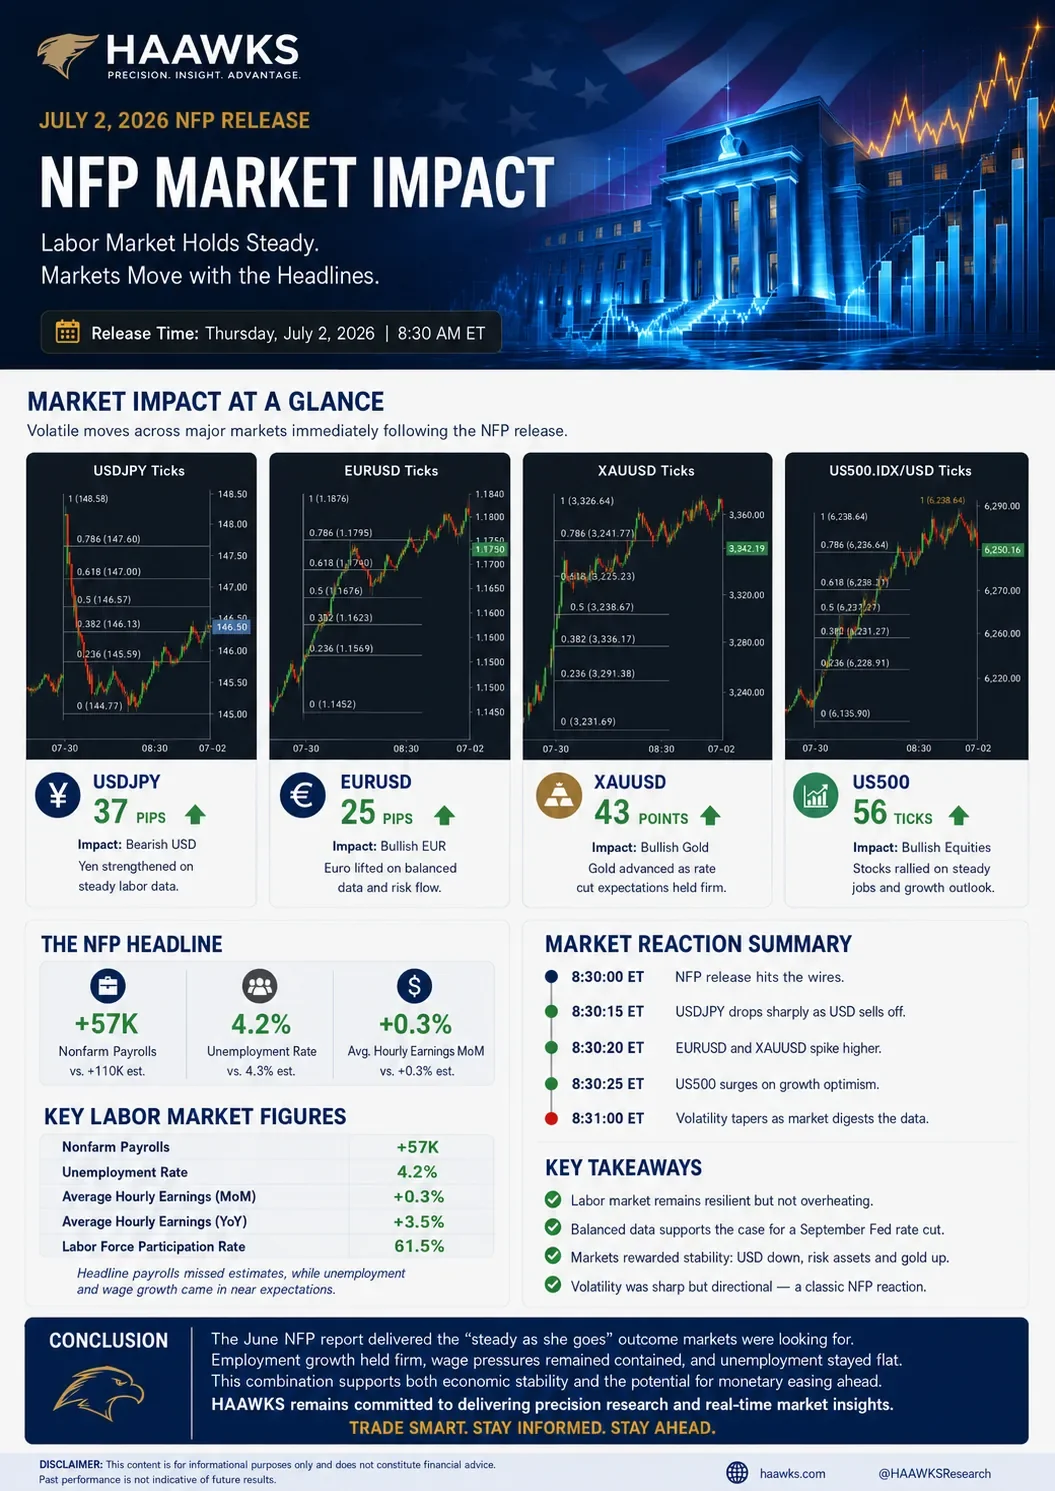
HAAWKS NFP market impact summary showing June 2026 labor market figures and release-window moves in USDJPY, EURUSD, XAUUSD, and US500

The June 2026 U.S. Nonfarm Payrolls release delivered a classic “soft but not broken” labor-market signal. Payroll growth slowed materially, but unemployment remained low and wage growth stayed contained. For markets, that combination was enough to trigger immediate volatility across FX, gold, and equity index futures.

The Bureau of Labor Statistics reported that total nonfarm payroll employment rose by 57,000 in June, while the unemployment rate stood at 4.2%. Average hourly earnings increased 0.3% month over month and 3.5% year over year. The prior two months were also revised lower by a combined 74,000 jobs, with April revised to +148,000 and May revised to +129,000.

Research Estimates vs. Actual Release

Ahead of the release, market expectations were for a stronger labor print. Consensus estimates pointed to nonfarm payrolls rising by roughly 110,000, unemployment near 4.3%, and average hourly earnings increasing 0.3% month over month.

The actual release came in softer on headline job creation, but broadly stable on unemployment and wages.

Indicator Estimate Actual HAAWKS Read-through
Nonfarm Payrolls +110K +57K Clear downside miss. Headline job creation came in softer than expected.
Unemployment Rate 4.3% 4.2% Better than expected, though the participation-rate decline softened the signal.
Average Hourly Earnings MoM +0.3% +0.3% In line. Wage growth remained contained.
Average Hourly Earnings YoY +3.5% +3.5% In line. No upside wage shock.
Prior-Month Revisions — -74K April and May were revised lower, pointing to softer labor momentum than previously reported.

The headline payroll miss was the main surprise. However, wage growth did not accelerate, unemployment remained low, and the report avoided the kind of broad deterioration that would suggest an immediate labor-market break.

Market Impact: HAAWKS Tick-Chart Reaction

The HAAWKS market-impact screenshots captured the immediate release-window volatility:

Market Measured Impact Direction HAAWKS Interpretation
USD/JPY 37 pips Lower The U.S. dollar sold off sharply against the yen after the softer payroll print.
EUR/USD 25 pips Higher The euro rallied as dollar weakness spread across major FX pairs.
XAU/USD 43 points Higher Gold rallied as traders repriced rate expectations following the weaker jobs number.
US500 56 ticks Higher Equities initially caught a bid as slower job growth supported the soft-landing narrative.

The market reaction was consistent with a softer-than-expected labor report. The U.S. dollar weakened, gold rallied, and equities reacted positively to the possibility that slower job growth could reduce pressure on the Federal Reserve to keep policy restrictive for longer.

Sector Detail: Slower Hiring, Not a Full Breakdown

The report showed continued job gains in professional and business services, social assistance, and health care, while leisure and hospitality lost 61,000 jobs. That divergence matters. It suggests the labor market is not uniformly weak, but momentum is becoming narrower.

The downward revisions were also important. A one-month payroll miss can be dismissed as noise; a miss combined with negative revisions tells a more cautious story. The labor market still appears functional, but the pace of hiring is clearly cooling.

HAAWKS Conclusion

The June NFP release was not a recession signal, but it was a warning that the labor market is losing speed.

For traders, the key takeaway was not simply that payrolls missed. It was the combination of:

Soft job creation, stable wages, lower unemployment, and negative revisions.

That mix created a “Goldilocks” reaction in markets: weak enough to pressure the dollar and support rate-sensitive assets, but not weak enough to trigger immediate risk-off panic.

Asset Class Reaction Why It Moved Trading Takeaway
FX Dollar weaker The headline payroll miss reduced near-term support for the U.S. dollar. USD vulnerability remained the cleanest immediate signal.
Gold Gold stronger Softer labor data supported lower-rate sensitivity and demand for precious metals. XAU/USD remained supported while rate-cut expectations held firm.
Equities Risk initially bid Stable wages and softer hiring helped support the soft-landing view. US500 strength reflected relief rather than a broad growth acceleration signal.
Rates Narrative Dovish lean The report was soft enough to support easing expectations, but not weak enough to trigger panic. The market reaction fit a classic “Goldilocks” setup.

The HAAWKS read:

USD vulnerability remains the cleanest short-term signal, while gold and equity indices may continue to benefit if incoming data supports the view that inflation pressure is easing without a sharp employment shock.

Final Takeaway

The June 2026 NFP report reinforced a market theme that traders cannot ignore:

Labor momentum is cooling, wage pressure is stable, and markets are increasingly sensitive to every data point that affects the Fed path.

For HAAWKS traders, the opportunity is not just in the headline number. It is in understanding how that number moves liquidity, volatility, and cross-asset positioning in real time.

Trade smart. Stay informed. Stay ahead.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Sources

  1. U.S. Bureau of Labor Statistics — Employment Situation Summary, June 2026
    Used for the official NFP release figures, including +57K nonfarm payrolls, 4.2% unemployment, +0.3% monthly wage growth, +3.5% annual wage growth, labor-force participation, sector detail, and prior-month revisions.
  2. Reuters — U.S. job growth likely cooled in June after recent string of big gains
    Used for pre-release market expectations, including the +110K nonfarm payroll estimate and 4.3% unemployment forecast.
  3. Reuters — Nasdaq, S&P 500 decline with tech; investors assess softer jobs data
    Used for equity-market context following the softer-than-expected jobs report.
  4. Reuters — Dollar slides after soft jobs report, yen surges
    Used for U.S. dollar and yen market reaction after the NFP release.
  5. Reuters — Gold gains after weak U.S. payrolls report
    Used for gold-market reaction and rate-expectation context after the payroll miss.
  6. HAAWKS internal tick-chart screenshots, captured July 2, 2026.
    Used for measured release-window market impact: USD/JPY 37 pips, EUR/USD 25 pips, XAU/USD 43 points, and US500 56 ticks.

Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

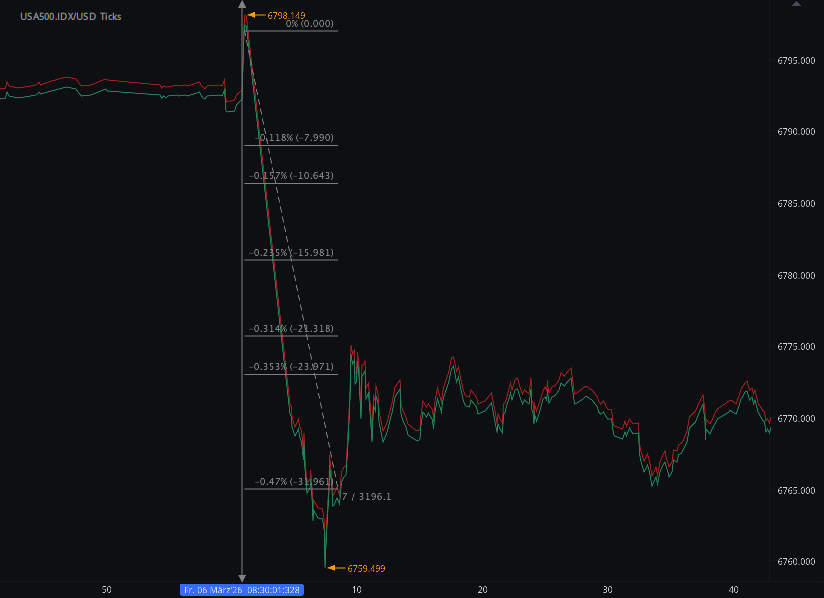
XAUUSD 16 points, US500 31 points potential profit in 24 seconds on 6 March 2026, analysis on forex fx futures news trading XAUUSD (spot gold) and US500 on US Employment Situation (NFP)

According to our analysis XAUUSD (spot gold) moved 16 points and US500 moved 31 points on US Employment Situation (Non-farm payrolls / NFP) data on 6 March 2026.

XAUUSD (16 points)

US500 (31 points)

Charts are exported from JForex (Dukascopy).


U.S. Jobs Report – February 2026: Payrolls Slip While Unemployment Holds Steady

The U.S. labor market showed signs of cooling in February 2026, according to the latest Employment Situation report from the Bureau of Labor Statistics (BLS). While the unemployment rate remained relatively stable, total nonfarm payroll employment declined slightly, highlighting a labor market that is still resilient but facing pockets of weakness across certain industries.

Payroll Employment Declines Slightly

Total nonfarm payroll employment fell by 92,000 jobs in February, reversing part of January’s gain of 126,000 jobs. The drop was largely influenced by job losses in specific sectors, particularly health care, information, and federal government employment.

Despite the monthly decline, the broader labor market picture remains mixed rather than sharply negative. Job growth throughout 2025 had already slowed considerably, and February’s figures suggest a continuation of that gradual moderation.

Unemployment Rate Holds at 4.4%

The unemployment rate remained unchanged at 4.4%, with approximately 7.6 million people unemployed in February. Across demographic groups—including adult men, adult women, teenagers, and major racial and ethnic categories—unemployment rates showed little change during the month.

However, one area of concern is long-term unemployment. The number of individuals unemployed for 27 weeks or longer reached 1.9 million, up from 1.5 million a year ago. Long-term unemployed workers now account for 25.3% of all unemployed people.

Labor Force Participation Remains Flat

Labor force participation and employment ratios also showed minimal movement:

  • Labor force participation rate: 62.0%

  • Employment-population ratio: 59.3%

Both measures have remained relatively stable over the past year. However, new population estimates from the U.S. Census Bureau affected the underlying data, particularly due to demographic shifts such as fewer men aged 25–54 and more women aged 65 and older—groups that historically participate in the workforce at different rates.

Sector Breakdown: Where Jobs Were Lost and Gained

Several industries experienced notable changes in February:

Health Care
Employment declined by 28,000 jobs, largely due to strike activity affecting physicians’ offices, which lost 37,000 jobs. Hospitals, however, added 12,000 positions.

Information Sector
The information industry continued its downward trend, shedding 11,000 jobs in February and averaging monthly losses over the past year.

Federal Government
Federal employment fell by 10,000 jobs. Since October 2024, federal employment has declined by 330,000 positions, representing an 11% drop.

Social Assistance
One of the few areas of consistent growth, social assistance added 9,000 jobs, primarily in individual and family services.

Transportation and Warehousing
Employment was mostly unchanged overall but saw losses in courier and messenger services, partially offset by gains in air transportation.

Wage Growth Continues

Despite softer employment numbers, wage growth remained solid.

  • Average hourly earnings: $37.32 (up $0.15 in February)

  • Year-over-year wage growth: 3.8%

Production and nonsupervisory employees saw earnings rise to $32.03 per hour, reflecting steady—though not accelerating—income growth for workers.

Workweek and Hours

The average workweek remained stable:

  • All private employees: 34.3 hours

  • Manufacturing: 40.1 hours (slightly lower)

  • Overtime in manufacturing: 3.0 hours

Stable hours suggest that employers are maintaining current staffing levels rather than significantly expanding or cutting back.

Data Revisions

The BLS also revised previous job numbers:

  • December 2025: Revised from +48,000 to –17,000

  • January 2026: Revised from +130,000 to +126,000

These revisions mean employment for those two months combined is 69,000 lower than previously reported.

Population Data Adjustments

February’s report also incorporated updated population estimates based on the 2020 Census. These revisions affected measures like labor force participation but did not change the unemployment rate.

The updated data indicates:

  • A decline in the number of men aged 25–54

  • An increase in women aged 65 and older

  • Changes in the racial composition of the population, including increases in Asian and multiracial populations

These demographic shifts slightly lowered overall labor force participation estimates.

What It Means for the Economy

February’s employment report paints a picture of a labor market that is stable but slowing. Unemployment remains low by historical standards, and wages continue to rise. However, job growth is weakening, certain industries are contracting, and long-term unemployment is creeping upward.

Economists will be watching closely to see whether February’s job losses represent temporary disruptions—such as strike activity—or the beginning of a more pronounced labor market slowdown.

The next Employment Situation report, covering March 2026, will be released on April 3, 2026.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

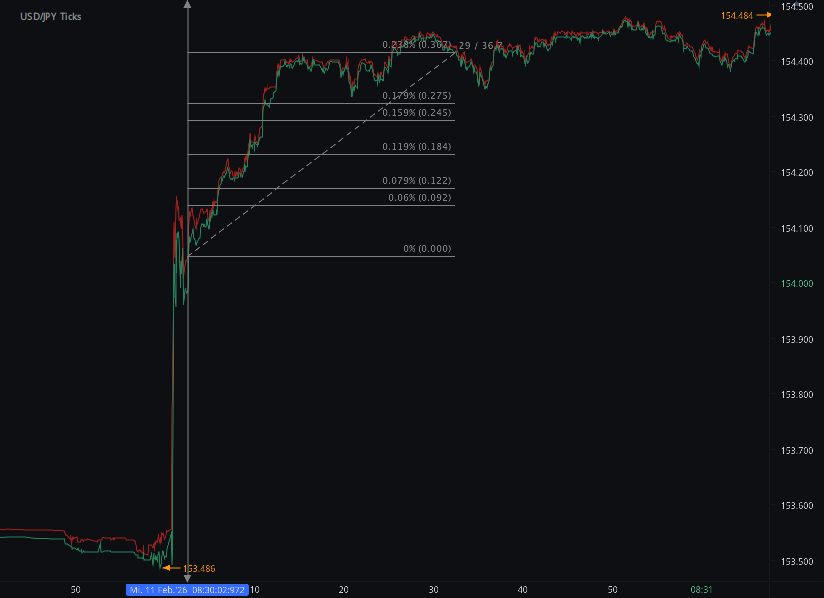
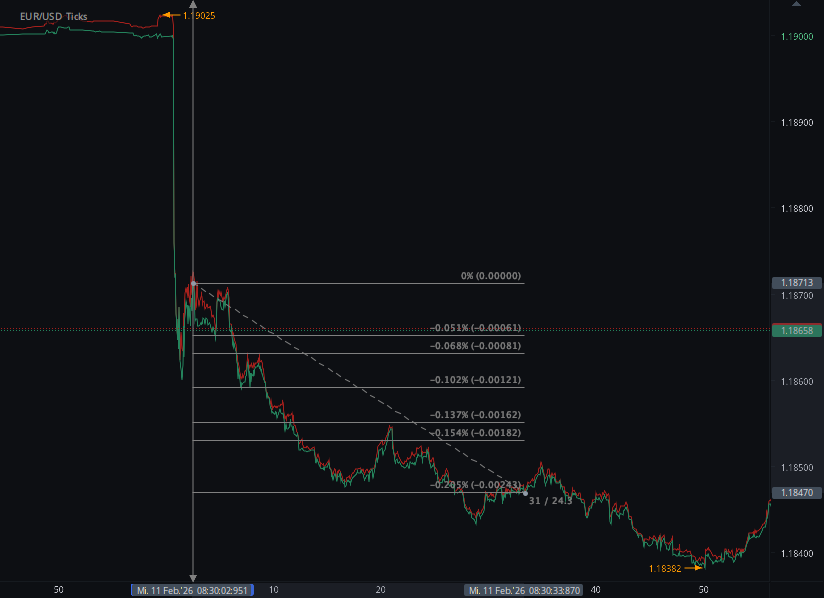
60 pips potential profit in 31 seconds on 11 February 2026, analysis on forex fx futures news trading USDJPY and EURUSD on US Employment Situation (NFP)

According to our analysis USDJPY and EURUSD moved 60 pips on US Employment Situation (Non-farm payrolls / NFP) data on 11 February 2026.

USDJPY (36 pips)

EURUSD (24 pips)

Charts are exported from JForex (Dukascopy).


U.S. Jobs Report – January 2026

Payrolls Rise by 130,000; Unemployment Rate Steady at 4.3%

The latest Employment Situation report from the U.S. Bureau of Labor Statistics shows a modest start to 2026. In January, total nonfarm payroll employment increased by 130,000 jobs, while the unemployment rate held steady at 4.3%.

Here’s what the numbers reveal about the current state of the labor market.

The Big Picture

  • 130,000 jobs added in January

  • Unemployment rate: 4.3% (unchanged)

  • Average hourly earnings: Up 0.4% to $37.17

  • Year-over-year wage growth: 3.7%

  • Labor force participation rate: 62.5% (little change)

While job growth continues, it remains moderate compared with historical expansion periods. The unemployment rate is slightly higher than a year ago (4.0% in January 2025), suggesting some cooling compared to last year.

Where Jobs Are Growing

Health Care Leads

Health care added 82,000 jobs in January:

  • +50,000 in ambulatory health care services

  • +18,000 in hospitals

  • +13,000 in nursing and residential care facilities

Health care averaged 33,000 jobs per month in 2025, making January’s increase notably strong.

Social Assistance Expands

Employment in social assistance rose by 42,000 jobs, primarily in individual and family services, reflecting continued demand for community-based support services.

Construction Rebounds

Construction added 33,000 jobs, largely in nonresidential specialty trade contractors (+25,000). After being essentially flat in 2025, the sector showed renewed momentum in January.

Sectors Losing Jobs

Not all industries expanded:

  • Federal government employment declined by 34,000, continuing a downward trend that began after a peak in October 2024. Since then, federal payrolls are down 327,000 jobs (−10.9%).

  • Financial activities fell by 22,000 jobs, including losses in insurance carriers.

These declines partially offset gains in health care and construction.

Household Survey Highlights

The household survey shows a largely stable labor market:

  • 7.4 million unemployed Americans

  • Long-term unemployed (27+ weeks): 1.8 million

  • Long-term unemployed account for 25% of all unemployed

Teen unemployment declined to 13.6%, while unemployment rates for adult men (3.8%), adult women (4.0%), and major racial and ethnic groups were largely unchanged.

The number of people working part time for economic reasons fell by 453,000 in January, though it remains higher than a year ago.

Wages and Hours

Wage growth remains steady:

  • Average hourly earnings: $37.17

  • Up 15 cents (0.4%) in January

  • Up 3.7% over the past year

For production and nonsupervisory workers:

  • $31.95 per hour

  • Also up 0.4% over the month

The average workweek edged up to 34.3 hours, suggesting stable labor demand.

Revisions and Benchmarking

The January release includes annual benchmark revisions:

  • March 2025 total nonfarm employment was revised down by 898,000 (seasonally adjusted).

  • 2025 job growth was revised from +584,000 to +181,000.

These revisions reflect updated payroll data from unemployment insurance records and improved seasonal adjustments — a standard statistical process designed to enhance accuracy.

Weather Impact?

Major winter storms affected large parts of the country in January. According to the BLS, they had no discernible impact on national payroll employment or unemployment rates, though survey response rates were slightly below average.

What This Means

January’s report shows:

  • Continued but moderate job growth

  • Stable unemployment

  • Solid wage gains

  • Sector-specific strength in health care and services

  • Ongoing weakness in federal government and financial activities

Overall, the labor market remains resilient but is expanding at a measured pace. The next Employment Situation report, due in early March, will provide further insight into whether this steady trend continues.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

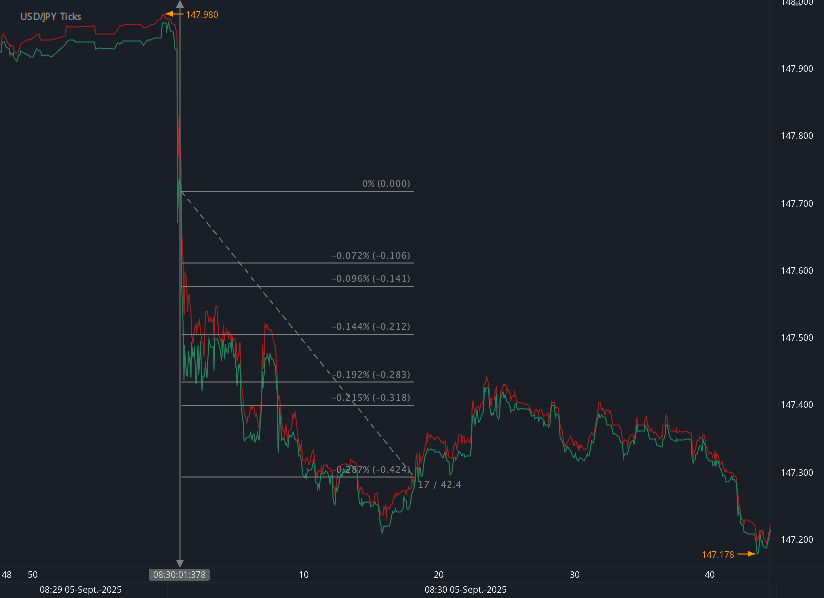
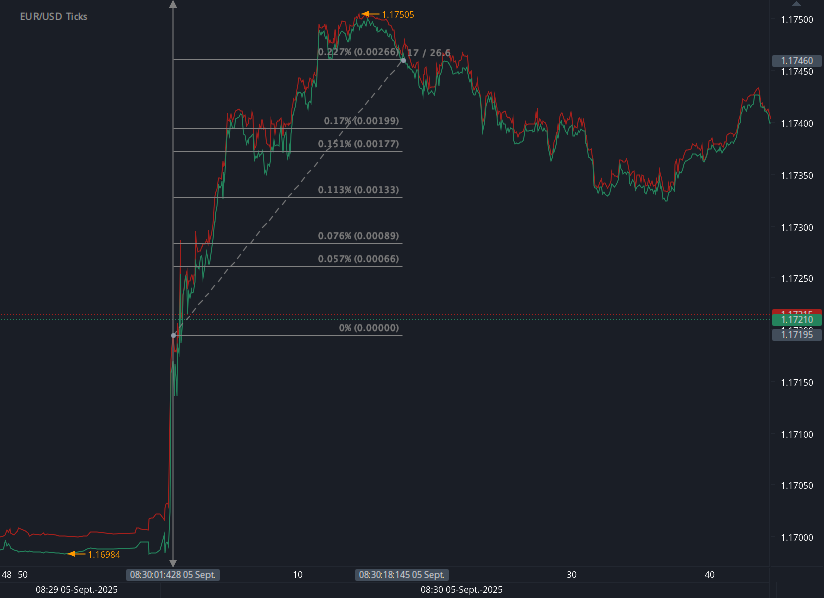
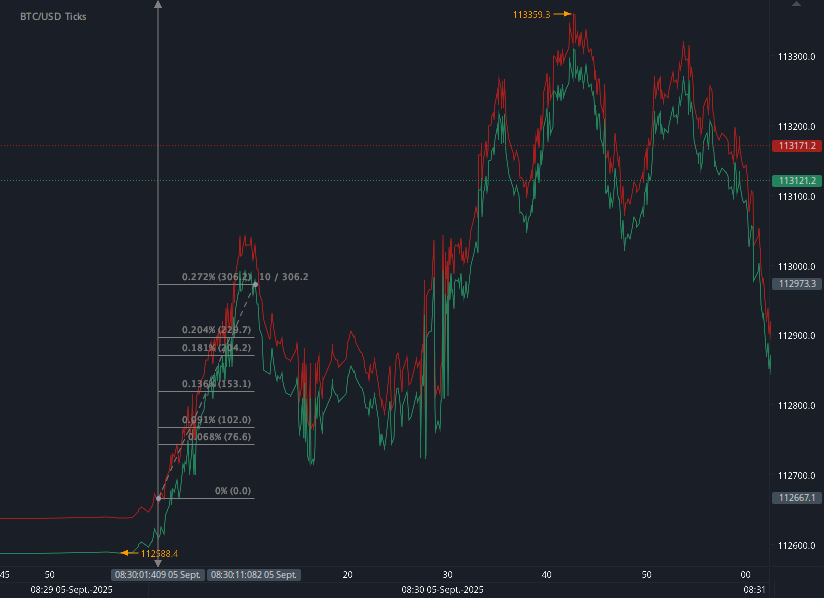
68 pips and BTC 306 points potential profit in 17 seconds on 5 September 2025, analysis on forex fx futures news trading USDJPY, EURUSD and BTC on US Employment Situation (NFP)

According to our analysis USDJPY and EURUSD moved 68 pips and BTC moved 306 points on US Employment Situation (Non-farm payrolls / NFP) data on 5 September 2025.

USDJPY (42 pips)

EURUSD (26 pips)

BTC (306 points)

Charts are exported from JForex (Dukascopy).


U.S. Jobs Report: August 2025 Employment Situation

The U.S. labor market showed little momentum in August 2025, according to the latest report from the Bureau of Labor Statistics (BLS). Nonfarm payroll employment edged up by just 22,000 jobs, while the unemployment rate held steady at 4.3%. Since April, overall job growth has been subdued, with gains in health care tempered by losses in government and energy-related industries.

Key Highlights from the Household Survey

  • Unemployment rate: 4.3%, essentially unchanged for the month.

  • Number of unemployed people: 7.4 million.

  • Long-term unemployment: 1.9 million, accounting for 25.7% of all unemployed, and up 385,000 over the past year.

  • Labor force participation: 62.3%, down 0.4 percentage point over the year.

  • Employment-population ratio: 59.6%, unchanged from July but also down over the year.

  • Part-time for economic reasons: 4.7 million, little changed in August.

  • Not in the labor force but want a job: 6.4 million, up 722,000 compared to last year.

Unemployment rates across major demographic groups—adult men (4.1%), adult women (3.8%), teenagers (13.9%), Whites (3.7%), Blacks (7.5%), Asians (3.6%), and Hispanics (5.3%)—showed little or no movement.

Key Highlights from the Establishment Survey

  • Total payroll employment: +22,000 jobs in August.

  • Health care: +31,000 jobs, led by gains in ambulatory services, hospitals, and nursing/residential care.

  • Social assistance: +16,000 jobs, mainly in individual and family services.

  • Federal government: -15,000 jobs, continuing a steady decline since January (down 97,000 total).

  • Mining, quarrying, and oil & gas extraction: -6,000 jobs, the sharpest monthly drop in over a year.

  • Wholesale trade: -12,000 jobs, down 32,000 since May.

  • Manufacturing: -12,000 jobs, with a notable -15,000 decline in transportation equipment manufacturing, partly due to strike activity.

Other major sectors—including construction, retail trade, financial activities, leisure and hospitality—showed little change in August.

Wages and Work Hours

  • Average hourly earnings: $36.53, up 10 cents (0.3%) in August. Over the past year, wages increased by 3.7%.

  • Production and nonsupervisory employees: $31.46 per hour, up 12 cents (0.4%).

  • Average workweek: 34.2 hours for all employees, unchanged for the third straight month.

  • Manufacturing workweek: slipped slightly to 40.0 hours, with overtime steady at 2.9 hours.

Revisions to Prior Months

  • June 2025 revised down to -13,000 (from +14,000).

  • July 2025 revised up to +79,000 (from +73,000).

  • Combined revisions: net 21,000 fewer jobs than previously reported.

What’s Next?

The September Employment Situation Report will be released on Friday, October 3, 2025. In addition, the BLS will issue its 2025 preliminary benchmark revision to payroll data on September 9, 2025, aligning survey estimates with unemployment insurance records.

Takeaway

The August report underscores a cooling labor market: job gains remain concentrated in health and social services, while government, manufacturing, and energy sectors shed jobs. Wage growth continues at a moderate pace, but labor force participation remains historically low. With revisions showing weaker summer job growth than initially reported, policymakers and businesses alike may be watching closely for signs of whether this slowdown persists into the fall.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

157 pips and BTC 158 points potential profit in 305 seconds on 1 August 2025, analysis on forex fx futures news trading USDJPY, EURUSD and BTC on US Employment Situation (NFP)

According to our analysis USDJPY and EURUSD moved 157 pips and BTC moved 158 points on US Employment Situation (Non-farm payrolls / NFP) data on 1 August 2025.

USDJPY (76 pips)

EURUSD (81 pips)

BTC (158 points)

Charts are exported from JForex (Dukascopy).


July 2025 Jobs Report: U.S. Labor Market Shows Minimal Growth Amid Mixed Signals

The U.S. Bureau of Labor Statistics (BLS) released its July 2025 Employment Situation report, and the labor market continues to show signs of a cooling trend. With just 73,000 jobs added, the monthly job growth has remained tepid since April. The unemployment rate was unchanged at 4.2%, signaling a labor market in a holding pattern as economic uncertainty lingers.

Key Takeaways from July 2025:

Sluggish Job Growth

  • Nonfarm payroll employment rose by only 73,000, well below the average gains seen earlier in the year.

  • Revisions to previous months were significant: May was revised down by 125,000 jobs and June by 133,000, meaning a combined loss of 258,000 jobs from earlier estimates.

Unemployment Rate Holds Steady

  • The unemployment rate remained at 4.2%, largely unchanged since May 2024.

  • The number of unemployed people stood at 7.2 million.

Employment Trends by Sector:

Gains

  • Health care added 55,000 jobs, continuing a strong upward trend. Key contributors were:

    • Ambulatory health care services: +34,000

    • Hospitals: +16,000

  • Social assistance rose by 18,000, mainly driven by:

    • Individual and family services: +21,000

Losses

  • Federal government employment dropped by 12,000 in July and has declined by 84,000 since January.

No Significant Change

  • Industries such as manufacturing, construction, retail, professional services, and leisure and hospitality saw little to no movement.

Worker Demographics and Labor Force Participation:

  • Labor force participation rate: 62.2% (unchanged for the month, down 0.5 percentage points over the year)

  • Employment-population ratio: 59.6% (also little changed)

  • Long-term unemployed (27 weeks or more): Up 179,000 to 1.8 million, making up 24.9% of total unemployed

  • New entrants to the labor force (seeking their first job): Up 275,000 to 985,000

  • Discouraged workers: Decreased by 212,000 to 425,000, following an increase in the prior month

Wages and Work Hours:

  • Average hourly earnings for private nonfarm employees increased by $0.12 (0.3%) to $36.44

  • Over the past 12 months, wages rose by 3.9%

  • Average workweek: Increased slightly by 0.1 hour to 34.3 hours

Looking Ahead

While health care and social services continue to show resilience, the broader employment landscape is stagnating. Job creation has softened significantly, revisions to past reports indicate weaker momentum than previously thought, and long-term unemployment is creeping up.

The next jobs report—covering August—will be released on Friday, September 5, 2025. Additionally, the preliminary 2025 benchmark revision to employment data will be released on September 9, 2025, offering a deeper look into the actual state of the labor market using QCEW data.

Bottom Line: The July 2025 labor market report points to a slow summer for job growth. While wage gains and stable unemployment offer some reassurance, shrinking revisions and rising long-term unemployment suggest that the labor market is cooling more quickly than previously thought.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

61 pips potential profit in 26 seconds on 3 July 2025, analysis on forex fx futures news trading USDJPY and EURUSD on US Employment Situation (NFP)

According to our analysis USDJPY and EURUSD moved 61 pips on US Employment Situation (Non-farm payrolls / NFP) data on 3 July 2025.

USDJPY (40 pips)

EURUSD (21 pips)

Charts are exported from JForex (Dukascopy).


July 2025 U.S. Jobs Report: Modest Gains Fuel Cautious Market Response

The U.S. Bureau of Labor Statistics released its June 2025 Employment Situation Report on July 3, revealing moderate but steady growth in the labor market. Nonfarm payrolls rose by 147,000, aligning closely with the 12-month average gain of 146,000. The unemployment rate held steady at 4.1%, showing little change from previous months and continuing the trend of a relatively tight labor market.

Key Highlights from the Report:

  • State Government and Health Care led job creation, adding 47,000 and 39,000 jobs respectively.

  • Federal Government employment declined by 7,000, bringing the total loss since January to 69,000.

  • Average hourly earnings increased by 0.2% to $36.30, while wages for production and nonsupervisory workers climbed 0.3% to $31.24.

  • Long-term unemployment rose by 190,000 to 1.6 million, now accounting for 23.3% of the total unemployed.

  • The labor force participation rate remained unchanged at 62.3%.

Market Reaction: USDJPY and EURUSD Move Modestly

Despite the data being mostly in line with expectations, forex markets saw mild volatility in response to the release:

  • USDJPY rose by 40 pips, signaling modest dollar strength likely tied to steady wage growth and job gains.

  • EURUSD slipped by 21 pips, a subdued reaction reflecting limited surprises in the report.

Overall, the total move across USDJPY and EURUSD was 61 pips, indicating a muted but focused market response, particularly ahead of the long U.S. holiday weekend.

What It Means for Traders

The June report did little to shake market sentiment but reaffirmed the narrative of gradual economic cooling without triggering recession fears. Wage growth remains solid, and job creation—though slower than earlier in the recovery—is still healthy. With the Fed watching inflation and labor market metrics closely, this report may not alter near-term rate expectations significantly but reinforces a “wait-and-see” stance.

Looking ahead, the next Employment Situation Report is scheduled for Friday, August 1, 2025, which could play a more pivotal role in shaping monetary policy expectations as more data accumulate.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

37 pips, US500 11 points and BTC 209 points potential profit in 18 seconds on 6 June 2025, analysis on forex fx futures news trading USDJPY, EURUSD, US500 and BTC on US Employment Situation (NFP) data

According to our analysis USDJPY and EURUSD moved 37 pips, US500 moved 11 points and BTC moved 209 points on US Employment Situation (Non-farm payrolls / NFP) data on 6 June 2025.

USDJPY (24 pips)

EURUSD (13 pips)

US500 (11 points)

BTC (209 points)

Charts are exported from JForex (Dukascopy).


U.S. Job Market Update: May 2025 Shows Steady Growth but Signs of Cooling

The U.S. labor market maintained moderate momentum in May 2025, according to the latest report from the Bureau of Labor Statistics (BLS), with total nonfarm payroll employment rising by 139,000 jobs. The unemployment rate held steady at 4.2%, continuing a 12-month trend of hovering between 4.0% and 4.2%.

Key Highlights

  • Job Growth by Sector:

    • Health Care led the way with +62,000 jobs, particularly in hospitals and ambulatory services.

    • Leisure and Hospitality added +48,000 jobs, mostly in food services and bars.

    • Social Assistance grew by +16,000 jobs, continuing its steady upward trend.

    • Federal Government employment continued to decline, down 22,000 jobs in May and 59,000 since January.

  • Wages and Hours:

    • Average hourly earnings rose by $0.15 to $36.24, a 0.4% monthly increase, and 3.9% over the past year.

    • The average workweek held steady at 34.3 hours.

  • Labor Force Metrics:

    • The employment-population ratio slipped to 59.7%, and labor force participation decreased to 62.4%.

    • Long-term unemployment dropped by 218,000 to 1.5 million, making up 20.4% of total unemployment.

    • Those jobless for less than 5 weeks rose by 264,000 to 2.5 million.

Revisions & Notes

  • March and April job gains were revised downward by a combined 95,000 jobs, suggesting the labor market may be slightly weaker than previously believed.

  • A minor correction was made to April’s household survey data due to the rollout of a redesigned sample.

  • A shift in classification of certain New York state workers impacted industry employment counts, transferring jobs from health care to social assistance.

Takeaway

The May report signals a job market that remains resilient but cautious. While job growth continues, it’s slower than the pace seen earlier in the recovery. Wage growth is steady, but softening participation and revisions to previous months hint at underlying labor market fragility. All eyes will be on the June report, due July 3, for confirmation of any emerging trends.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment

Comment

19 pips, US500 19 points and BTC 192 points potential profit in 92 seconds on 2 May 2025, analysis on forex fx futures news trading USDJPY, US500 and BTC on US Employment Situation (NFP) data

According to our analysis USDJPY, US500 and BTC moved 19 pips, 19 points and 192 points on US Employment Situation (Non-farm payrolls / NFP) data on 2 May 2025.

USDJPY (19 pips)

US500 (19 points)

BTC (192 points)

Charts are exported from JForex (Dukascopy).


April 2025 Jobs Report: Steady Growth with a Few Soft Spots

The U.S. labor market continued its slow but steady climb in April 2025, according to the latest data from the Bureau of Labor Statistics (BLS). Nonfarm payrolls increased by 177,000, a solid gain that’s slightly above the average monthly increase of 152,000 over the past year. Meanwhile, the unemployment rate held steady at 4.2%, continuing a nearly year-long trend of relative stability in joblessness.

Key Takeaways:

Job Growth Driven by Health Care and Transportation

  • Health care led the way with 51,000 new jobs, continuing its strong performance from previous months. Hospitals and ambulatory health care services were major contributors.

  • Transportation and warehousing added 29,000 jobs, with gains in warehousing and storage (+10,000), couriers and messengers (+8,000), and air transportation (+3,000).

Other Industries on the Rise

  • Financial activities added 14,000 jobs, bringing total gains since April 2024 to over 100,000.

  • Social assistance employment rose by 8,000, though at a slower pace than usual.

Federal Government Job Cuts

  • Federal employment fell by 9,000 jobs in April and is down 26,000 since January. This marks a continued contraction in the public sector.

Other Notable Stats:

  • The number of unemployed people remained at 7.2 million.

  • Long-term unemployment rose to 1.7 million, making up 23.5% of all unemployed persons.

  • The labor force participation rate stayed flat at 62.6%, and the employment-population ratio held at 60.0%.

  • Wages continue to grow modestly:

    • Average hourly earnings rose by 6 cents to $36.06, up 3.8% year-over-year.

    • Nonsupervisory workers saw a 10-cent gain to $31.06.

Revisions & Trends

The jobs numbers from February and March were revised down by a total of 58,000 jobs, tempering earlier optimism. While these revisions don't indicate a major downturn, they reflect the continued balancing act of a cooling economy with pockets of resilience.

Bottom Line:

April’s jobs report reflects a labor market that’s stable, but not booming. Most of the gains are concentrated in a few key sectors, while other areas — including government — are shedding jobs. Wage growth is modest, and the overall unemployment rate remains within a narrow range.

With the next employment report due June 6, attention will remain focused on whether this steady trajectory can be maintained amid ongoing economic uncertainties.

Disclaimer: This blog post is for informational purposes only and should not be construed as financial advice. Always conduct thorough research and consider seeking advice from a financial professional before making any investment decisions.

Source: https://www.bls.gov/news.release/empsit.nr0.htm


Start forex fx futures news trading with Haawks G4A low latency machine-readable data today, one of the fastest news data feeds for US macro-economic and commodity data.

Please let us know your feedback. If you are interested in timestamps, please send us an email to sales@haawks.com.

Comment